<?xml version='1.0' encoding='UTF-8'?>
<items>
	<item>
		<title>Inflation Ignites Again As Oil Prices Ease</title>
		<description><![CDATA[<p><strong>Susannah Streeter, Chief Investment Strategist, Wealth Club: </strong>&ldquo;Inflation has slipped from the reins and is running higher again, and coaxing the price spiral down looks set to be painful. The headline CPI rate hit 3.1% in August, up from 2.9% in July, racing further away from the Bank&rsquo;s 2% target. The impact of the war in Iran is showing up starkly, with higher crude prices feeding through to the pumps. It feels like Groundhog Day, with consumers once again feeling the pinch due to geopolitical events far beyond their control. The average price of petrol stood at 161.3 pence per litre in August 2026, which was the highest price recorded since November 2022. But since then they&rsquo;ve ramped up even higher, and more increases look set to be on the way given that crude has jumped so sharply.</p>

<p>The picture is not uniformly grim though, with food inflation holding at 1.3% and services inflation stuck at 3.4%, while core CPI, which strips out volatile food and fuel moves, remained at 2.6%. But there will still be concerns that businesses will start passing higher energy costs on as higher prices for goods and services.</p>

<p>Given this ramp-up in consumer prices, the pressure on the Bank of England to raise rates is mounting, although a hold at 3.75% is still expected tomorrow. The bigger shift is happening in expectations for the months ahead, with markets now pricing in multiple hikes as the energy shock threatens to keep inflation elevated. That is going to pile on the financial pain for those looking to remortgage or get onto the housing ladder. With energy costs rising and borrowing costs looking set to surge higher, there looks set to be a fresh squeeze on spending, so consumers are going to become even choosier about where they spend their available cash.</p>

<p>Nevertheless, it appears investors have become used to this cycle of warnings about inflationary pressures, and are set to shrug off this latest snapshot. The FTSE 100 is set for some gains in early trading, while Wall Street futures also point to a sanguine opening even as attention is trained on the upcoming Fed meeting, with another hiking cycle in central bankers' sights. The chronic energy crunch, combined with accelerated spending on the AI build-out, risks tipping stubbornly high inflation even higher. The feeling is that the Fed won&rsquo;t be able to sit on its hands, and now an increase is widely expected &ndash; with a 92.4% chance of at least a 25-basis-point U.S. rate hike today being factored in. The big question is how high could they go &ndash; with multiple hikes now expected over the next year.</p>

<p>But there is a little relief on the energy front this morning, with crude prices dipping after US inventories unexpectedly rose. American crude stocks increased by 7.1 million barrels last week, confounding expectations for a draw, while gasoline and distillate inventories also climbed. Brent slipped briefly back below $108 a barrel as a result but has begun climbing again.</p>

<p>So there's been some respite, but it was a small breather rather than the start of long-term relief. The underlying supply picture remains extremely tight, with a halt to crude exports at the Saudi port of Yanbu, due to drone attacks, adding to the concerns over how much crude can actually reach the market.</p>

<p>Every day appears to bring a fresh development in the conflict, making the supply picture even more fragile. Saudi Arabia&rsquo;s air defences shot down a Houthi drone south of Mecca, with the threat to the holy city another ominous twist in the conflict. The Houthis deny targeting Mecca, but the incident brings the war into stark reality for the kingdom, showing that the threat is no longer confined to oil installations and shipping lanes, but is now reaching towards the heart of the country&rsquo;s religious life.&rdquo;</p>

<p> </p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/inflation-ignites-again-as-oil-prices-ease-27185.htm</link>
<pubDate>Wed, 16 Sep 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Tpt Appoints Geoff Tookey As Head Of Trustee Services</title>
		<description><![CDATA[<p>Geoff&rsquo;s appointment comes as TPT continues to broaden the range of pension solutions available to schemes and employers. He will play a key role in ensuring the CDC and Superfund trustee boards receive coordinated support from across TPT, helping them to make well-informed decisions and maintain a strong focus on positive long term member outcomes.</p>

<p>Geoff brings with him over twenty years of experience in pensions. He joins TPT from Bank of America where he was Head of Pensions for UK & Ireland. Following pension consulting roles at WTW and KPMG, Geoff moved to O2 as Pensions and Benefits manager, later progressing to Head of Pensions at Virgin Media O2. Geoff is a qualified actuary.</p>

<p><strong>Commenting on the appointment, Andy O&rsquo;Regan, Chief Client Strategy Officer at TPT Retirement Solutions, said:</strong> &ldquo;Geoff joins TPT at an important stage in our growth, as we continue to broaden the range of pension solutions we offer to schemes and employers. As our business grows, maintaining high governance standards will be critical and Geoff will be instrumental in ensuring we continue to deliver for our members.&ldquo;</p>

<p><strong>Geoff Tookey, Head of Trustee Services, at TPT Retirement Solutions, said:</strong> &ldquo;It is an exciting time to join TPT. It has a clear and innovative vision for the future of pensions, and I look forward to working closely with our trustees to deliver better outcomes for our members.&rdquo;</p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/tpt-appoints-geoff-tookey-as-head-of-trustee-services-27189.htm</link>
<pubDate>Wed, 16 Sep 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Private Markets Larger Role In Future Pension Defaults</title>
		<description><![CDATA[<p>Private market investing could play a larger role in the evolution of pension defaults in the UK over the next decade, according to new analysis from Standard Life and WPI Economics.</p>

<p>The report, <a href="https://www.actuarialpost.co.uk/downloads/cat_1/Standard-Life-From-scale-to-impact-June-2026.pdf"><strong>From Scale to Impact: A Blueprint for the Future DC Pensions Market</strong></a>, explores how consolidation and pension reforms could reshape how default funds invest. It sets out how larger schemes could build more diversified portfolios and increase exposure to private markets.</p>

<p>With a long-term outlook, the research projects that the UK workplace DC market could be dominated by 10 to 15 larger pension schemes by 2035, each managing more than &pound;50 billion of assets. Under this scenario, default funds could potentially allocate between 15% and 30% of assets to private markets during the growth phase of retirement saving, compared with around 2% to 4% today1.</p>

<p>It&rsquo;s also anticipated that the range of private assets within defaults will broaden. Rather than concentrating exposure in a single asset class, the blueprint sets out a scenario in which future default funds invest across a broad mix of private market assets. Private equity and venture capital could account for 30% to 50% of private market allocations, private credit 20% to 40%, and infrastructure and real assets 20% to 40%2. This mix could support more diversified portfolios and stronger long-term outcomes for savers by combining different sources of return and risk.</p>

<p>The report suggests private credit is likely to play an increasingly important role in helping schemes manage liquidity and downside risk. Infrastructure investments could provide long-term, inflation-linked cashflows and diversification benefits, helping to smooth returns over time, while private equity and venture capital are expected to remain important drivers of long-term growth and value creation.</p>

<p>The findings indicate that UK DC schemes could begin to look more like their international counterparts. Australian superannuation funds currently invest around 17% of assets in private markets, with some growth-stage strategies allocating up to 40%, while Canadian public pension funds allocate around a quarter of assets to private markets. However, the composition of those allocations differs. Australian investors have tended to place greater emphasis on infrastructure and real assets, while Canadian funds typically allocate more heavily to private equity and venture capital. The blueprint suggests future UK default funds are likely to draw on both approaches, combining infrastructure's diversification and inflation-protection characteristics with the growth potential offered by private equity and venture capital.</p>

<p>While maintaining global diversification, the report argues that future schemes are likely to retain a meaningful domestic bias within their private market allocations. It estimates that 30% to 50% of private market investments could be allocated to UK opportunities, compared with around 5% to 10% of listed equity investments. As private market allocations grow, this could materially increase the volume of pension capital flowing into UK infrastructure, businesses and other productive assets.</p>

<p>By 2035, the report estimates that between &pound;40 billion and &pound;200 billion of DC pension assets could be invested in UK private markets under this approach, compared with an estimated &pound;2 billion to &pound;3 billion invested in private markets by today&rsquo;s master trusts.</p>

<p><strong>Jenny Holt, Product Director at Standard Life, said:</strong> &quot;Interest in private markets has grown significantly in recent years, but adoption across the workplace pensions market is developing at different speeds.</p>

<p>&quot;This research explores how the DC market could evolve over the longer term if schemes continue to consolidate and gain greater scale. In that environment, larger schemes may be better placed to access a broader range of investment opportunities and build more diversified portfolios.</p>

<p>&quot;Ultimately, the focus should not be on allocation targets alone, but on the value private market investments can deliver for members. Different schemes are likely to take different approaches as the market develops, but any investment strategy should remain focused on improving member outcomes, delivering value for money and being supported by strong governance and a clear investment rationale.&quot;</p>

<p><strong>Joe Ahern, Director of Policy at WPI Economics, said:</strong> &ldquo;Scale changes what pension schemes can invest in and how they invest. Larger schemes are better positioned to access a wider range of opportunities, build specialist expertise and construct more diversified portfolios across different private market asset classes.</p>

<p>&ldquo;The challenge now is ensuring the wider regulatory and commercial environment supports schemes in accessing those opportunities while maintaining a relentless focus on delivering value for savers.&rdquo;</p>

<p>The report argues that greater scale, a stronger focus on value rather than cost, and reforms to support investment in illiquid assets will be necessary if schemes are to adopt these strategies at scale while maintaining a focus on delivering good pension outcomes for pension savers.</p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/private-markets-larger-role-in-future-pension-defaults-27186.htm</link>
<pubDate>Wed, 16 Sep 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>100 Years After The Great Miami Hurricane</title>
		<description><![CDATA[<p>One hundred years ago this month, the Great Miami Hurricane struck South Florida, devastating a young and rapidly growing city. On the centenary of the September 18, 1926 landfall, new Swiss Re Institute analysis shows how the stakes have changed: a Category 5 hurricane striking the Miami or Tampa Bay area today could generate insured losses of USD 300 billion or more. The scenario illustrates how population growth and the accumulation of assets in exposed areas are driving higher insured natural catastrophe losses globally.</p>

<p><strong>Balz Grollimund, Head Catastrophe Perils at Swiss Re, said:</strong> &quot;The Atlantic hurricane season has been relatively quiet so far this year, but it only takes one major storm making landfall in a highly exposed area to turn a quiet season into a costly one. One hundred years after the Great Miami Hurricane, the question is not simply how powerful the next major hurricane will be, but what it will encounter when it reaches shore. That lesson extends well beyond Florida: as populations and asset values increase in areas exposed to natural catastrophes, so does the potential for large insured losses.&quot;</p>

<p>A century of population and property growth has transformed the potential impact of a hurricane striking Miami-Dade County. Just over 100,000 residents lived there when the Great Miami Hurricane arrived in 1926, compared with around 2.8 million in Miami-Dade today. More than two million homes in the Miami metropolitan area, with a combined reconstruction cost exceeding USD 600 billion, are now at moderate or greater risk of hurricane wind damage.</p>

<p>Where a hurricane makes landfall is critical. Hurricane Andrew struck around 20 miles south of Miami as a Category 5 storm in 1992, largely sparing Miami's much larger concentration of insured property. Swiss Re Institute estimates that the same track today would cause close to USD 100 billion in insured losses. By contrast, a Category 5 hurricane striking Miami or Tampa Bay could cause insured losses of USD 300 billion or more.</p>

<p>The centenary is also a resilience story. Traditional and alternative reinsurance capacity can be more effective when supported by catastrophe modelling, disciplined accumulation management and effective mitigation. Stronger building codes and wind-resistant construction can help reduce hurricane losses. Updated standards helped newer homes in Florida withstand Hurricane Ian in 2022, while replaced and storm-proofed roofs further reduced vulnerability.</p>

<p><strong>Monica Ningen, CEO US P&C Reinsurance at Swiss Re, said:</strong> &quot;Florida&rsquo;s growth has transformed the risk landscape, making it increasingly important for insurers, communities and policymakers to understand how exposure is changing. Stronger building standards have improved resilience, but continued population and property growth in exposed areas means the potential for severe losses remains significant. Effective mitigation and risk modelling can help manage that risk, while reinsurance helps insurers absorb the volatility of severe events.&quot;</p>

<p> </p>

<p>The English version of the sigma insights<a href="https://www.swissre.com/risk-knowledge/mitigating-climate-risk/the-great-miami-hurricane-100.html"> &quot;The Great Miami Hurricane at 100: hurricane loss potential could exceed USD 300 billion&quot;</a> </p>

<p> </p>

<p> </p>

<p> </p>

<p> </p>

<p> </p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/100-years-after-the-great-miami-hurricane-27190.htm</link>
<pubDate>Wed, 16 Sep 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Over  135bn Stashed In Cash Isas </title>
		<description><![CDATA[<div>Around &pound;135.7 billion was subscribed to adult ISAs in 2024 to 2025, an increase of &pound;32.7 billion compared to 2023 to 2024, with Stocks and Shares ISA subscriptions increasing by 20% (&pound;6.1 billion) to &pound;31.3 billion. However, the majority of this expansion was driven by the rise in Cash ISA subscriptions, which grew by 38% (&pound;26.1 billion) from &pound;69.5 billion to &pound;95.6 billion with the Bank of England bank rate and the interest swap rates at their highest levels during the 2023/24 and 2024/25 tax years.</div>

<div> </div>

<div><strong>Winston Ruddick, Senior Financial Planning Consultant at Broadstone, commented: </strong>&ldquo;Higher interest rates and looming reforms have turbocharged the appeal of Cash ISAs, with savers taking advantage of stronger returns to stash billions more pounds into these accounts. &ldquo;The scale of the increase is striking with higher savings rates clearly making cash a far more attractive proposition, while the tax-free wrapper has become increasingly valuable as more savers find their interest income exposed to tax.</div>

<div> </div>

<div>&ldquo;However, while cash has an important role to play for emergency savings and shorter-term needs, holding too much in cash over the long term can come at the cost of investment growth. The rise in Stocks and Shares ISA subscriptions is therefore encouraging, but the figures also underline the scale of the behavioural change the Government is seeking to achieve through its reforms.</div>

<div> </div>

<div>&ldquo;From April 2027, the annual Cash ISA limit for under-65s will fall to &pound;12,000, while the overall ISA allowance remains at &pound;20,000, meaning savers wanting to use their full allowance will need to put at least &pound;8,000 into investments rather than cash.</div>

<div> </div>

<div>&ldquo;With almost &pound;96 billion flowing into Cash ISAs in the latest year alone, the new rules could prompt a significant shift in where people put their savings. The challenge will be ensuring that people do not simply stop saving once they reach the new cash limit but instead understand the potential benefits of investing for longer-term goals.&rdquo;</div>

<div> </div>

<div><a href="https://www.gov.uk/government/statistics/annual-savings-statistics-2026/commentary-for-annual-savings-statistics-september-2026">HMRC Annual Savings Statistics</a></div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/over--135bn-stashed-in-cash-isas--27187.htm</link>
<pubDate>Wed, 16 Sep 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Enriched Vehicle Data Central To Motor Insurance Pricing</title>
		<description><![CDATA[<div><u><strong>By Tom Lawrie-Fussey, associate vice president of insurance product management, U.K. and Ireland, LexisNexis Risk Solutions</strong></u></div>

<div> </div>

<div>This suggests this more stable period may be under pressure. Our report shows how the U.K. car parc is changing. The average vehicle is now over 10 years old, while new manufacturers are entering the market at pace, particularly Chinese electric vehicle brands. Vehicle technology, including Advanced Driver Assistance Systems (ADAS), continue to evolve.  At the same time, claims costs remain under considerable pressure[iii].</div>

<div> </div>

<div>For actuaries and pricing teams, this means traditional assumptions are being tested in new ways. Understanding risk is no longer just about broad vehicle categories. It increasingly depends on individual vehicle characteristics supported by high-quality data.</div>

<div> </div>

<div><strong>Stability in customer behaviour should not be mistaken for stability in risk</strong></div>

<div>The LexisNexis Insurance Demand Meter U.K. for H2 2025 found that approximately 17,000 fewer consumers per day shopped for motor insurance during 2025 compared with the previous year. In the fourth quarter of 2025, only 21% of consumers who shopped for cover changed insurance provider, the lowest switching level recorded since early 2023.</div>

<div> </div>

<div>Motor insurance shopping has always been cyclical. When insurance renewal premiums remain relatively stable, as they did for much of 2025, consumers who do shop around for motor insurance may find there is little to gain from switching. In those circumstances, many choose to stay put. </div>

<div> </div>

<div>However, motor insurance providers continue to face elevated repair costs, increasingly complex vehicle technology and ongoing supply chain challenges. Even relatively minor collisions can require recalibration of sensors, replacement of specialist components or manufacturer-approved repair techniques.</div>

<div> </div>

<div>Against this backdrop, insurance providers are likely to be assessing whether current pricing remains sustainable. If premiums do start to rise, as Confused.com has reported[iv], shopping and switching activity may increase again.</div>

<div> </div>

<div><strong>An ageing car parc presents new pricing challenges</strong></div>

<div>A key finding from the latest LexisNexis Insurance Demand Meter U.K. is that the average insured vehicle value fell by almost &pound;1,000 between the second half of 2023 and the second half of 2025. Over the same period, the average age of insured vehicles increased to approximately ten years and five months.</div>

<div> </div>

<div>The reasons are understandable. Many motorists have delayed replacing vehicles[v] because of affordability concerns, higher borrowing costs and the ongoing cost-of-living crisis. There is likely to be an inflection point, though. As vehicles age, servicing costs tend to increase and MOT failures become more likely. Eventually, the cost of keeping an older vehicle on the road can outweigh its market value.</div>

<div> </div>

<div>Older cars are also far from uniform. Many contain different generations of ADAS. Some have received software updates throughout their life while others have not. Maintenance histories differ considerably, and repair methods can vary depending on age, manufacturer and previous repairs.</div>

<div> </div>

<div>Electric vehicles can have fewer mechanical servicing requirements than traditional internal combustion engine vehicles. However, battery condition, electronic systems, specialist repair capability and component availability can all affect insurance claims costs and residual values and ultimately, pricing assumptions.</div>

<div> </div>

<div>This is where more granular vehicle intelligence becomes essential. Understanding a vehicle&rsquo;s precise specification, equipment, powertrain and current market value can help pricing models better reflect actual exposure, rather than relying on broad assumptions.</div>

<div> </div>

<div><strong>The rapid rise of Chinese manufacturers</strong></div>

<div>Perhaps the most striking trend emerging from the latest LexisNexis Insurance Demand Meter U.K. is the continued growth of Chinese car brands. By the end of 2025, Chinese vehicle manufacturers represented 1.2% of personal motor insurance policies, compared with 0.6% in 2022. While this remains a relatively small share of the overall motor insurance market, the growth has been consistent and is expected to continue as more models reach U.K. roads. This shift is taking place alongside wider growth in electric vehicle registrations, with the Society of Motor Manufacturers and Traders (SMMT)[vi] reporting a 35% year on year increase in registrations of new battery electric vehicles.</div>

<div> </div>

<div>As Chinese car brands become more established, some of the insurance pricing uncertainty seen today may begin to ease[vii]. The granular vehicle data available to motor insurance providers should, in time, be complemented by a fuller understanding of claims experience, better availability of green parts and stronger repair networks.</div>

<div> </div>

<div><strong>Better data supports better decisions</strong></div>

<div>As the composition of the U.K. car parc continues to change, the motor insurance providers best equipped to respond will be those that combine actuarial expertise with rich, real time vehicle intelligence. That combination can support more accurate risk assessment, greater pricing confidence and better outcomes for customers, whether they choose to switch to an EV or stay with a vehicle they already know.</div>

<div> </div>

<div><em style="font-size:11px">[i] <a href="https://www.bbc.co.uk/news/uk-wales-66236110">https://www.bbc.co.uk/news/uk-wales-66236110</a></em></div>

<div><em style="font-size:11px">[ii] <a href="https://www.abi.org.uk/news/news-articles/2026/7/record3.2-billion-paid-out-to-support-motor-insurance-customers-in-q2-2026/">https://www.abi.org.uk/news/news-articles/2026/7/record3.2-billion-paid-out-to-support-motor-insurance-customers-in-q2-2026/</a></em></div>

<div><span style="font-size:11px"><em>[iii] <a href="https://www.abi.org.uk/news/news-articles/2026/7/record3.2-billion-paid-out-to-support-motor-insurance-customers-in-q2-2026/">https://www.abi.org.uk/news/news-articles/2026/7/record3.2-billion-paid-out-to-support-motor-insurance-customers-in-q2-2026/</a></em></span></div>

<div><span style="font-size:11px"><em>[iv] <a href="https://www.confused.com/compare-car-insurance/average-car-insurance-cost-uk">https://www.confused.com/compare-car-insurance/average-car-insurance-cost-uk</a></em></span></div>

<div><span style="font-size:11px"><em>[v] <a href="https://natcen.ac.uk/publications/evidence-review-exploring-how-car-ownership-changing-uk">https://natcen.ac.uk/publications/evidence-review-exploring-how-car-ownership-changing-uk</a></em></span></div>

<div><span style="font-size:11px"><em>[vi] <a href="https://www.smmt.co.uk/vehicle-data/car-registrations/">https://www.smmt.co.uk/vehicle-data/car-registrations/</a></em></span></div>

<div><span style="font-size:11px"><em>[vii] <a href="https://www.regit.cars/car-news/chinese-evs-cost-up-to-3x-more-to-insure-than-european-rivals-data-reveals">https://www.regit.cars/car-news/chinese-evs-cost-up-to-3x-more-to-insure-than-european-rivals-data-reveals</a></em></span></div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/enriched-vehicle-data-central-to-motor-insurance-pricing-27188.htm</link>
<pubDate>Wed, 16 Sep 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Red Sea Risks Fuels Inflation As Jobs Market Loses Momentum</title>
		<description><![CDATA[<p><em>Higher public sector pay awards, and the timing of them, have pushed up average pay to 3.9% - a measure which will be used to set the state pension increase, and is set to reignite the triple lock debate. </em><em>Stagflation fears risk returning, as a weakening jobs market collides with stubborn inflation and a fresh energy shock, leaving the Bank of England facing an increasingly awkward balancing act.</em></p>

<p><strong>Susannah Streeter, Chief Investment Strategist, Wealth Club: </strong>&ldquo;There&rsquo;s no let-up in the volatility rippling through financial markets, with energy prices staying painfully elevated and worries swirling about the knock-on effect for inflation and interest rates. A sea of red could be set to wash over indices, just as attention turns to the Red Sea and mounting threats to shipping and oil exports. The FTSE 100 is turning lower in early trade, and the sell-off hitting US markets this week, exacerbated by concerns about high risks of rapid AI advancements, looks set to continue.</p>

<p>Brent crude has climbed back to highly unwelcome levels, above $107 a barrel as supply concerns are back front and centre. There are more twists in Iran&rsquo;s story of retaliation, with escape routes for exports blocked off and passing the Strait of Hormuz remaining highly risky. Saudi Arabia&rsquo;s pipeline stretching from the East of the country to the Red Sea port of Yanbu is closed due to drone attacks, with repairs forecast to take weeks. Houthi rebels have seized the key Hanish islands, which now threaten ships&rsquo; passage through the Bab el-Mandeb Strait, the vital shipping route linking the Red Sea with the Gulf of Aden, raising the risk of further disruption to global oil flows. Given the can of worms which has been ripped open, with fresh threats popping up all over the place, it&rsquo;s not surprising it&rsquo;s adding another layer of pressure to highly watchful markets. The conflict has become more entrenched, with Iran clearly in this fight for the long haul, and it&rsquo;s led to fresh worries that higher energy costs will become embedded in economies, leaving companies with little choice but to hike prices on a vast range of goods.</p>

<p>That&rsquo;ll be concentrating the minds of the raft of central bankers meeting this week on both sides of the Atlantic to decide on rate hikes. The bond markets are reflecting concerns that the only way is up, and the worries that the ascent could be a steep one. 10-year gilt yields remain highly elevated at levels not seen since the Great Financial Crisis. It&rsquo;s a fraught picture for US Treasuries, with the 10-year Treasury yield also creeping over the psychologically important 5% mark, flirting with a rate not seen since 2007.</p>

<p>Corporate debt is proving to be a formidable rival to government debt offerings, with the hyperscalers increasingly tapping bond markets to fund the enormous cost of data centres, chips and computing capacity.</p>

<p>The latest jobs figures add another awkward piece of the picture for the UK economy, which may keep central bankers puzzling about how to react. Payrolled employment has fallen by 145,000 over the year, with another 26,000 people dropping off payrolls in August, while vacancies have slipped to 702,000, which is the lowest level outside the pandemic since 2014. Unemployment is holding at 4.9%, so while this is not a jobs market in freefall, businesses are clearly becoming more reluctant to take people on as labour and other costs remain painfully elevated.</p>

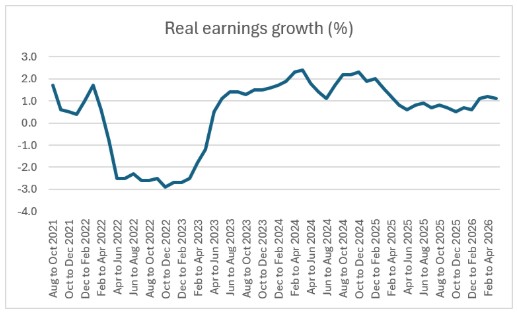
<p>Pay growth is cooling too, with regular earnings growth (including bonuses) easing to 3.9%, but that is hardly enough to make the inflation problem disappear. This snapshot points to a 3.9% rise in the state pension next April under the triple lock, with average earnings growth, the measure used for the calculation, being pushed higher by particularly strong public sector pay growth. Public sector pay is running at 6.3%, more than twice the 2.9% pace in the private sector, which reflects the impact of pay awards and the timing of them.</p>

<p>That&rsquo;s likely to reignite the debate around the triple lock, particularly when government debt is already so high, and the cost of servicing it is painfully expensive. It may be even more controversial given that a pay measure which has been boosted by public sector wage awards is helping drive up the state pension bill at the same time as the government is already under pressure to contain spending and borrowing.</p>

<p>With inflation already stubbornly above target and energy prices surging again, the UK is facing an increasingly uncomfortable combination of a jobs market losing momentum at the same time as another inflationary shock is potentially building, and pressure on public spending is mounting.</p>

<p>So the spectre of stagflation is still looming over the UK economy. Although the latest growth figures surprised on the upside, there will be concern that GDP is not robust enough to sustain a drop in confidence among households and consumers if the energy crunch continues. Fewer vacancies, falling payroll numbers and cautious employers point to an economy losing some of its hiring power, just as higher energy costs descend. Policymakers at the Bank of England will be mindful that the economy is struggling to gain momentum, yet some are increasingly concerned about the rising inflationary risks. While a pause still looks likely on Thursday, four interest rate hikes are now being priced in, and those expectations will show up in higher borrowing costs in the mortgage market, so households are already bracing for high bills ahead.&rdquo;</p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/red-sea-risks-fuels-inflation-as-jobs-market-loses-momentum-27177.htm</link>
<pubDate>Tue, 15 Sep 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Comments As Pensions On Track For 3 9  State Pension Hike</title>
		<description><![CDATA[<p>The ONS has published the latest labour market data: <a href="https://www.gov.uk/government/statistics/uk-labour-market-september-2026">UK Labour Market: September 2026 - GOV.UK</a></p>

<p><strong>Helen Morrissey, head of retirement analysis, Hargreaves Lansdown: </strong>&ldquo;Pensioners stand to be almost &pound;490 better off next year as today&rsquo;s earnings figures have a huge impact on next year&rsquo;s state pension. The data, alongside September&rsquo;s inflation figure and 2.5%, is a key component of the triple lock formula used to increase state pensions. With CPI inflation currently sitting at 2.9% it seems increasingly likely that today&rsquo;s 3.9% increase in average earnings will be the figure used. This would put someone on the full new state pension on course to receive &pound;250.70 per week from next April &ndash; up from the current &pound;241.30 per week. Someone on a full basic state pension would receive &pound;192.10 per week &ndash; up from &pound;184.90. This will be a welcome boost to pensioner incomes but remember that the state pension is the foundation of your income and will only cover the essentials.  HL&rsquo;s Savings and Resilience Barometer shows only 43% of households are on track for an adequate retirement &ndash; the state pension will get you some of the way, but not all of it. If you want more from your retirement, you need to take your pension planning into your own hands. Taking advantage of tools such as online calculators lets you see how much you are on track to have and how much income that is likely to give you when you retire. If you have a gap between what you have and what you need then taking small actions, such as boosting contributions every time you get a pay increase or promotion could have a big impact over time. If your employer is willing to increase their contribution if you increase yours &ndash; known as the employer match &ndash; then this can also make a big difference. This steady drip feed of contributions invested over the long term can transform your retirement.&rdquo;</p>

<div><strong>David Brooks, Head of Policy at Broadstone, commented: </strong>&ldquo;The earnings growth data looks set to provide another big boost to the State Pension from next year, delivering a welcome financial uplift to retirees as we head towards a challenging winter. The full new State Pension now exceeds the Personal Allowance, a landmark that will inevitably draw further attention to the impact of frozen tax thresholds and the substantial increases we have seen in the State Pension over recent years. The increase will sharpen the question of whether the triple lock remains affordable over the long term given the UK&rsquo;s precarious public finances. It is important not to throw the baby out with the bathwater as protecting pensioner living standards remains vital, but the system also has to be fair and financially sustainable across generations. Transitioning to a double lock that protects increases in line with working-age benefits would seem the most likely compromise given it is today&rsquo;s workers who ultimately fund the State Pension.&rdquo;</div>

<div> </div>

<div> </div>

<p> </p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/comments-as-pensions-on-track-for-3-9--state-pension-hike-27178.htm</link>
<pubDate>Tue, 15 Sep 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Pension Savers Need More Support At Retirement</title>
		<description><![CDATA[<div><u><strong>By Dale Critchley, Workplace Policy Manager, Aviva</strong></u></div>

<div> </div>

<div>Trustees and pension providers have a duty to provide clear, relevant information, in the right format and at the right time to help members make good decisions. The retirement &ldquo;wake up pack&rdquo; is packed with information about the different options available to those looking to take an income. This is often augmented by online information and modelling tools, all designed to help members decide on the best option to meet their retirement income needs.   </div>

<div> </div>

<div>For some people, information is enough. But where understanding is low or decisions involve significant sums of money, members may need additional support.  </div>

<div> </div>

<div>Regulated advice provides a bespoke retirement plan, created to meet the precise needs of an individual or household. It&rsquo;s the gold standard but comes at a cost which may not be justifiable for smaller pension pots.  Information about the availability of advice, and when it might be appropriate, could help members make better decisions. At Aviva we offer a free service to help customers decide if they should take advice in the run up to retirement. Seeing information about the entirety of our pension income via the Pension Dashboard may prompt more people to recognise the value of advice too.    </div>

<div> </div>

<div>Targeted Support and high-level proposals for Guided Retirement within the recent Pension Schemes Act both lean into the idea that members might benefit from guidance around what might be appropriate, based on groups of people who share common characteristics. In both cases, a solution is presented based on the data required to place a member within a cohort for whom a particular solution has been identified as appropriate. Within Targeted Support this is a recommendation, within Guided Retirement it will be presented as a &ldquo;default solution&rdquo;.  </div>

<div> </div>

<div>The effectiveness of guidance will depend on whether members participate in the process and their willingness to accurately answer what might be a handful of questions. This may well depend on an appreciation of the value they might get from the process.  It will also depend on schemes and providers being able to make recommendations, or provide appropriate defaults, based on a limited amount of data. This will not be the same as the fact find to capture data for advice.   </div>

<div> </div>

<div>Given that longevity risk sharing solutions will disadvantage people with a reduced life expectancy (without effective underwriting) I think there should at least be a simple filtering question about health. Capacity to deal with fluctuating income can be inferred from details of other sources of income, while aspects like housing tenure can point toward income needs. We might also need to ask about preferences, recognising that members have saved hard to accumulate their pension pot, and that, for example, they may prefer to forego a level income in real terms, in exchange for a higher income in more active retirement.  </div>

<div> </div>

<div>While millions have been successfully enrolled into workplace pensions without needing to make active choices, there is growing recognition that members need more than clear information if they are to make better retirement decisions and achieve better outcomes.</div>

<div>            </div>

<div>   </div>

<div>                                                   </div>

<div> </div>

<p> </p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/pension-savers-need-more-support-at-retirement-27183.htm</link>
<pubDate>Tue, 15 Sep 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Digital Pensions Revolution Must Not Leave Savers Behind</title>
		<description><![CDATA[<div>As online member portals, mobile apps, Pensions Dashboards and artificial intelligence (AI) become central to pension provision, the paper argues that inclusion must become a fundamental design principle rather than an afterthought.</div>

<div> </div>

<div>While digital technology has the potential to improve engagement, simplify administration and help members make better-informed retirement decisions, the paper warns that increasing reliance on digital services could widen existing inequalities for people who lack digital access, skills, confidence or trust.</div>

<div> </div>

<div>In pensions, where decisions can affect financial security for decades, digital exclusion can lead to lower engagement, poorer outcomes and greater vulnerability to scams and fraud.</div>

<div> </div>

<div>The paper sets out practical recommendations for trustees, providers, regulators and policymakers, including embedding inclusive design into digital services from the outset, maintaining high-quality alternative channels for those who need them, simplifying communications, improving accessibility, adopting proportionate identity verification processes and ensuring AI is developed and deployed responsibly.</div>

<div> </div>

<div>The paper highlights that digital exclusion is about far more than internet access. Disability, affordability, digital confidence, usability, language and major life events can all affect a person's ability to engage with their pension at the time they need support most.</div>

<div> </div>

<div>Rather than treating digital inclusion as a compliance exercise, the SPP argues it should become a strategic priority across the pensions system, helping to deliver better retirement outcomes while supporting innovation, trust and long-term value for members.</div>

<div> </div>

<div><strong>Mamunul Wahid, Chair of the SPP Digital Inclusion Working Group, said: </strong>&quot;Digital technology has enormous potential to transform how people engage with their pensions, but innovation must go hand in hand with inclusion.</div>

<div> </div>

<div>If we design digital services around the needs of the widest possible range of scheme members, we can improve engagement, build trust and help deliver better retirement outcomes for everyone. The challenge is not simply to make pensions more digital, but to make them more accessible.&rdquo;</div>

<div> </div>

<div><a href="https://www.actuarialpost.co.uk/downloads/cat_1/SPP-Pensions-in-a-Digital-World-Embedding-Inclusion-15.9.26.pdf">Pensions in a Digital World: Embedding Inclusion is available in full, for free, here</a></div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/digital-pensions-revolution-must-not-leave-savers-behind-27179.htm</link>
<pubDate>Tue, 15 Sep 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Building Sovereign Disaster Resilience</title>
		<description><![CDATA[<div><iframe allow="accelerometer; autoplay; clipboard-write; encrypted-media; gyroscope; picture-in-picture; web-share" allowfullscreen="" frameborder="0" height="315" referrerpolicy="strict-origin-when-cross-origin" src="https://www.youtube.com/embed/zxIcBs_trTU?si=MtahxrA0_dyoxkOV" title="YouTube video player" width="340"></iframe></div>

<p> </p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/building-sovereign-disaster-resilience-27184.htm</link>
<pubDate>Tue, 15 Sep 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Warning Against One Size Fits All Value For Money Framework</title>
		<description><![CDATA[<div>In its <a href="https://www.actuarialpost.co.uk/downloads/cat_1/PMI-consultation-response-vfm-framework-2026.pdf">response</a> to the Value for Money Framework consultation on draft regulations and draft FCA rules, the PMI supports the overall direction of the reforms, including the move away from assessing pensions primarily on cost and towards a broader evaluation of investment performance, service quality and member outcomes.  </div>

<div> </div>

<div>However, the PMI is concerned that revised proposals would bring hybrid schemes into scope, despite the framework having been developed principally around standalone defined contribution arrangements. The PMI believes this risks creating misleading comparisons, additional complexity and significant compliance costs, while offering limited practical benefit to members.  </div>

<div> </div>

<div>And it warns that schemes could be required to spend increasing amounts of time, money and governance resource complying with reporting requirements that do not improve retirement outcomes, potentially diverting attention from activities that genuinely add value for members.  </div>

<div> </div>

<div>The PMI is therefore calling for hybrid schemes to remain outside the initial scope of the framework, or for a temporary exemption until a more proportionate and tailored approach can be developed.  </div>

<div> </div>

<div><strong>Helen Forrest Hall, Chief Strategy Officer at the PMI, said: </strong>&quot;Everyone wants pension schemes to deliver value for money. The test is whether regulation helps savers achieve better outcomes or simply creates more process. Hybrid schemes are different by design. Applying a framework built for standalone DC schemes risks adding cost and complexity without adding value. </div>

<div> </div>

<div>&quot;We should be careful not to confuse measuring value with delivering value. The focus must remain on better outcomes for savers, not more administration for schemes. The Government has made important improvements to these proposals, but keeping hybrid schemes exempt for now would be the right and proportionate approach.&quot;  </div>

<div> </div>

<div>Alongside its concerns on scope, the PMI has welcomed a number of improvements to the proposals, including a stronger focus on overall value rather than charges alone, a phased implementation period, broader comparator groups and measures intended to encourage continuous improvement rather than conformity.  </div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/warning-against-one-size-fits-all-value-for-money-framework-27180.htm</link>
<pubDate>Tue, 15 Sep 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Triple Lock Debate Intensifies</title>
		<description><![CDATA[<p>Millions of UK pensioners are on course for a potentially inflation-beating increase in their State Pension next April, however the rise will also push the full new State Pension above the frozen income tax Personal Allowance &ndash; putting the interaction between the Triple Lock and the tax system firmly in focus ahead of the Autumn Budget.</p>

<p>The Triple Lock, introduced in 2011 by the Conservative-Liberal Democrat Coalition government, guarantees that the State Pension rises each April by the highest of average earnings growth, September CPI inflation or 2.5%. It replaced a system under which the basic State Pension had for decades been largely linked to inflation, meaning that while pensioners were protected against rising prices, the value of the State Pension had gradually fallen behind average earnings. </p>

<p>The key May-July earnings figures published by the Office for National Statistics today shows earnings rising 3.9%. Unless September inflation subsequently comes in higher, earnings are therefore likely to determine the April 2027 increase in the State Pension.</p>

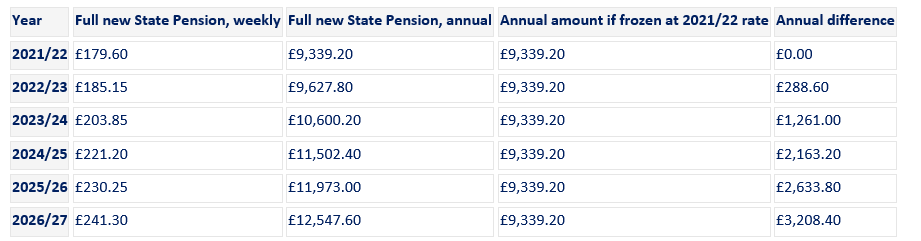
<p>Earnings growth at 3.9%, means the full new State Pension would rise from &pound;241.30 to around &pound;250.70 a week - taking annual income to approximately &pound;13,036. Someone receiving the full basic State Pension under the pre-2016 system could see their weekly payment rise from &pound;184.90 to around &pound;192.10. </p>

<div><strong>Triple Lock meets the frozen tax threshold</strong></div>

<div>While a 3.9% rise may look generous, the frozen tax threshold means some of that increase is effectively clawed back through the frozen income tax threshold - a classic example of fiscal drag or stealth tax. For someone receiving the full new State Pension with no other taxable income, around &pound;466 would sit above the Personal Allowance, potentially resulting in roughly &pound;93 of income tax at the 20% basic rate. That would reduce the &pound;488 annual increase to around &pound;395 after tax &ndash; an effective net increase of approximately 3.1%. </div>

<p>This particular calculation applies to those receiving the full State Pension, but it illustrates the wider tension: as the State Pension rises while tax thresholds remain frozen, more pensioners are pulled into the tax net and the Exchequer effectively takes back part of the increase it has just awarded. </p>

<p>The State Pension is taxable income, although it is normally paid without tax being deducted at source. Pensioners with additional income from workplace or private pensions may therefore find more of their retirement income caught by income tax as the State Pension rises while tax thresholds remain frozen.</p>

<p><strong>Maike Currie, VP Personal Finance, PensionBee, comments:</strong> &ldquo;An inflation-beating State Pension rise will be welcome news for millions of pensioners, particularly those struggling with the cost of everyday essentials. But there is an increasingly obvious contradiction at the heart of the system: the Triple Lock is pushing the State Pension up while frozen tax thresholds are pulling more pensioners into the tax net.</p>

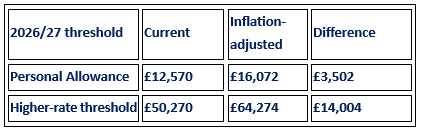
<p>&ldquo;A rise of 3.9% next April would take the state pension above &pound;13,000 and notably above the tax-free &pound;12,570 Personal Allowance.So we increasingly have one arm of the government raising pensioners&rsquo; incomes while another claws some of that increase back through tax.&rdquo;</p>

<div><strong>Triple Lock debate intensifies</strong></div>

<div>The figures arrive as the future of the Triple Lock moves increasingly into the political spotlight. The Institute for Fiscal Studies estimates that &pound;154 billion will be spent on the State Pension in 2026/27, making it by far the UK&rsquo;s largest benefit. It estimates annual spending is now around &pound;16 billion higher than it would have been if the State Pension had risen in line with average earnings since 2010.</div>

<p>The Triple Lock was introduced after decades in which the State Pension had fallen behind average earnings. Its role in rebuilding its value means PensionBee believes the debate should move beyond a binary choice between keeping the current system forever or simply scrapping it.</p>

<p><strong>Currie comments:</strong> &ldquo;The Triple Lock has done an important job. For three decades before its introduction, the State Pension was largely linked to price rises. While that protected its purchasing power, it meant pensioners progressively fell behind the earnings of working households. The Triple Lock helped reverse that decline and rebuild the value of the State Pension.</p>

<p>&ldquo;But it was designed as a catch-up mechanism, not necessarily a forever policy. Because it always chooses the highest of inflation, earnings growth or 2.5%, over time this formula can ratchet the State Pension up faster than any one of those measures taken alone. Recent periods of volatility have highlighted the ratchet effect of the Triple Lock. The State Pension rose by 10.1% in April 2023, reflecting the previous September&rsquo;s inflation rate, and by another 8.5% in April 2024, in line with earnings growth. Because each increase becomes part of the pension&rsquo;s new baseline, these unusually large rises are effectively locked in and compound future spending.&rdquo; </p>

<p>The OBR estimates that, because inflation and earnings have proved much more volatile than initially anticipated, the Triple Lock has cost around three times more than originally expected. </p>

<p>&ldquo;After 15 years of the Triple Lock, calls for its reform are growing as the cost continues to rise and questions of generational fairness become harder to ignore. The UK has around one million young people not in employment, education or training, persistent child poverty and a generation of workers facing high housing costs and a heavy tax burden, while also being asked to fund an increasingly expensive retirement system,&rdquo; says Currie. </p>

<p><strong>She adds:</strong> &ldquo;However, pitching pensioners against young people is the wrong answer. We all rely on younger generations to work, build businesses and pay the taxes that ultimately support the State Pension. The challenge is to protect pensioners from poverty today without steadily passing an unsustainable bill to the working generation.&rdquo;</p>

<div>Triple Lock reform must be part of a bigger retirement settlement</div>

<div>Any reform of the Triple Lock would need to give people sufficient time to adjust their retirement plans. Changes to the State Pension age are typically announced years in advance, and PensionBee believes the same principle should apply to any fundamental change in how the State Pension is uprated.</div>

<p>&ldquo;People make retirement decisions decades ahead, so you can&rsquo;t move the goalposts overnight. Any reform of the Triple Lock needs to be clearly signalled years in advance so people understand what is changing and have time to plan,&rdquo; .</p>

<p>But the debate over the Triple Lock should not happen in isolation. PensionBee believes policymakers need to take a more holistic view of retirement provision, considering the level of the State Pension alongside the State Pension age and the adequacy of private pension saving.</p>

<p>Auto-enrolment has successfully brought millions more people into workplace pension saving, but there are growing concerns that minimum contribution levels will not provide many workers with enough to maintain their standard of living in retirement. Millions more remain inadequately served by the system, including many self-employed and gig workers, and lower earners.</p>

<p>&ldquo;The Triple Lock protects the baseline income of today&rsquo;s retirees, but we also have serious structural gaps in private pension saving. Millions of tomorrow&rsquo;s retirees risk reaching later life with nowhere near enough to maintain their standard of living,&rdquo; </p>

<p>That makes the question of intergenerational fairness much broader than whether today's pensioners should receive a particular increase in their State Pension.</p>

<p>&ldquo;This cannot descend into a young-versus-old argument. We need a State Pension settlement that today&rsquo;s pensioners can rely on, while making sure today&rsquo;s 20-, 30- and 40-year-olds are building enough private pension wealth and can reasonably expect the State Pension to still be there when they retire.</p>

<p>&ldquo;The Triple Lock has helped repair the State Pension. The next challenge is much bigger: designing a retirement system - State Pension, State Pension age and private pension saving together - that is both adequate and sustainable for the next generation.&rdquo; </p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/triple-lock-debate-intensifies-27181.htm</link>
<pubDate>Tue, 15 Sep 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Comments On Dwp Small Pot Consolidation Proposals</title>
		<description><![CDATA[<div><em>Across the workplace pensions market today, there are an estimated 13 million deferred small pension pots (less than &pound;1,000) &ndash; a number which is growing by more than a million every year and is costing the industry an estimated &pound;240 million annually in administration costs that are ultimately paid by members. </em><em>The proposals &ndash; which follow the passing of the Pension Schemes Act 2026 &ndash; lay the groundwork to implement the Multiple Default Consolidator solution by consulting on factors such as the eligibility criteria for schemes and pots within scope, the authorisations required for consolidators and new duties on employers to provide relevant information to schemes in respect of their enrolled employees.</em></div>

<div> </div>

<div><strong>David Pye, Head of Client Development at Broadstone, commented: </strong>&ldquo;The small pots problem has been building for years and the scale of the challenge is becoming increasingly difficult to ignore. With more than 13 million deferred pots with a total value of over &pound;4 billion already in the system and another million being created every year, automatic consolidation has the potential to make pensions simpler for savers while stripping out a significant amount of unnecessary administration and cost. The government is right to put member outcomes at the centre of the framework. Consolidation should not simply be about moving assets into bigger schemes, but ensuring savers are transferred into well-governed arrangements that offer good value for money and lay the groundwork for achieving improve retirement outcomes. &ldquo;This consultation makes clear that there are important practical questions still to resolve, particularly around authorisations, data matching, member communications and the treatment of pots carrying valuable guarantees or protections. The industry will also need sufficient certainty and time to build the infrastructure required to make millions of transfers accurately and securely. 2030 may sound some way off, but creating a system capable of consolidating potentially tens of millions of pots will be a major operational undertaking. This consultation is therefore an important step in turning a long-discussed policy ambition into something that can work effectively in practice.&rdquo;</div>

<div> </div>

<div>
<div><strong>Maurice Titley, Commercial Director - Data & Dashboards at Lumera said:</strong> &ldquo;The scale of the small pots challenge makes consolidation one of the most significant operational exercises facing the pensions industry. With more than 13 million deferred pots worth less than &pound;1,000, and around one million more being created each year, there is a clear need for a solution that can deliver consolidation efficiently while reducing the costs currently borne by savers. The Government's proposed federated delivery model has the potential to provide just that. By allowing schemes to continue exchanging data, carrying out matching activity and undertaking transfers through scheme-led processes, within a common framework of rules, standards and governance, it should provide an efficient and scalable model, balancing operational practicality with strong governance, and alignment with the DWP&rsquo;s roadmap. When Lumera co-authored the 2025 Pensions UK Small Pots Digital Systems Feasibility Review with KGC, one of our key conclusions was that a federated model could be delivered, provided the industry established common approaches to areas including data standards, messaging standards and data matching. This consultation provides an opportunity to develop those detailed approaches further, including defining the role and responsibilities of the proposed central oversight body. The Government has reiterated its ambition 'to have small pot consolidation operational from 2030' and this consultation already gives enough direction for industry to start preparing to deliver this. Schemes and consolidators will need the data, systems and processes in place to support a federated delivery model at scale, including the high volumes of automated matching and transfers that will be required. The consultation provides an opportunity to test and refine the standards, governance and operational processes that will ultimately be needed to make consolidation work effectively for millions of savers.&rdquo;</div>

<div> </div>
</div>

<div><a href="https://www.gov.uk/government/consultations/small-pots-a-pathway-for-consolidation/small-pots-a-pathway-for-consolidation">Link to the consultation</a></div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/comments-on-dwp-small-pot-consolidation-proposals-27182.htm</link>
<pubDate>Tue, 15 Sep 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Ai Models Give Inaccurate Financial Advice 57  Of The Time</title>
		<description><![CDATA[<div>Millions of Britons risk facing financial losses because the AI models they rely on for financial advice are giving them the wrong answers most of the time, according to new research.</div>

<div> </div>

<div>The new report, Artificial Authority: Should you trust AI to deliver financial advice? from financial technology firm Saturn, shows that the most popular AI models from the likes of ChatGPT, Claude, CoPilot, Grok and Gemini give wrong answers to financial inquiries on average 57% of the time, only giving accurate answers 43% of the time. On harder questions, the AI models made mistakes, on average, in 88% of cases. Some AI models gave wrong answers to 99% of those more complex questions.</div>

<div> </div>

<div>In the most comprehensive analysis so far of AI financial advice, Saturn rigorously tested 18 popular AI models against 121 different financial questions. Each question was repeated 5 times to check consistency. In total, over 10,000 questions were put through the AI models. It found their answers contained errors in calculations, missed vital risk warnings, ignored upcoming tax changes or hallucinated rules that did not exist. In the worst cases, the cost of following the incorrect advice could run to tens of thousands of pounds.</div>

<div> </div>

<div>Free to use models give more inaccurate advice than paid-for models. Free AI models made mistakes in 63% of answers, whereas the paid-for models made mistakes in 49% of answers. On the hardest questions, the free models made mistakes in 93% of answers.</div>

<div> </div>

<div>The research comes after the Financial Conduct Authority published The Mills Review and found 26% of consumers trust general-purpose AI tools like ChatGPT and Claude for financial advice. It warned of the potential dangers for consumers who are left without any protections when taking financial advice from AI.</div>

<div>The FCA is also considering whether to regulate the financial advice that AI models provide.</div>

<div> </div>

<div><strong>Saturn chief executive Amal Jolly said:</strong> &ldquo;The low quality of financial advice from mainstream AI models risks leading to widespread consumer harm. Millions of people are trusting the AI models for money advice, but they are getting wrong answers that can lose them money.&rdquo;</div>

<div> </div>

<div><strong>How the AI models performed and costly errors</strong></div>

<div>The findings from the research in Artificial Authority: Should you trust AI to deliver financial advice? includes:</div>

<div> </div>

<div><em>The worst-performing model, Claude Haiku 4.5, made mistakes in 82% of answers.</em></div>

<div><em>Second-worst was Google&rsquo;s Gemini 3.1 Pro, failing 73% of tests.</em></div>

<div><em>xAI&rsquo;s Grok 4.5 made mistakes 59% of the time.</em></div>

<div><em>ChatGPT 5.6 Luna made mistakes 58% of the time.</em></div>

<div><em>When asked more complex financial questions, Google&rsquo;s Gemini 3.5 Flash and Claude Haiku 4.5 and gave wrong answers 99% of the time.</em></div>

<div><em>The best performing model overall was Claude Opus 5 (reasoning), which made mistakes in 39% of answers</em></div>

<div> </div>

<div>AI models were scored against specific criteria for each question that they had to get right in order to pass. Where answers contained factual errors, missed key points or left out important warnings they were marked as a fail.</div>

<div> </div>

<div>Among the most serious and costly errors in the experiments, a mistake on pension tax rules by Claude Haiku 4.5, one of its free models, could have resulted in a pension saver facing a &pound;17,500 charge from HMRC.</div>

<div> </div>

<div>Vulnerable consumers in debt could also be at serious risk from poor AI advice. By recommending that it is best to pay off highest-interest debts first, rather than priority bills like rent and council tax, the AI models could have put someone in debt at risk of eviction, bailiff visits or legal action.</div>

<div> </div>

<div>When asked about student loans, Claude invented a rule and said a graduate could stop repayments if they were moving abroad. This could have resulted in that person being put onto higher monthly repayments.</div>

<div> </div>

<div>Meanwhile, flawed mortgage advice presented further potential harm for borrowers. A Gemini model wrongly reassured a borrower that taking a mortgage payment holiday would not damage their credit score when in reality it could, making it harder to secure the most competitive rates in future.</div>

<div> </div>

<div>The study uncovered failures across a broad spectrum of issues, affecting consumers in different age groups and income brackets, including debt, student loans, mortgages, pensions, tax and savings.</div>

<div> </div>

<div>Separate FCA research suggests that consumers are almost three times as likely to trust tools such as ChatGPT, Claude and Gemini for financial advice, than they are to receive advice from a qualified financial adviser.[1] Young investors are now more likely to trust AI than financial influencers or TV shows, the FCA found.[2]</div>

<div> </div>

<div><strong>Saturn CEO Amal Jolly continued:</strong> &ldquo;AI tools are fast becoming the first port-of-call for many consumers with financial questions. But our research reveals evidence that it is far too early to put so much trust in AI chatbots. We found some of the most widely used models gave the wrong answer to financial questions the majority of the time. In the worst examples, relying on AI&rsquo;s answers to tax questions could cost families tens or hundreds of thousands of pounds.&rdquo;</div>

<div> </div>

<div><strong>He added: </strong>&ldquo;AI financial advice is currently unregulated, leaving consumers with none of the protections, including compensation, that they would get if they went to a human adviser. The FCA has started to think about this, but it needs to act fast to protect people. The FCA should regulate AI to ensure consumers are protected.&rdquo;</div>

<div> </div>

<div><span style="font-size:11px"><em>[1]  26% of adults trust Al for advice, while 9% of adults receive financial advice (FCA, Mills Review, p.5)</em></span></div>

<div><span style="font-size:11px"><em>[2] An FCA survey of 18-40 years olds who own or are considering investments found that 56% trust AI tools, more than TV and radio (47%), press (46%) or social media influencers (29%).</em></span></div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/ai-models-give-inaccurate-financial-advice-57--of-the-time-27175.htm</link>
<pubDate>Mon, 14 Sep 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>How To Manage Cyber Risk As A Strategic Imperative</title>
		<description><![CDATA[<p><strong>By Adrian Ruiz, Head of FINEX GB Cyber & TMT at WTW</strong></p>

<p>These kinds of questions were at the heart of the agenda at a recent Willis cyber risk event, which brought together cyber risk and insurance specialists, legal professionals and cybersecurity experts to explore cyber risk management as a strategic imperative.</p>

<p>In this, the first of a series of articles based on insight from the event, we look at what recent incidents, the influence of AI and claims experience tell your business about better resilience and stronger recovery.</p>

<div><strong>Why does cyber risk now demand board-level business leadership?</strong></div>

<div>Cyber incidents can quickly create operational disruption and financial loss, putting the issue alongside more traditional board-level concerns like liquidity and regulatory scrutiny.</div>

<p>Should your systems go down, your organisation will want to know it can keep your customers informed, restore critical activity, manage suppliers, protect cash flow and make fast decisions with incomplete information. That means finance, legal, operations, risk management and executive leadership all need to understand what a cyber event would mean for the business to better prioritize investments in cyber resilience and how it will recover should an incident hit.</p>

<p>Our recent Cyber in Focus report showed ransomware incidents are disrupting organisations for an average of 25 days, with business interruption often driving a significant share of losses. The 2025 Jaguar Land Rover cyber attack, for example, lasted weeks, reaching UK factories, overseas operations, suppliers, business partners and local communities.</p>

<p>Without the right preparation supported at the highest levels, your teams may struggle to sustain manual workarounds and may uncover dependencies and insurance gaps they haven&rsquo;t fully mapped.</p>

<div><strong>How is AI changing your organisation&rsquo;s cyber risk profile?</strong></div>

<div>AI may not be creating a separate cyber risk category today, but it is making familiar attack routes faster, more convincing and harder for your teams to contain.</div>

<p>Willis cyber specialists have seen attackers use AI to enhance impersonation, social engineering, credential misuse and deepfakes, making attacks easier to launch and harder to spot. One reported agentic AI-powered attack showed malicious actors using AI to identify vulnerabilities and exploit them with very little human input.</p>

<div><strong>How should your cyber risk strategy address AI-enabled threats?</strong></div>

<div>Your cyber strategy should strengthen the fundamentals instead of rebuilding strategy around each new threat label. Strong authentication, identity security, approval controls, employee awareness and clear escalation routes can help your teams reduce risks around the people and processes attackers are targeting every day.</div>

<p>Every organisation needs disciplined cyber risk governance, tested response plans and clear recovery priorities. It also needs robust vendor management and supplier backups with a detailed understanding of which providers support critical activities, what your teams would do if those providers became unavailable and how long your business could keep operating without them.</p>

<div><strong>How can cyber insurance improve resilience?</strong></div>

<div>Willis&rsquo; Cyber in Focus report showed cyber insurance is responding to claims, with more than 95% of the average data breach loss and 90% of the average first-party loss covered.</div>

<p>Cyber insurance also has a role in helping your organisation quantify cyber risk and connecting your specific exposures to the operational disruptions and financial losses your board needs to plan for above all others.</p>

<p>Your organisation can get the most value from cover by using cyber risk quantification to set the appropriate limits and structure your policy around your specific operating exposures. Calling on insurers and brokers to align wordings, decide on approved vendors and refine incident response processes before an event hits will also help the business maximise insurance value alongside its resilience and recovery capabilities.</p>

<p>Discover more practical perspectives on maximising value from cyber insurance. Access <a href="https://willistowerswatson.turtl.co/story/cyber-claims-in-focus-june-2026/page/1">Willis&rsquo; Cyber in Focus 2026 report.</a></p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/how-to-manage-cyber-risk-as-a-strategic-imperative-27176.htm</link>
<pubDate>Mon, 14 Sep 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Only Two In Five Know Where All Their Pensions Are Held</title>
		<description><![CDATA[<div>Ahead of Pension Awareness Day, new research from Mylo at Aegon has revealed that only two-in-five (40%) UK adults know where all their private and workplace pensions are held.</div>

<div> </div>

<div>The findings highlight the challenge many people face in keeping track of retirement savings accumulated across multiple employers, an issue Mylo is designed to help address by helping people locate and bring together eligible pension pots.</div>

<div> </div>

<div>More than a third (36%) of UK adults don't know where all their pensions are held, with 20% only knowing where some are and one-in-six (16%) admitting they don't know where any of their pensions are held. A further 24% say they don't have a pension.</div>

<div> </div>

<div>The findings suggest that for many people, understanding whether they're on track for retirement starts with a more fundamental challenge: keeping track of pension savings accumulated across different jobs and over many years.</div>

<div> </div>

<div>Despite many people engaging with pension communications, understanding also remains a challenge. More than seven-in-ten (72%) pension savers say they open their annual pension statement and 69% read it, yet only 55% say it helps them understand whether they are saving enough for retirement.</div>

<div> </div>

<div>The research also found that almost a third (30%) of pension savers never check where their pension is invested, while only 21% do so at least monthly.</div>

<div> </div>

<div><strong>Nick Roy, Commercial Director of Workplace at Aegon, said: </strong>&quot;You can't plan effectively for retirement if you've lost track of your pension savings. Yet only two-in-five adults know where all their pensions are held. For many people, the challenge isn't a lack of interest in planning for the future, it's keeping on top of pension pots accumulated across different jobs and different stages of their working life.</div>

<div> </div>

<div>&quot;As people move between employers and build up multiple pension pots, it's easy to lose track of what you've already saved. Before people can decide whether they're saving enough for retirement, they first need to understand what retirement savings they have and where they are held.</div>

<div> </div>

<div>&quot;That's where Mylo can help. By helping people track down old pension pots and bring eligible pensions together, Mylo is designed to help people take greater control of their retirement savings and build a clearer picture of what they have. It can also help people understand where their money is invested and make more informed decisions about their future.</div>

<div> </div>

<div>&quot;As we continue the rollout of Mylo, our ambition is simple: to help people move from wondering where their pensions are and whether they're doing enough, to feeling more in control of their retirement savings and more confident about taking the next step.&quot;</div>

<p> </p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/only-two-in-five-know-where-all-their-pensions-are-held-27173.htm</link>
<pubDate>Mon, 14 Sep 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Ai Data Rules Must Reflect The Realities Of Pension Schemes</title>
		<description><![CDATA[<p>Last month the Government launched its call for evidence seeking practical examples of how data regulation interacts with AI and other data-intensive technologies, including where existing legal, technical and governance arrangements create uncertainty or friction.</p>

<p><strong>Victoria Roberts, Senior Client Manager and Cyber and Data Lead at ZEDRA, commented:</strong> &ldquo;The pensions industry has an important perspective to contribute to the Government&rsquo;s call for evidence, given the abundance as well as sensitivity of member data and the number of organisations typically involved in its collection, processing and use. With AI changing how data is collected, processed and used, it is important that the regulatory framework keeps pace to ensure it remains fit for purpose. For pension schemes, this is particularly relevant. Large volumes of member data can move across a complex network of trustees, administrators, advisers, technology providers and other third parties, while trustees remain accountable for ensuring that members&rsquo; interests are protected. For example, where the risk settlement industry is so active within DB pensions, large amounts of detailed personal data are being transferred and accessed.&rdquo;</p>

<p><strong>Roberts added: </strong>&ldquo;Any future approach to data regulation needs to recognise this reality and provide clarity around accountability, governance and the appropriate use of data across these relationships. Trustees need to be able to understand not just what data and where data is held, but how it is being used, including where AI-enabled technologies form part of the process.</p>

<p>&ldquo;As the Government considers the evidence, the pensions industry must ensure its experience is part of the conversation and shares insights from its collective experience. Getting the balance right will be important in enabling schemes to benefit from AI, such as more efficient processes and automation, while maintaining the trust and protections members expect.&rdquo;</p>

<p><strong>Roberts concluded: </strong>&ldquo;AI has the potential to vastly improve how pension schemes operate and how members are supported, but innovation needs to be underpinned by effective governance and guard rails that adequately protect members interests. The current call for evidence is a great opportunity for the pensions industry to ensure the regulatory framework supports responsible use of AI without creating unnecessary uncertainty for schemes.&rdquo;</p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/ai-data-rules-must-reflect-the-realities-of-pension-schemes-27174.htm</link>
<pubDate>Mon, 14 Sep 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Economy Shows Resilience  Stagflation Fears In The Spotlight</title>
		<description><![CDATA[<p><strong>Susannah Streeter, Chief Investment Strategist, Wealth Club: </strong>&ldquo;The spectre of stagflation is still hovering over the UK economy, but the latest growth snapshot has provided a welcome glimmer of resilience, with the economy expanding rather than going into reverse. The Footsie is set to claw back some ground, with a touch of optimism rearing up, after a fresh energy shock set off a wave of selling. It&rsquo;s a welcome report card for the government as Andy Burnham and his new team settle in, but there is no room for complacency, given the volatile forces swirling through markets, keeping borrowing costs painfully elevated and casting a dark shadow over the administration&rsquo;s spending plans.</p>

<p>Today&rsquo;s data shows GDP grew by 0.4% in July, according to the ONS, comfortably beating expectations for a contraction and following growth of 0.3% in June. Over the three months to July, the economy expanded by 0.4%, marking the eighth consecutive three-month period of growth.</p>

<p>While it's far from a rip-roaring recovery, it does suggest the UK economy has more staying power than feared, particularly given the pressure households and businesses are facing from scorchingly high energy prices and elevated borrowing costs. </p>

<p>Services are once again doing the heavy lifting, growing by 0.6% over the three months to July, with professional, scientific and technical activity and information and communication among the strongest performers.</p>

<p>AI also appear to be providing a bounce, with computer programming, consultancy and related activities jumping 3.5% in July. Many businesses with the largest turnover in these areas were involved in activities related to artificial intelligence and cloud computing.</p>

<p>It&rsquo;s a sign that the AI spending boom is starting to feed through into the wider economy, as businesses invest in the computing power, software and expertise needed to put the technology to work.</p>

<p>But there are still plenty of warning lights flashing. Production and construction both contracted by 0.5% over the three months to July, while consumer-facing services fell 0.4% in July, suggesting households are still cautious.</p>

<p>So, while the spectre of outright stagnation looms more faintly over the economy, the danger is that with crude and gas prices racing higher again and borrowing costs escalating, they will squeeze households and businesses, just as growth appears to have built a bit more momentum.</p>

<p>The bond market has switched into panic mode, with investors demanding sharply higher returns to lend, with 10-year gilt yields reaching levels not seen since the summer of 2007. While oil prices have retreated a little from the painfully high levels yesterday, when Brent nudged 108 a barrel, they are still painfully elevated, keeping inflationary concerns front and centre.</p>

<p>Interest rate decision</p>

<p>For the Bank of England, today's stronger-than-expected GDP figure makes an interest rate increase this year a touch more likely. Nevertheless, given the volatile times decision-makers are meeting in, it&rsquo;s still likely they will once again press the pause button next week and await more data. The MPC held Bank Rate at 3.75% in July, with policymakers split 6-3, with three members voting for a hike.</p>

<p>The big worry is that higher energy costs will be passed on as higher prices by businesses and consumers, but it&rsquo;s likely that the committee will want to see more evidence of that before triggering rate hikes. Given the turmoil in energy and bond markets, however, there is an expectation that we could see three to even four rate hikes over the next year. However, if the economy slows and consumers turn more cautious, that reticence may do some of the inflation-busting work for the bank.&rdquo;</p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/economy-shows-resilience--stagflation-fears-in-the-spotlight-27169.htm</link>
<pubDate>Fri, 11 Sep 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Soft Markets  Ai And Next Steps For London Market Pricing</title>
		<description><![CDATA[<p><u><strong>By Charl Cronje, Partner, LCP</strong></u></p>

<p>As markets soften rapidly in 2026, the importance of technical pricing will increase.  Firms need to monitor closely how far they allow rates to fall relative to technical adequacy, and there comes a point where the technical rates need to &ldquo;bite&rdquo; and prompt conversations about limiting premium volumes on a particular class of business.</p>

<p>The best firms have detailed &ldquo;retreat plans&rdquo; for each class, and for the overall portfolio mix.  As one underwriter recently told me &ldquo;anyone can reduce volume in a soft market, but it&rsquo;s all about knowing where to reduce that volume.&rdquo; </p>

<p>It&rsquo;s especially important in a soft market to capture data on underwriting decisions versus technical prices.  This data needs to differentiate between instances where the underwriter accepts the technical price but cannot realistically achieve that rate in the market, versus cases where the underwriter has a different view on the technical price itself. </p>

<p>Over time, this dataset can reveal whether model weaknesses, inconsistent underwriting, market pressures or strategic choices are driving pricing outcomes. This is potentially even more valuable than the underlying policy and claims data for refining pricing models over time. Only a minority of firms are doing an effective job in this area, so it is a potential angle for generating competitive advantage in difficult market conditions.</p>

<div><strong>Pricing team structure and operation</strong></div>

<div>Leading firms have surprisingly different operating models for actuarial pricing.  Some pricing functions stand entirely apart from underwriting and provide independent challenge on rate adequacy.  Others have actuaries embedded with underwriting teams, providing day-to-day technical support.  This approach loses much of the power for independent challenge but firms argue that it helps underwriters make better pricing decisions over time.</div>

<p>Other firms have pricing actuaries working closely with underwriters but reporting into a central actuarial pricing function.  This can provide a better combination of independent challenge and business-as-usual assistance.  Importantly, it can be helpful for each pricing actuary to have visibility of multiple classes of business.  This enables them to spot differences in underwriting approaches and to highlight risks to the central pricing  function.</p>

<div><strong>Pricing versus portfolio management</strong></div>

<div>Firms now typically have a portfolio management team (PMT) separate from the pricing and underwriting functions.  PMTs tend to include a mix of individuals from underwriting, actuarial and data analytics backgrounds.</div>

<p>The remit of PMTs varies a lot from firm to firm.  A common approach is for PMTs to do a lot of work on &ldquo;thematic&rdquo; issues like inflation or silent cyber risk, as well as deep dives on problematic classes of business.  This is in addition to the core function of helping management decide how to allocate capital or premium volume &ldquo;budget&rdquo; between classes. </p>

<p>In other cases, PMTs play different roles, like &ldquo;translating&rdquo; between the actuarial pricing function and underwriters, developing new pricing models or helping with new product strategy.</p>

<p>A pitfall for firms to watch out for is creating the sense that the &ldquo;exciting&rdquo; pricing work is all going to the PMT, leaving only repetitive daily pricing work to the actuarial pricing team.  This can affect performance and retention &ndash; rather, the actuarial pricing team and PMT should work closely together to ensure that both benefit from the insights generated by the other.</p>

<div><strong>Capturing AI opportunities</strong></div>

<div>Underwriters are already using large language models (LLMs) for general research purposes.  However, there is growing pressure for insurers to deliver AI-related innovations or cost savings in all areas of work.</div>

<p>A key current focus for many firms is using LLMs to automate the ingestion of submission data into the underwriting system. The smallest firms are some way from achieving this, because of lower business volumes (meaning that there is less money to be saved) and lack of resources.  The largest firms are tending to pursue this on an &ldquo;enterprise&rdquo; scale, which ultimately may be very efficient but may take a couple of years to implement.  This may create an opportunity for well-resourced mid-tier firms: they can test focused use cases more quickly than firms pursuing enterprise-wide transformation, while still having sufficient scale for the savings to matter.</p>

<p>An obvious challenge to LLM-assisted data ingestion is &ldquo;won&rsquo;t the LLM get things wrong or hallucinate data?&rdquo;  These concerns are valid but, when firms have backtested these solutions against past data, it turns out that humans were making plenty of data ingestion mistakes in the past!</p>

<p>We are still a way off from deep integration of AI into underwriting decision-making itself. The potential gains are clear, but specialty underwriting involves such a high degree of judgement that there will be a high bar for models to add real value.</p>

<p>One way forward is a model that observes underwriter behaviour and identifies decisions that are inconsistent with past practice.  This could lead to better decisions over time.  Some firms already have simple solutions to help with this, such as automatically showing the underwriter 3-5 examples of similar risks that they have underwritten recently, before they make their decision on the risk at hand.</p>

<div><strong>Where next?</strong></div>

<div>We&rsquo;ve only scratched the surface in this article.  There are many other pressing issues for pricing teams to consider in the coming years, including:</div>

<div> </div>

<div><em>Balancing the benefits of pricing models that mimic underwriter expert judgement with the slightly different benefits of more data-heavy models that provide fully independent challenge.</em></div>

<div><em>Balancing the desire for pricing models to provide close to 100% coverage of the portfolio with the reality that models are much weaker and less predictive in some classes of business than in others.</em></div>

<div><em>Understanding why some underwriting teams engage much better with the pricing models than others.</em></div>

<div><em>Making it easier for underwriters to engage with the technical price, and doing this at the right point in the underwriting workflow.</em></div>

<p>London Market underwriting is a business that is massively driven by relationships and expert judgement.  This makes it a particularly exciting area to apply the actuarial skillset to help manage risk, unlock efficiencies and ultimately maintain competitive advantage.  Pricing actuaries will need to continue to innovate in order to achieve this.</p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/soft-markets--ai-and-next-steps-for-london-market-pricing-27172.htm</link>
<pubDate>Fri, 11 Sep 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Index Shows Both Schemes Hold Steady Through August</title>
		<description><![CDATA[<p>The Broadstone Sirius Index has published its August tracking for a &lsquo;growth focused&rsquo; and a more conservative &lsquo;matching focused&rsquo; investment strategy against a low dependency basis. Both schemes started 90.0% funded at the start of 2026.</p>

<p>Reporting its update for August 2026, the Broadstone Sirius Index found that both schemes held steady throughout the month with the &lsquo;growth focused&rsquo; scheme seeing only 0.6 percentage points between the highest and lowest funding level. The  &lsquo;matching&rsquo; scheme showed a narrower range, as expected, staying in a 0.4 percentage point range.</p>

<p>Overall, the &lsquo;growth focused&rsquo; scheme saw a marginal improvement in funding which rose from 94.1% to 94.2% through the month, while the &lsquo;matching focused&rsquo; scheme dropped by 0.1 percentage points to 89.8% at the end of August.</p>

<p><img alt="" src="https://www.actuarialpost.co.uk/images/pic_BroadstoneSiriusSteady1109261.jpg" style="height:309px; width:600px" /></p>

<p><strong>Andy Knight-Stephens, Investment Director at Broadstone, commented:</strong> &ldquo;August saw gilt yields reach levels not seen for decades. The move was part of a broader global government bond sell-off, driven by persistent inflation concerns and renewed focus on fiscal sustainability.</p>

<p>&ldquo;Growth assets, particularly equities, delivered positive returns over August, with most major equity markets advancing in Sterling terms, despite the continued uncertain macroeconomic backdrop.</p>

<p>&ldquo;Pension schemes will have seen mixed results over the month depending on their composition of fixed and inflation-linked liabilities and approach to investment strategy.</p>

<p>&ldquo;Looking ahead we could see collateral calls for LDI arrangements, and schemes should consider asset allocation rebalancing needs in light of recent growth and matching asset performance.&rdquo;</p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/index-shows-both-schemes-hold-steady-through-august-27170.htm</link>
<pubDate>Fri, 11 Sep 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Spp Backs Vfm Framework With Proportionate Implementation</title>
		<description><![CDATA[<div>Yet the SPP is calling for greater clarity on the framework&rsquo;s scope, particularly for AVCs, hybrid schemes, single employer trusts and future coverage of non-workplace, decumulation and collective defined contribution (CDC) arrangements.</div>

<div> </div>

<div>It also supports the revised approach to investment performance but believes historic performance should carry greater weight than forward-looking metrics, with the latter capped at around 30% to avoid undue reliance on projections.</div>

<div> </div>

<div>The SPP response also welcomes the proposal to assess decumulation strategies separately, recognising that investment approaches for annuity purchase, drawdown and other retirement solutions cannot always be meaningfully compared on a like-for-like basis.</div>

<div> </div>

<div>The SPP urge regulators to retain a proportionate approach beyond the first year, particularly for single employer trusts, bespoke, legacy and non-commercial arrangements, and to guard against league-table behaviour and excessive convergence in investment strategies.</div>

<div> </div>

<div><strong>Dr Amanda Cooke, Chair of the SPP&rsquo;s Financial Services Regulation Committee, said: </strong>&ldquo;The SPP broadly supports the VfM Framework and its aim of improving transparency and outcomes for members. But value for money should not become a box-ticking exercise or drive schemes towards a one-size-fits-all approach. The framework needs to recognise different scheme structures, member needs and retirement strategies, while ensuring that the costs of compliance remain proportionate to the value it delivers.&rdquo;</div>

<div> </div>

<div><a href="https://www.actuarialpost.co.uk/downloads/cat_1/SPP-VfM-Framework-11.9.26.pdf"><strong>The SPP&rsquo;s 16 page consultation response can be read in full here</strong></a></div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/spp-backs-vfm-framework-with-proportionate-implementation-27171.htm</link>
<pubDate>Fri, 11 Sep 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Digital Health Accelerates Ai Adoption</title>
		<description><![CDATA[<p>AI investment builds: planned AI adoption is rising across treatment (86%), personalised services (78%), robotics (89%), diagnosis (84%) and administrative services (78%).Growth cools: 52% of executives expect their business to shrink over the next 12 months.Cyber concern grows: 35% identify cyber risk as a leading concern, while 23% are concerned about cyber attacks resulting in bodily injury.Workforce worries increase: 32% identify workforce competency and professional conduct and misrepresentation risk as a leading concern, outweighing concern over clinical exposure.</p>

<p>As automation deepens, organisations face increasing scrutiny around oversight, accountability and patient safety. At the same time, cyber, clinical, technology and compliance risks are becoming more interconnected, while workforce competency becomes ever more critical to maintaining trust and delivering care in a tech-fuelled environment.</p>

<p>Against this backdrop, digital health business leaders now see fast and reliable claims handling and payment as the most important factor when choosing an insurance partner.</p>

<p><strong>Carolyn Conners, Head of Healthcare at Beazley, said: </strong>&ldquo;As the digital health sector matures, the growth story is becoming more complex. While AI investment continues to accelerate and create significant opportunities, it is also raising important questions about standards of care as companies embed AI and other technologies more deeply into patient services. This makes robust governance, clear policies and procedures, effective human oversight, and well-defined guardrails more important than ever. Partnering with insurers that help organisations manage interconnected risks, proactively prevent losses, and respond effectively when incidents occur will be key to building long-term resilience and sustainable growth.&rdquo;</p>

<p><a href="https://www.actuarialpost.co.uk/downloads/cat_1/Beazley-digital-health-report-2026.pdf"><strong>Beazley Report on Digital Health 2026</strong></a></p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/digital-health-accelerates-ai-adoption-27166.htm</link>
<pubDate>Thu, 10 Sep 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>The Ecb s Second Stitch In Time</title>
		<description><![CDATA[<p>&quot;The justification for the decision lies principally in relation to concerns regarding the outlook for inflation across the single currency region.  Last week&rsquo;s HICP inflation data for August confirmed that higher energy prices are already feeding into higher headline inflation, the year-on-year increase from 2.9% in July to 3.3% last month, almost entirely down to energy.</p>

<p>&quot;More specifically, the central bank will be concerned regarding the sharp increase in regional natural gas prices which are now significantly above the are now significantly above the E45/MWh level identified in its own pessimistic outlook scenario published back in June.  Confirmation that the region&rsquo;s gas storage level stands at just 65% against a 90% target by end-November and the onset of winter, points to a structural supply problem risking another sharp upward price spike not unlike that witnessed in the autumn of 2022.  </p>

<p>&quot;The Governing Council will not want a repeat of the 2022 regional gas supply shock which saw headline inflation rise in excess of 10% and the euro hit parity against the US dollar, thus a strong imperative exists for rate-setters to act pre-emptively even though underlying consumer price pressures appear subdued with few indications, as yet, that higher energy costs are being passed through.</p>

<p>&quot;President Lagarde is likely to face questions in her ensuing press conference regarding how the Governing Council views the recent surge in regional government bond yields.  In part, the bond market sell-off is being driven by international factors over which the ECB has no control, however, the adjustment is being driven, in further part, by rising fiscal concerns, notably in relation to France and Italy.  Mme Lagarde is highly likely to emphasise that the adjustment is not (yet) as pronounced as during regional crises of the past and that its armoury has been subsequently strengthened, particularly through the as yet unused Transmission Protection Instrument (TPI).  </p>

<p>&quot;Nonetheless, senior ECB officials will not want to be criticised for &ldquo;falling behind the curve&rdquo;.  The highly regarded Executive Board member Ms Isabel Schnabel put it well stating recently that, &ldquo;It is critical to prevent the occurrence of second-round effects early on because acting late could necessitate more (policy) tightening (in the future&rdquo;.</p>

<p>&quot;Beyond the justifications lying behind this week&rsquo;s likely rate hike, much will hinge on the ECB&rsquo;s perception regarding the outlook and the evolution of price pressures in particular.  Financial market futures anticipate two further 25-basis point rate hikes, taking the Discount Rate to 3.00% by spring 2027.  Without delivering any specific guidance other than the reiterated commitment to be guided by incoming data and a preparedness to act as necessary, senior officials are unlikely to want to close the door on further rate hikes in coming months.&quot;</p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/the-ecb-s-second-stitch-in-time-27163.htm</link>
<pubDate>Thu, 10 Sep 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Flood Risk In Changing Climate  What Risk Managers Must Know</title>
		<description><![CDATA[<p><u><strong>By Neil Gunn, Head of Flood and Water Management Research, Willis Research Network; and Hayley Fowler, Professor of Climate Change Impacts, Newcastle University.</strong></u></p>

<p>Crucially, severe flooding is increasingly occurring in locations not historically classified as high risk, prompting renewed scrutiny of exposure and preparedness.</p>

<p>Recent flooding illustrates how once-in-a-lifetime events are now occurring in rapid succession. The United States&rsquo; Texas Hill Country floods, with more than 500 millimetres of rainfall in two days, exemplified this shift, resulting in substantial loss of life and revealing gaps in emergency response and insurance coverage. Further evidence of this intensification has been seen in Pakistan, Spain and elsewhere. The persistence and clustering of such extremes align with trends clearly established in 2023 and 2024.  Climate change is increasing rainfall intensity and expanding flood hazard footprints, while societal exposure continues to outpace preparedness.</p>

<p>Flood impacts arise from three principal mechanisms: 1) fluvial flooding, when rivers exceed capacity and inundate surrounding land; 2) coastal flooding, when tides, low-pressure systems and wind-driven surge raise sea levels; and 3) pluvial flooding, when intense rainfall overwhelms drainage capacity.</p>

<div><strong>Pluvial flooding: The hidden driver</strong></div>

<div>While riverine and coastal floods dominate public perception, pluvial floods are a major and growing source of damage. In Britain 6.3 million homes are thought to be at risk of flooding from all sources. Of these, 4.6 million or 73% are at risk from pluvial flooding. According to the Federal Emergency Management Agency (FEMA), in the United States the proportions at risk from the three main flood mechanisms are very similar. In continental Europe, France, Germany and Poland are dominated by fluvial flood risk, but pluvial flooding is the fastest rising driver.</div>

<p>In the U.S., FEMA produces flood maps, which are used to underpin many risk management activities including administration of the National Flood Insurance Program (NFIP). One of the mapped flood extents is the Special Flood Hazard Area (SFHA) which delineate the 1-in-100-year flood outline. However, all but the most recent versions of these maps do not account for pluvial flooding.</p>

<p>Pluvial flood risk is more difficult to map than fluvial or coastal flooding because it can occur far from rivers or coastlines and requires precise elevation data and knowledge of drainage capacity. The largest uncertainty stems from estimating intense rainfall: long-term rainfall records on which this assessment is based are often limited and climate change makes the problem a moving target. Consequently, many countries have been slow to develop or publish pluvial flood maps, leaving significant gaps in risk assessment and planning.</p>

<p>According to a recent study led by the University of Michigan, in the United States, pluvial claims typically result in smaller individual payouts than catastrophic river floods (median damage is about $9,500 per claim versus $51,000 for major events) but their sheer frequency makes them costly in aggregate. In lower risk areas outside SFHAs, pluvial flooding accounts for most claims and casualties. The same study reported that 87% of claims from properties outside FEMA&rsquo;s SFHAs were due to pluvial flooding. Between 1978 and 2021, the NFIP paid $4 billion for pluvial flood claims outside of the SFHA, compared to $2.3 billion for major river floods in the same zones. These figures exclude uninsured losses, which are likely several times higher.</p>

<div><strong>Action for risk managers</strong></div>

<div>Extreme weather is not just a future concern &mdash; it is today&rsquo;s operational reality. Businesses that fail to adapt will face escalating losses, supply chain disruptions and reputational damage. Here are practical steps to strengthen resilience:</div>

<p>Assess exposure by using government tools like the Environment Agency&rsquo;s flood risk map or FEMA&rsquo;s Flood Map Service Center. Do not assume flood risk is zero outside of formal flood zones. Evaluate surface-water risk, especially in urban areas. Consider upstream and downstream dependencies: suppliers, logistics hubs and critical infrastructure.Where possible, register for flood warnings (river and coastal) and explore local alert systems for surface-water flooding. Develop a comprehensive flood plan that assigns clear responsibilities, identifies vulnerable assets and plans to relocate critical equipment above likely flood levels. Establish communication and evacuation protocols. Test and update plans regularly: treat them with the same rigour as fire safety drills. In England, for properties within the 100-year flood plain, a flood is five times more likely than a home fire.Prepare for recovery. In the home, this might mean resilient construction but also simple measures like keeping important papers safe and moving key belongings to safety. In business, this might also mean preparation for five key loss types: premises, people, equipment, IT systems and suppliers.Make sure that insurance coverage is adequate and covers the correct risks including property damage. Be certain that business interruption policies include flooding as a covered peril. Check limits, sub-limits, deductibles and occurrence clauses &mdash; flood events often span multiple days, complicating claims.</p>

<div><strong>Looking ahead</strong></div>

<div>Climate projections indicate that hydrological extremes will intensify, with convective storms delivering rainfall rates far beyond historical norms even in areas with no historical flood record. A new partnership including Willis and Newcastle University, the EXTREME-FUTURES initiative, will combine advanced climate science and AI to improve forecasting and resilience strategies. In the interim, businesses cannot afford complacency. Risk managers must recognise that pluvial flooding now accounts for much of the flood risk in many regions &mdash; and that traditional flood maps do not always capture this threat.</div>

<div> </div>

<p>About the Authors: Neil Gunn, Head of Flood and Water Management Research, Willis Research Network; and Hayley Fowler, Professor of Climate Change Impacts, Newcastle University.</p>

<p> </p>

<p> </p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/flood-risk-in-changing-climate--what-risk-managers-must-know-27167.htm</link>
<pubDate>Thu, 10 Sep 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Footsie Flat As Oil Stays Above  100 A Barrel</title>
		<description><![CDATA[<p><strong>Susannah Streeter, Chief Investment Strategist, Wealth Club: </strong>&ldquo;It&rsquo;s been another lacklustre start for the Footsie as crude prices have stayed stubbornly above $100 a barrel, with no relief in sight. Hopes that there would be some kind of resolution before the US mid-terms, to offer relief at the pumps for voters, have been dashed, with President Trump warning the conflict won&rsquo;t end before the elections. He&rsquo;s trying to woo the electorate instead with helicopter money, offering $5,000 cheques if Republicans retain control of Congress, but this will be sugar-rush money, and while it may boost spending in the short term, it will only add to concerns about the profligate nature of his presidency.</p>

<p>These concerns are showing up as warning lights in the bond markets, especially with Norway&rsquo;s sovereign wealth fund proposing to cut its US Treasury holdings by potentially tens of billions of dollars. A decision by US Treasury Secretary Scott Bessent to ramp up bond buybacks landed like a damp squib. It signalled the administration is worried about yields, but the scale of the buyback suggests it isn&rsquo;t prepared to throw serious financial firepower at the problem. Steamy energy prices appear to be the trigger for these latest moves higher in yields, but there&rsquo;s been an underlying structural shift in the global flow of money for some time as some of the world&rsquo;s biggest institutional investors rotate away from Treasuries to seek returns in corporate debt, with a huge stream issued by AI hyperscalers. Add in the prospect of higher defence spending as geopolitical tensions rise, and there is potentially an even bigger supply of bonds looking for buyers.</p>

<p>And what happens in Treasuries doesn&rsquo;t stay in Treasuries, with the pressure spilling over into other government debt, including gilts. Bond markets are closely connected, with investors constantly comparing the returns available from US Treasuries, UK gilts and other major sovereign debt. The European Central Bank meeting is in sharp focus today, with a hike in interest rates widely expected. Although the decision in itself is not set to be a market mover, President Christine Lagarde's comments will be closely watched for the direction of travel ahead. While she's stressed a future hiking path isn't set in stone, with Eurozone inflation staying creeping higher and hotter energy prices building, speculation is building about future hikes ahead.</p>

<p>There is specific UK pressure building as well, with investors looking ahead to the looming Budget, with government finances already under considerable pressure. Higher oil prices threaten to keep inflation elevated, while higher borrowing costs are already eating into the government&rsquo;s fiscal headroom. The UK has already had to pay its highest yield on a 30-year gilt since the Debt Management Office was established in 1998, at 5.82%, underlining just how sensitive the public finances have become to higher borrowing costs. But demand for the debt was still strong, with investors putting in orders worth more than &pound;87 billion for the &pound;4.25 billion being sold, showing that investors are still willing to buy UK government debt, but at a very high price.</p>

<p>For households and businesses, the consequences eventually filter through in the form of more expensive mortgages, loans and corporate borrowing, potentially weighing on investment and growth, which is why there&rsquo;s so much caution around on equity markets too.</p>

<p>Lacklustre trading has helped propel fast fashion giant Primark into making a U-turn it&rsquo;s resisted for years. Primark is finally joining the home-delivery party, despite a record of repeatedly insisting that its cheap prices made online shopping too expensive to make sense. The retailer now says the success of Click & Collect, improving digital capabilities and a highly automated fulfilment centre in Sheffield have changed the maths, which is why it&rsquo;s lurched into this U-turn. So customers will be able to get their fashion fix delivered when Primark spins off from parent company ABF, with the demerger targeted for the end of 2027.</p>

<p>The economics of home delivery have shifted, with customers also more used to having to pay fees for returns, and the dominance of Shein set to be eroded with the tax treatment of small parcel imports set to change. Primark has benefited from a loyal customer base, and its social media presence keeps them across new styles landing in stores, but its agility has been stifled given that it&rsquo;s been so slow to adapt to the biggest shopping trend this century &ndash; e-commerce. Gone are the days post-pandemic when huge queues snaked round the block to snap up bargains once shops re-opened. It&rsquo;s facing much tougher competition from high street rivals who can keep the digital tills running and parcels landing when conditions turn more inclement. The rolling heatwaves are likely to be partly why Primark&rsquo;s sales have come under sharp pressure as customers have stayed away from scorching high streets amid stifling temperatures. Like-for-like sales are set to be down 3.0% in its fourth quarter to September 12, and UK and Ireland have fared a little better, with sales up marginally by 0.4%, while it&rsquo;s been a struggle across continental Europe where they fell 4.3%. The European market arguably also needs a home delivery boost, but it&rsquo;ll have to wait as the new delivery service is only reserved for the UK, for the meantime. So there&rsquo;s no quick fix available yet for Primark&rsquo;s sliding sales in key markets, while the rollout of the home delivery system in the UK won&rsquo;t come cheap. So investors are turning increasingly sceptical about Primark&rsquo;s prospects, with ABF shares down by more than 9% in early trading.</p>

<p>And the going has got tougher for John Lewis as it's squeezed by challenging consumer behaviour. Sales fell 2% to &pound;2 billion in the six months to August 1, despite revenues across the wider Partnership rising 2%, helped by Waitrose. Shoppers are becoming increasingly cautious about big-ticket purchases, while extreme heat also kept people away from heading out on big shopping sprees. While the soaring temperatures over the summer might have boosted online sales of fans and outdoor goods, and picnic treats, it's made shopping a less attractive hobby as households found ways to cool off instead. When they do want to browse online or in-store, shoppers, with increasingly tight budgets, are being more choosy, looking for bargains or discount sites for a retail fix.</p>

<p>The department store concept is clearly past its prime. In its heyday, they sat at the head of the high street table, but their dominance has been eroded by more agile players, quicker to spot trends and more competitive on price. Shoppers now demand a bigger experience than five floors of goods with the odd demonstration and caf&eacute; thrown in, and John Lewis is struggling to demonstrate its relevance in the new retail landscape.&rdquo;</p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/footsie-flat-as-oil-stays-above--100-a-barrel-27165.htm</link>
<pubDate>Thu, 10 Sep 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Summer s Over  Saving Is On</title>
		<description><![CDATA[<div>As summer draws to a close and many families take stock of the cost of the summer holidays and back-to-school spending, new analysis from the retirement specialist Standard Life suggests that some dual-income households without children, often referred to as 'DINKs' (Dual Income, No Kids), could build an additional &pound;351,000 in retirement savings by directing the equivalent cost of raising a child into their pension.</div>

<div> </div>

<div>This analysis comes as family patterns continue to evolve, with the fertility rate in England and Wales falling to 1.39 children per woman in 20251. For DINK households, lower child-related spending can mean greater flexibility in how disposable income is allocated, creating opportunities to prioritise longer-term financial goals such as retirement saving.</div>

<div> </div>

<div><strong>What if the cost of raising a child went into a pension instead?</strong></div>

<div>To illustrate the long-term impact, Standard Life compared the average estimated cost of raising a child, around &pound;250,000 by age 18.&sup2; Spread evenly across 18 years, this equates to approximately &pound;13,900 a year. Standard Life calculations show that someone who contributed an additional &pound;13,900 to their pension each year for 18 years from the age of 30 could build a pension pot worth approximately &pound;603,000 in today's prices by age 68.&sup3;</div>

<div> </div>

<div>This is around &pound;351,000 more than someone who also started saving at age 22 on a salary of &pound;30,000 a year and contributed only the minimum auto-enrolment amounts (5% employee and 3% employer contributions) throughout their working life, but did not make any additional contributions from age 30.</div>

<div> </div>

<div>Even contributing half this amount (&pound;6,950 a year) could make a significant difference. Standard Life calculations show this could add &pound;175,500 to a retirement fund in today's prices, resulting in a total savings pot of approximately &pound;428,000 by age 68, allowing for inflation.</div>

<div> </div>

<div><img alt="" src="https://www.actuarialpost.co.uk/images/pic_StandardLifeDINK1009261.jpg" style="height:148px; width:600px" /></div>

<div><span style="font-size:11px"><em> *assuming 3.50% salary growth per year, and 5% a year investment growth. Figures allow for 2% inflation. Annual Management Charge of 0.75% assumed. The figures are an illustration and are not guaranteed. Earning limits not applied.   </em></span></div>

<div> </div>

<div><strong>Emma Furlonger, Managing Director for Workplace Pensions at Standard Life, said:</strong> &ldquo;September can be a useful time to take stock of your finances. The summer holidays are over, routines are settling back in, and many people will be thinking again about what they are spending, saving and putting aside for the future.</div>

<div> </div>

<div>&ldquo;For people without child-related costs, there may be periods when there is a little more flexibility in the household budget. It might not be realistic to put the full equivalent cost of raising a child into their pension every year, but these figures show just how powerful additional saving can be when you give it time to grow.</div>

<div> </div>

<div>&ldquo;It doesn&rsquo;t have to be all or nothing either. Whether you have children or not, putting a bit more away when you can, perhaps after a pay rise, once a debt has been cleared or simply at a point when you have more disposable income, can make a meaningful difference over the course of your working life, helping to build greater financial security in later life. The key is finding a balance that lets you enjoy your money today while making sure some of it is working for your future too.&rdquo;</div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/summer-s-over--saving-is-on-27164.htm</link>
<pubDate>Thu, 10 Sep 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Beyond Drawdown</title>
		<description><![CDATA[<div>The webinar, attended by over 300 pension professionals, is part of the SPP&rsquo;s weekly conference programme in September. Attendees were asked, &ldquo;If it was your pension, which guided retirement solution would you prefer&rdquo;</div>

<div> </div>

<div>The polling results showed a clear preference for flexible and blended approaches to retirement income, rather than a traditional annuity-only solution. Retirement CDC also attracted significant support, with 11% choosing it on its own and a further 17% preferring to use it after a period of flexibility.</div>

<div> </div>

<div>In contrast, traditional annuities were the least popular option, with just 3% selecting an annuity as their preferred solution. </div>

<div> </div>

<div><em>Collective drawdown  2%</em></div>

<div><em>Annuity  3%</em></div>

<div><em>Managed income drawdown   9%</em></div>

<div><em>Flex then deferred annuity  10%</em></div>

<div><em>Retirement CDC                 11%</em></div>

<div><em>Managed income drawdown with a minimum income guarantee  13%</em></div>

<div><em>Flex then annuity   14%</em></div>

<div><em>Flex then retirement CDC   17%</em></div>

<div><em>Flex and annuity (i.e. pot at retirement is split part drawdown and part immediate annuity) 19%</em></div>

<div> </div>

<div><strong>Sophia Singleton, SPP&rsquo;s immediate past President, who chaired the event, said: </strong>&ldquo;What&rsquo;s particularly striking about this SPP polling is the breadth of solutions that pension professionals would choose for themselves. The results demonstrate a real appetite to look beyond traditional drawdown and consider how different approaches including Retirement CDC and various flex options, could work to provide better outcomes in retirement.&rdquo;</div>

<div> </div>

<div><a href="https://the-spp.co.uk/events/upcoming-events/">Further SPP event details are available here</a></div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/beyond-drawdown-27168.htm</link>
<pubDate>Thu, 10 Sep 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Terrorism Insurance  25 Years After September 11</title>
		<description><![CDATA[<p><strong>Key highlights include:</strong></p>

<div><em>The September 11 attacks caused roughly $60 billion in insured losses in today's dollar value. The second-largest insured loss event in the U.S. after Hurricane Katrina.</em></div>

<div> </div>

<div><em>In 2022, U.S. Congress enacted the Terrorism Risk Insurance Act, creating a public-private reinsurance backstop to stabilize the market.</em></div>

<div> </div>

<div><em>Emerging risks are expanding the scope of terrorism insurance. In some pools and backstops schemes, losses from cyber terrorism and now covered.</em></div>

<p>&quot;For insurers, the anniversary of the September 11 attacks reinforces the importance of managing exposure concentrations, catastrophe scenarios, and contract certainty, including those caused by cyber terrorism&quot;, <strong>said Marcos Alvarez, Managing Director of Global Financial Institution Ratings.</strong></p>

<p>&quot;In a more volatile geopolitical environment, cyber operations could broaden the transmission of political motivated disruption. A destructive attack on shared cloud services, payments infrastructure, or electricity networks could generate correlated losses among geographically dispersed policyholders.&quot;</p>

<p><a href="https://www.actuarialpost.co.uk/downloads/cat_1/Morningstar_DBRS-Terrorism_Insurance-25_Years_After_September_11.pdf"><strong>Morningstar DBRS Commentary Terrorism Insurance: 25 Years After September 11</strong></a></p>

<p> </p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/terrorism-insurance--25-years-after-september-11-27158.htm</link>
<pubDate>Wed, 9 Sep 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Comments On Activity In The Bulk Annuity Market Over H1 2026</title>
		<description><![CDATA[<p>&ldquo;As in previous years, we expect to see volumes weighted towards the second half of the year, with some large deals expected to complete before the year-end. Since the end of June, insurers have so far also reported a further &pound;6.4bn of transactions either signed or in exclusivity, which underlines the continued momentum in the market.</p>

<p>&ldquo;Competition among insurers remains exceptionally strong, demand remains high from schemes and the market continues to offer attractive opportunities for schemes of all sizes.</p>

<p>&ldquo;The depth of insurer appetite has been particularly evident for small and medium-sized transactions. There have been fewer multi-billion-pound transactions in the market, so more insurers have turned their attention to smaller transactions to meet targets - and more insurers have launched dedicated small-scheme propositions this year.&rdquo;</p>

<p><strong>On key themes across the market in 2026</strong></p>

<p><strong>Dominic Grimley, Partner in Aon&rsquo;s Insurer Due Diligence team, said: </strong>&ldquo;One of the defining features of the market in 2026 is how quickly it continues to evolve. Market growth has demanded a wider search from insurers for attractive asset opportunities, with many insurers now having strong relationships with global asset firms. In the latest of these, Standard Life has recently announced a new proposed partnership with several major investment firms, to provide the capital and asset backing to compete for the market&rsquo;s largest transactions.</p>

<p>&ldquo;Innovation is also extending to member experience. For the most advanced insurer services, members can increasingly manage their pension digitally while the insurers&rsquo; call centres can provide enhanced support for vulnerable customers and potentially utilise live calculations.</p>

<p>&ldquo;There&rsquo;s now more variation in deal structures - developed to address particular client demands. For example, that can be to support a particular desired buyout timing, utilise scheme surplus or to provide members with a potential share of future asset gains.</p>

<p>&ldquo;One of the other facets of the market that we are seeing, is that trustees are placing greater emphasis on evaluating insurers, given how their propositions are evolving through innovation and becoming increasingly sophisticated and differentiated.</p>

<p>&ldquo;Factors such as member experience, financial strength, ESG credentials and cyber resilience are increasingly important points of comparison. Aon's Insurer Due Diligence service has helped trustees and sponsors assess these across over &pound;100bn of transactions, ensuring that trustees can make fully informed decisions.&rdquo;</p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/comments-on-activity-in-the-bulk-annuity-market-over-h1-2026-27159.htm</link>
<pubDate>Wed, 9 Sep 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Db Endgame Options  When Strategy Meets Accounting Reality</title>
		<description><![CDATA[<p><strong>By Tom McMullen, Senior Actuarial Consultant, Hymans Robertson</strong></p>

<p>Early consideration of the accounting implications, supported by proactive auditor engagement, can help sponsors avoid surprises and ensure the chosen strategy is reflected appropriately in their financial reporting. In this article, we explore the key endgame options for defined benefits (DB) schemes, their typical accounting treatments under IAS19 and FRS102, auditor perspectives and considerations sponsors should keep in mind. </p>

<p>The accounting outcome will depend on the route chosen, whether that is buy-in, buy-out, superfund transfer, run-on or another form of external capital support. </p>

<div><strong>Accounting treatment </strong></div>

<div>For buy-ins, buy-outs and superfund transactions, the scheme pays a third party to assume some or all of its liabilities. The accounting impact is typically the difference between the amount paid and the value of those liabilities in the accounts. As transaction pricing is usually based on more prudent assumptions, this difference can be material. The accounting treatment then depends on whether the assets and liabilities remain on the balance sheet. If they do, the impact will generally be recognised through Other Comprehensive Income (OCI); if they&rsquo;re removed, it will typically be recognised through Profit and Loss (P&L). </div>

<div> </div>

<div><strong>Buy-ins </strong></div>

<div><strong>Partial buy-ins</strong> for a subset of members are generally treated as an asset transaction. The impact flows through OCI. </div>

<div><strong>Full scheme buy-ins</strong> can be treated differently depending on the nature of the transaction. If a buy-out isn&rsquo;t expected in the short term, the transaction may be treated in the same way as a partial buy-in through OCI. If a buy-out is imminent, it may be treated as a settlement, resulting in a P&L impact.  </div>

<div> </div>

<div><strong>Buy-outs </strong></div>

<div>Buy-outs are treated as settlements. The liabilities and plan assets are reduced to nil, and the difference is recognised immediately in P&L. If a buy-in took place previously, this P&L item may be nil, or negligible tidying up of residual assets and liabilities. </div>

<div>Superfunds </div>

<div>Accounting treatment is still evolving. Typically, the transfer is treated as a settlement, with liabilities removed and assets derecognised. The difference is recognised in P&L. This reflects that there&rsquo;s no intermediate stage equivalent to the buy-in for an insurance policy.  Immediate recognition of an impact through P&L can create challenges for sponsors. A significant accounting charge may deter sponsors from pursuing an otherwise attractive risk-reduction strategy. It is therefore important to prepare stakeholders for these potential impacts in advance. </div>

<div> </div>

<div><strong>Run-on </strong></div>

<div>The accounting impact of run-on will depend on the detail of the strategy. Constructive obligations around surplus sharing and discretionary benefits can create accounting implications. If a surplus-sharing mechanism is agreed, accounting liabilities may need to increase to reflect expected future benefit enhancements. </div>

<div> </div>

<div>Surplus refunds are treated as negative contributions so affect cash flow but <strong>don&rsquo;t affect P&L</strong>. </div>

<div>Benefit enhancements <strong>are likely to affect P&L</strong>, equal to the additional liability value of the enhancement.  </div>

<p>Surplus sharing under run-on can create a positive outcome for both sponsors and members. However, sponsors need to understand the potential P&L impacts. If this deters sponsors from considering run-on, it could work against the government&rsquo;s ambitions to support growth investment by removing barriers to surplus extraction. Careful structuring of the sharing mechanism can mitigate this impact. <a href="https://www.hymans.co.uk/media/kvhfq1ph/corporate_pension_viewpoint__accounting_implications_of_run-on_and_surplus_sharing-1.pdf">Our previous article </a>explored the accounting implications of surplus sharing in more detail: </p>

<div><strong>What should sponsors consider? </strong></div>

<div>Different endgame options can lead to very different accounting outcomes. Understanding the implications early can help sponsors make informed decisions, engage effectively with stakeholders and avoid surprises later in the process. </div>

<div> </div>

<div><strong>Early engagement: </strong>Sponsors should consult auditors before finalising transactions to avoid surprises and align the accounting treatment.  </div>

<div><strong>Documentation: </strong>The strategy should be carefully documented. Auditors may request evidence of the strategic intent behind the chosen approach to support the accounting treatment. Examples of this could range from management correspondence or meeting minutes to a formal Memorandum of Understanding that sets out the purpose, timings and future plans for the transaction. </div>

<div><strong>P&L sensitivity:</strong> Consider the impact of discretionary increases or settlements and explore mitigations. For example, discretionary benefits that are contingent on future events may have a lower impact than immediate use of existing surplus assets to fund discretionary benefits.  </div>

<div><strong>Regulatory alignment:</strong> Stay informed on evolving legislative changes and guidance.  </div>

<div><strong>Investor education:</strong> Help stakeholders understand the strategic rationale behind the decision. Any accounting impact may not reflect underlying business performance, and the transaction may still deliver positive strategic outcomes despite the accounting result.  </div>

<div> </div>

<div><strong>Final thoughts </strong></div>

<div>Endgame options for DB pension schemes are becoming increasingly relevant as schemes mature and funding levels improve. Accounting standards can be complex and, in some cases, may appear misaligned with intended objectives and economic outcomes of a transaction. It would be helpful if these standards evolved to reduce outcomes that may act as a barrier to sound economic decisions.  </div>

<p>In the absence of change, companies will need to navigate the current landscape carefully. Early engagement with auditors is key to ensuring the chosen approach is reflected appropriately in financial statements and supported by the necessary documentation. By understanding the implications upfront, sponsors can make informed decisions and focus on the strategic benefits of their chosen endgame route. </p>

<p>Accounting shouldn't determine your endgame strategy, but it should form part of the evaluation process. If you'd like to discuss how the accounting implications of different endgame options could affect your organisation.</p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/db-endgame-options--when-strategy-meets-accounting-reality-27161.htm</link>
<pubDate>Wed, 9 Sep 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Oil And Trade Tensions Pile On Inflation Pressure</title>
		<description><![CDATA[<p><em>There are pockets of consumer resilience with Inditex, owner of Zara, reporting first-half sales up 7.6%, with cheaper brands Bershka and Stradivarius particularly strong.The Gym Group sees sales rise despite a membership price hike, with a gym bench more appealing than a pub bar for plenty of younger consumers.</em></p>

<p><strong>Susannah Streeter, Chief Investment Strategist, Wealth Club: </strong>&ldquo;The FTSE 100 has opened lower as investors assess a toxic cocktail of inflationary pressures, with Brent crude nudging towards $100 a barrel and the US-Canada trade war escalating, adding another potential brake on global growth. Far from showing signs of resolution, the conflict in the Middle East appears to be becoming more entrenched, creating chronic supply concerns around crude and gas, while intensifying trade battles threaten to push up the cost of goods just as central banks are trying to get inflation under control.</p>

<p>This may be a bonus for energy companies, with Shell and BP rising in early trade, but it&rsquo;s highly painful for companies and consumers, and puts more pressure on central bankers to raise interest rates. Given the sustained impact of higher energy prices, the worry is that firms will have little choice, other than to raise prices, which risks creating another inflationary spiral. The prospect of higher rates is showing up in the bond markets, with gilt and Treasury yields shifting up yet again, making borrowing more expensive for governments, increasing the prospect of higher interest payments on the huge debts already piled up.</p>

<p>Brent Crude has raced higher, hitting $100 for the first time since July, after Iran ratcheted up its offensive on the US and its allies, hitting two American vessels and firing missiles towards Jordan, while threatening crews in ports in Bahrain and Kuwait. More oil tankers have been struck, and Houthi rebels have also been attacking Saudi Arabia&rsquo;s Jazan refinery, heightening supply worries about energy shipments. It comes after the US military targeted infrastructure on the key Iran export hub &ndash; Kharg Island. While other oil-producing nations have increased production, it&rsquo;s not enough to offset the disruption wreaked across the Middle East, with prices looking set to stay stubbornly around $100 a barrel. UK and European gas prices have also risen again to levels not seen since December 2022. Usually, weaker demand for gas and lower prices during the summer months means stocks can be replenished, but the crisis has kept this process on go slow, and as we head towards the colder winter months, storage levels in the UK and Europe are the lowest for 13 years, keeping nations reliant on imports of expensive supplies. It&rsquo;s set to add to the bill burden of households this winter, with domestic energy prices set to ramp up if a resolution to this conflict remains elusive.</p>

<p>The trade war between the US and Canada has also moved up a gear, with Washington banning a range of Canadian imports, including dairy and alcohol, after Canada imposed retaliatory tariffs on US goods. It&rsquo;s another unwelcome inflationary jolt, as tariffs push up the cost of goods and leave businesses and consumers footing more of the bill. And at a time when oil prices are already surging, the combination of more expensive energy and more expensive goods is a particularly nasty cocktail, threatening to squeeze consumers, dent business investment and put another drag on global growth. While the TACO trade  - &lsquo;Trump Always Chickens Out&rsquo; is still alive to some extent, with investors used to expecting threats to be softened or reversed, but this more capricious approach to policymaking is highly disruptive. Even when trade deals are struck, other countries can&rsquo;t be sure they&rsquo;ll hold, making businesses more reluctant to invest and plan ahead.</p>

<p>However, there are pockets of resilience amid all this uncertainty. Fashion lovers seem to have shrugged off worries about conflict and climate change and spent big on wardrobe refreshes. Zara owner Inditex has reported a record &euro;19.8 billion in first-half sales, up 7.6%, with profits rising 6.8% to just under &euro;3 billion, while sales in August and early September jumped 9%.</p>

<p>It&rsquo;s a pretty strong fashion statement and a badge of honour for Zara&rsquo;s design and merchandising teams who are on the money when it comes to creating the looks to make shoppers part with their cash, even when household budgets are under pressure. There&rsquo;s still appetite for retail therapy, particularly if the price is right, with Bershka and Stradivarius delivering double-digit sales growth. These brands are at the slightly cheaper end of Zara&rsquo;s wardrobe of fashion names, and seem to be touching the sweet spot when it comes to a desire for style updates, while keeping an eye on tighter budgets. Sportswear brand Oysho also saw sales grow by more than 20%, capitalising on the desire to get fit and the growing gym scene.</p>

<p>The Gym Group has been flexing its pulling power among young fitness fans, with sales jumping even though it put up its fees. Membership prices increased by 10%, but the numbers signing up still rose by 5% in the first half. The Gym Group has now reached around a million members, showing that going to the gym has become a deeply embedded habit. It&rsquo;s also the price point that matters, because even after the recent increases, memberships remain around the &pound;25&ndash;&pound;30-a-month mark at many sites, which is a fraction of the cost of premium health clubs such as David Lloyd. The Gym Group&rsquo;s average member is around 30, with Gen Z now making up 44% of its membership. It&rsquo;s clear that the gym is increasingly becoming a crucial part of social lives rather than simply somewhere to go and work up a sweat. It&rsquo;s a sign of changing spending habits and priorities among younger consumers, with a gym bench rather more appealing than a pub bar.&rdquo;</p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/oil-and-trade-tensions-pile-on-inflation-pressure-27160.htm</link>
<pubDate>Wed, 9 Sep 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>6m  Unsure How They  039 ll Pay Rent Or Mortgage In Retirement</title>
		<description><![CDATA[<div>More than six million people who expect to pay housing costs in retirement don't know how they'll afford them, according to the latest research from Royal London.  The research found that around one in three UK adults (34%), equivalent to 18.7 million people, either expect to pay housing costs in retirement or are already doing so. Four in ten (39%) of the approximately 16 million UK adults who expect to pay housing costs say they don't know how they'll pay their rent or mortgage once they stop working. </div>

<div> </div>

<div>Renters face the biggest challenge, but almost four in ten mortgage borrowers won&rsquo;t be mortgage free when they retire. Six in ten renters (61%) expect to have housing costs in retirement, compared with 37% of mortgage borrowers. Nearly half of renters (45%) believe they'll still be paying rent for more than 10 years after they retire, while just 7% of mortgage holders expect to be making mortgage payments for that long.  </div>

<div> </div>

<div>The findings come as rising housing costs and longer mortgage terms mean more people are likely to enter retirement still paying for a roof over their head. Younger adults are particularly affected. More than four in ten (44%) people aged 18 to 34 expect to have housing costs in retirement, compared with 24% of those aged 50 to 69. On average, homebuyers aged 18 to 34 have an original mortgage term of 31 years, and 43% took out a mortgage with an original term of 35 years or longer. By comparison, just 2% of retirees originally took out their mortgage for a term of 35 years or more.  </div>

<div> </div>

<div><strong>Housing costs could put additional pressure on retirement incomes </strong></div>

<div>The research highlights how broader financial circumstances, including housing costs and income levels, can influence people's ability to save for retirement and build long-term financial resilience. Those who expect to pay housing costs in retirement have an average pension pot of &pound;34,948, compared with &pound;120,682 among those who don't. The average pension savings figure across all respondents was &pound;93,221.  </div>

<div> </div>

<div>People struggling financially are also more likely to face housing costs in later life. Nearly six in ten (59%) people who describe themselves as being in financial crisis expect to pay rent or mortgage costs in retirement, compared with just 11% of those who say they are financially comfortable.  </div>

<div> </div>

<div><strong>Regional differences </strong></div>

<div>The likelihood of paying housing costs in retirement varies across the country. People living in London, the South East, and the South of England, are among the most likely to expect housing costs in retirement, with 34% saying they expect to still be paying rent or a mortgage after they retire. This compares with 23% in Yorkshire and the Humber. Meanwhile, more than half (53%) of people in the North East of England who expect to have housing costs in retirement say they don't know how they will pay them, significantly higher than the UK average of 39%.  </div>

<div> </div>

<div><strong>Sarah Pennells, Consumer Finance Specialist at Royal London, said: </strong>&quot;For generations, reaching retirement often meant reaching the point where housing costs were behind you. But for millions of today's retirees and future retirees, that simply isn't the reality. Whether it's renting for longer, taking out larger mortgages or stretching repayments over decades, more people are approaching retirement still facing significant housing costs. What's particularly worrying is that over six million people who expect to pay rent or mortgage costs in retirement don't know how they'll cover those payments. If you're heading towards retirement and expect to have housing costs, it's important to factor these into your retirement planning as early as possible. </div>

<div> </div>

<div>&quot;Housing costs can make a huge difference to how far retirement income will stretch. Understanding what your housing costs could look like in later life can help you develop a more realistic picture of the income you'll need in retirement.&quot; </div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/6m--unsure-how-they--039-ll-pay-rent-or-mortgage-in-retirement-27162.htm</link>
<pubDate>Wed, 9 Sep 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>When Water Becomes The Constraint</title>
		<description><![CDATA[<p>Inland waterways have long been established as efficient, environmentally favourable means of moving cargo, with ships and barges on major corridors such as the Rhine, Danube, Mississippi, Yangtze and Paran&aacute; able to carry substantial volumes at lower cost and emissions than road transport; however, recurrent drought conditions are increasing operational pressure through vessel loading restrictions, reduced draughts, navigation bottlenecks, delays, grounding incidents and rising freight costs.</p>

<p>TT Club warns that the consequences extend well beyond individual vessels. Reduced carrying capacity can disrupt port throughput, create inventory imbalances at warehouses and generate sudden demand for alternative rail and road capacity. The resulting disruption can cascade through interconnected supply chains.</p>

<div><strong>A wider resource-allocation risk</strong></div>

<div>Recent conditions on the Danube have highlighted a further concern: access to navigable waterways may be constrained by decisions beyond the control of transport operators.</div>

<p>In Romania, authorities faced difficult choices over the allocation of limited water resources, balancing the requirements of navigation with those of critical infrastructure, including energy generation. As climate pressures intensify, governments may increasingly need to balance water use between drinking supplies, agriculture, energy production and transportation.</p>

<p>This presents a less-recognised climate-related supply chain risk. Businesses dependent on inland waterway transport could be affected not only by low water levels themselves, but also by broader societal decisions when water becomes scarce.</p>

<p><strong>Neil Dalus, Risk Assessment Manager at TT Club, commented: </strong>&ldquo;Inland waterways remain an essential component of efficient, lower-emission freight transport. However, the assumption that these corridors will always provide a dependable alternative to road and rail must now be challenged.</p>

<p>&ldquo;Drought should no longer be considered a rare environmental issue. It is a business continuity risk with the potential to affect vessel capacity, route availability, port operations and the wider transport network. The question for operators is not whether low-water conditions will occur, but whether they have the visibility, flexibility and contingency arrangements required to manage them.&rdquo;</p>

<div><strong>Resilience alongside decarbonisation</strong></div>

<div>The challenge is particularly significant as supply chain strategies increasingly seek to shift cargo towards inland waterways in support of decarbonisation objectives. TT Club stresses that the environmental case for waterborne freight remains compelling, but sustainable transport choices must also be resilient transport choices.</div>

<p>Organisations should therefore move beyond planning based principally on historical water levels and incorporate climate-informed decision-making into their wider risk-management processes.</p>

<p><strong>TT Club recommends that operators consider priority measures including:</strong></p>

<p><em>Mapping dependencies on inland waterways and identifying vulnerable transport corridors</em></p>

<p><em>Monitoring river levels and incorporating drought forecasts into cargo and fleet planning</em></p>

<p><em>Establishing alternative road, rail and storage arrangements before restrictions arise</em></p>

<p><em>Stress-testing supply chains against prolonged periods of reduced vessel carrying capacity</em></p>

<p><em>Reviewing contractual, inventory and contingency arrangements for recurring low-water disruption</em></p>

<p><em>Using real-time data, remote sensing, predictive analytics and operational intelligence to support earlier decisions</em></p>

<p>Dalus continued: &ldquo;The most resilient organisations will be those that understand their dependencies, can activate alternative transport options quickly and have already considered how their supply chains will perform under persistently constrained conditions.&rdquo;</p>

<p>TT Club concludes that organisations must combine sustainability ambitions with a clear understanding of climate-related operational risk, building the flexibility needed for a future in which water itself may become one of supply chains&rsquo; most important constraints.</p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/when-water-becomes-the-constraint-27153.htm</link>
<pubDate>Tue, 8 Sep 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Trade And Geopolitical Tensions Add To Inflationary Concerns</title>
		<description><![CDATA[<p>The Strait of Hormuz remains the key pressure point, with shipping traffic slowing amid Iranian threats of retaliation and concerns that disruption could persist. European and UK gas prices have climbed to three-and-a-half-year highs, amid ongoing conflict. Qatar had already extended its suspension of some LNG shipments and European storage remains below usual seasonal levels. Economies are still showing resilience with data dump over past week showing increased activity and job strength particularly in the US.</p>

<p><strong>Susannah Streeter, Chief Investment Strategist, Wealth Club: </strong>&ldquo;Trade tensions and geopolitical stalemate are adding to inflationary concerns &ndash; pushing prices up across a large basket of commodities, which will feed through to household and business costs. The moves are adding to the note of caution reverberating on financial markets, as investors assess the likelihood that interest rates may have to stay higher for longer to keep a lid on consumer prices.</p>

<p>Tariff wars have reared up again after Canada slapped billions of dollars of retaliatory tariffs on American goods, after talks with the US administration collapsed. The former trade allies have turned foes, with President Trump turning up the heat, and the latest measures are likely to add another layer of uncertainty for businesses and consumers. Canada&rsquo;s retaliatory tariffs on around $20 billion of US goods came into effect today, with duties ranging from 15% to 50%.</p>

<p>Even the threat of further tariffs is distorting market prices, with copper futures reaching a record high as US importers stash the metal in warehouses amid expectations of higher duties ahead. Operational issues at major mines have also conspired to push prices higher, amid concerns about supply backlogs as demand surges for a metal so sought after for the world&rsquo;s electrification drive and the build-out of AI infrastructure.</p>

<p>While this provides support for mining stocks, it&rsquo;ll add to manufacturing costs, with gadgets small and large already set to rise in price due to chip shortages. Meanwhile geopolitical tensions are also adding to inflationary pressures. The lack of success in the Russia-Ukraine talks has led to renewed concerns over wheat supplies. Ukraine, known as the breadbasket of Europe, has already seen exports sideswiped by the war. With hopes dashed for a faster resolution, there are renewed concerns that export capacity will be constrained due to Russia&rsquo;s denial tactics over Black Sea shipments. Conflict is colliding with the effects of El Ni&ntilde;o-related drought, exacerbating potential crop shortages. This toxic combination of war and weather risks driving up food prices next year, just as consumers are already feeling the squeeze from higher energy and other household costs.</p>

<p>Oil and gas prices are painfully elevated, with Brent crude heading above $98 a barrel and wholesale gas prices shooting sharply higher as the market prices in heightened risks around the Strait of Hormuz.  Talks between Iran and Oman to manage shipping through the key Strait of Hormuz appear to be making good progress and while that&rsquo;s encouraging in the short term, it could allow Iran to wield much more control over this key waterway in the future, paving the way for potential future disruption. President Trump has previously threatened to bomb Oman if it got in the way, and although he&rsquo;s gone quieter on the subject recently, the US still appears determined to call the shots when it comes to transit through this vital waterway.</p>

<p>Iran has continued attacking US allies, with Saudi Aramco&rsquo;s facilities in Jazan near the Red Sea hit again yesterday and Tehran threatening further attacks on infrastructure in the region. This has again heightened worries about future supplies, particularly gas heading towards Europe and Asia.</p>

<p>European gas storage levels are below the seasonal average, leaving the market vulnerable as winter months approach. Qatar&rsquo;s extension of its suspension of shipments means that those levels can&rsquo;t easily be replenished, with supply concerns amid high demand pushing European and UK gas prices back up to levels not seen for three and a half years. For now, gas prices are still way below the spike we saw in the months following the outbreak of the Ukraine war, and Brent has so far failed to breach the psychologically important $100 threshold. Alternative export routes, some oil still moving through the Strait of Hormuz, rising production from outside OPEC and softer demand are helping to cushion the supply shock to some extent.</p>

<p>Higher energy, food and manufactured goods prices look set to put fresh pressure on finances, increasing the political pressure on governments to step in and help shield households and businesses from the hit. But ministers are in a tight spot, with borrowing costs still elevated, with yields on government debt stubbornly high. So they have little room to offer more support without raising taxes or squeezing spending, both of which could put another brake on an already fragile economy. Still there are glimmers of resilience with data over the past week showing the services sector continued to expand in August, while the eurozone economy is also holding in expansion territory, with manufacturing showing signs of improvement. Across the Atlantic, the US looks particularly robust, with employers adding 162,000 jobs in August, helped by a surge of construction activity partly fuelled by the mega data centre build out to power the AI trade.</p>

<p>So while the latest energy and trade shocks are clearly a threat to growth, there appears to be some underlying momentum across economies, which could help absorb some of the price pressure.&rsquo;&rsquo;</p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/trade-and-geopolitical-tensions-add-to-inflationary-concerns-27150.htm</link>
<pubDate>Tue, 8 Sep 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Comment On Artwork Worth  8m Stolen From Renoir Museum</title>
		<description><![CDATA[<div>While museums generally maintain robust security measures, no protection system is infallible. From an insurance perspective, the focus is not only on preventing theft, but also on ensuring comprehensive documentation, proven provenance records and effective recovery plans that can support the return of stolen works where possible.&quot;</div>

<div> </div>

<div>&quot;Although the headline figure is substantial, events like this are a reminder that the true exposure extends beyond the market value of the artworks concerned. Masterpieces by internationally recognised artists such as Renoir carry significant cultural and historical importance, which cannot simply be replaced through a claims settlement.</div>

<div> </div>

<div>&quot;High-profile works will always attract criminal interest due to their global recognition and value so it is important to make it as difficult and time consuming as possible for thieves to get to them. The fine art insurance market has invested heavily in supporting museums, galleries and private collectors through specialist risk assessments, security reviews and collection management advice. However, smaller museums often pose a particular challenge: many were once private houses and installing high level security is both difficult and expensive. They are also unlikely to have night watchmen so thieves can get in and out before the authorities are able to respond to the alarms.</div>

<div> </div>

<div>&quot;The fact that one of the works was reportedly dropped during the thieves' escape also illustrates another important aspect of the risk. Damage occurring during a theft can sometimes prove as significant as the theft itself, creating complex restoration and valuation considerations.</div>

<div> </div>

<div>&quot;Incidents of this nature reinforce the importance of maintaining detailed inventories, up-to-date valuations, robust physical security measures and clear recovery protocols. These elements are critical both in mitigating losses and in maximising the likelihood of recovering stolen works.&quot;</div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/comment-on-artwork-worth--8m-stolen-from-renoir-museum-27156.htm</link>
<pubDate>Tue, 8 Sep 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Insurance As A Strategic Enabler Of Business Growth</title>
		<description><![CDATA[<p><strong>By Sana Haseeb, Business Development Executive, Howden</strong></p>

<p>It demonstrates to investors, lenders, customers, and other stakeholders that the business understands its risks, has a plan to manage them, and possesses the financial resilience to withstand unexpected setbacks.</p>

<div><strong>Why investors care about risk management</strong></div>

<div>When investors assess a business, they are not solely evaluating revenue growth or profitability. They are also considering the organisation's ability to protect future earnings, maintain operations, and recover from disruption.</div>

<p>Strong governance, robust internal controls, business continuity planning, cyber resilience, and appropriate insurance arrangements all play an important role in reducing uncertainty. Together, they provide reassurance that management has identified its key risks and taken sensible steps to mitigate them.</p>

<p>For investors, this translates into confidence. For growing businesses, that confidence can make a meaningful difference when seeking funding, attracting strategic partners, negotiating lending facilities, or preparing for a future exit.</p>

<div><strong>Insurance as part of a wider risk management programme</strong></div>

<div>Insurance should never operate in isolation. The most resilient organisations integrate their insurance programme into a broader risk management framework, encompassing:</div>

<div> </div>

<div><em>Business continuity planning</em></div>

<div><em>Cyber security and data protection</em></div>

<div><em>Supply chain resilience</em></div>

<div><em>Health and safety management</em></div>

<div><em>Environmental and regulatory compliance</em></div>

<div><em>Director and officer risk management</em></div>

<div><em>Financial and operational controls</em></div>

<p>Together, these disciplines help protect a business's ability to generate revenue, serve customers, and respond effectively when challenges arise. Insurance may help mitigate the impact of losses, enabling businesses to absorb significant losses without jeopardising future growth plans, cash flow, or stakeholder confidence.</p>

<div><strong>Lessons from real-world businesses</strong></div>

<div> </div>

<div><strong><a href="https://www.londonstockexchange.com/news-article/VTU/business-interruption-insurance-settlement/17570707">Vertu Motors (2026)</a> - Insurance protecting profitability</strong></div>

<div>Vertu Motors demonstrated the value of a well-designed insurance programme following disruption caused by the Jaguar Land Rover cyber incident in 2025. The attack affected vehicle supply, parts availability, and critical operational systems across the retailer's network.</div>

<p>As a result of its business interruption insurance arrangements, Vertu Motors secured a &pound;3.9 million settlement, delivering a net recovery of &pound;3.4 million after excess. The outcome directly enhanced the company's expected profitability and highlighted the important role insurance can play in protecting earnings when unforeseen events occur. While the cyber incident itself was outside Vertu's control, the financial impact on the business was significantly reduced because the appropriate protection was already in place.</p>

<div><strong><a href="https://www.insurancebusinessmag.com/us/news/cyber/major-uk-retailers-cyber-breach-offers-lessons-for-us-businesses-551161.aspx">Co-op (2025)</a> - The cost of being underinsured</strong></div>

<div>The Co-op's widely reported cyber incident in 2025 provides a contrasting example. The attack reportedly reduced annual profits by approximately &pound;120 million and impacted revenues by more than &pound;200 million.</div>

<p>Although the business was able to maintain many customer-facing operations, reports later suggested it did not have comprehensive cyber insurance in place to recover a significant proportion of the associated business interruption losses.</p>

<p>The case has since become a notable example of the distinction between risk prevention and risk transfer. While investment in cyber security remains essential, even strong controls cannot eliminate risk entirely. Insurance exists to provide financial recovery when preventative measures alone prove insufficient. Individual claim outcomes will depend on the circumstances, policy terms and extent of cover in place.</p>

<div><strong>Finding a partner that can grow with you</strong></div>

<div>One of the most common challenges facing growing businesses is that their risk profile often evolves faster than their insurance programme. What may have been appropriate for a &pound;5 million turnover business can quickly become inadequate as revenues, headcount, contractual obligations, international exposures, and investor expectations increase.</div>

<p>This is why organisations should seek an insurance partner that offers more than policy placement. The right adviser should anticipate changing insurance requirements, provide market insight, benchmark coverage against industry peers, support mergers and acquisitions activity, and ensure programmes remain aligned to business objectives. The objective is not simply to insure today's operation, but to support tomorrow's ambitions.</p>

<div><strong>Looking beyond Insurance</strong></div>

<div>A well-structured insurance and risk management programme provides reassurance to investors, confidence to lenders, credibility with customers and protection for leadership teams. Whether opening new locations, investing in technology, entering new markets or making acquisitions, growth inevitably involves uncertainty. Insurance does not remove that uncertainty, but it provides the financial resilience needed to move forward with conviction.</div>

<p>When aligned with a company's wider ambitions, insurance becomes far more than a transactional purchase. It becomes a strategic tool that can support wider business objectives, including helping demonstrate effective risk management and financial resilience to investors, lenders and other stakeholders. Insurance may be designed to protect against loss, but at its best, it provides something far more valuable: the confidence to grow.</p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/insurance-as-a-strategic-enabler-of-business-growth-27157.htm</link>
<pubDate>Tue, 8 Sep 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>The Generation That Cannot Picture Retirement</title>
		<description><![CDATA[<p>Generation X are struggling more than any other generation to picture their retirement, with more than one in ten (11%) unable to imagine life after work - more than twice the proportion of any other age group, new PensionBee research reveals. </p>

<p>For a generation now in their late 40s and 50s, that uncertainty is showing up in how they prepare for later life. More than half (56%) say they didn't seriously think about their pension until they were 46 or older, while nearly half (48%) feel they've left retirement planning too late.</p>

<p>Around one in ten (11%) Gen X respondents also say they feel indifferent about retirement &ndash; the highest proportion of any generation. Taken together, the findings suggest retirement remains a distant  or hard to picture prospect for a significant slice of this generation, despite it moving increasingly close. </p>

<div><strong>Left too late, for practical reasons</strong></div>

<div>That late start has left its mark. Nearly half of Gen X (48%) say they feel they have left retirement planning too late, the highest proportion of any generation.</div>

<p>But for many, the issue wasn't a lack of interest, but a lack of financial headroom. Gen X savers who feel they started too late, four in ten (40%) say they simply couldn't afford to engage with their pension sooner, while almost one in five (18%) didn't know where to start.</p>

<div><strong>Caught between two pension eras</strong></div>

<div>Gen X has also been caught between two pension eras. Many began their careers as final salary pensions were either disappearing from the private sector, but before Auto-Enrolment was introduced in 2012. </div>

<p>As a result, many missed out on the years of automatic pension saving that younger generations will benefit from throughout most of their working lives. now take for granted. At the same time, many Gen Xers have become the backbone of the so-called &ldquo;sandwich generation&rdquo;, supporting ageing parents while still helping dependent or returning adult children. With mortgages, university costs and potentially care bills competing for the same money, their own retirement savings can easily slip down the priority list.</p>

<p>The wider evidence suggests Gen X has a particular reason to feel uncertain about retirement. The Government's Pensions Commission warned that around 15 million people are undersaving for later life, identifying Generation X as facing a particularly acute challenge. In its central scenario, 46% of Gen X are projected to fall short of the income needed to maintain their standard of living in retirement, the highest proportion of any generation. Almost a third (32%) of Gen X savers with defined contribution pension wealth have less than &pound;50,000 saved, according to its findings. </p>

<p><strong>Maike Currie, VP Personal Finance, PensionBee, comments: </strong>&quot;You can't plan for a future you can't picture. Gen X are getting closer to retirement than any other working generation, yet for many it still feels abstract. When you can't see what you're aiming for, it's much harder to work out what you need to save to get there. to turn it into something you can plan, save and prepare for.</p>

<p>&quot;Gen X have been squeezed from every angle. They came of age as final salary pensions were disappearing, meanwhile Auto-Enrolment arrived later in their careers. They have weathered repeated economic shocks while many have found themselves sandwiched between supporting children and caring for ageing parents. It's no surprise their own retirement has sometimes slipped down the priority list.</p>

<p>&quot;But being behind doesn't mean being stuck. Gen X may have been born to retire, but they weren't necessarily given the easiest route to get there. The first step is to make retirement real. Find old pensions and bring them together, then use a pension calculator to put a rough number on the life you want in retirement. Once you can see the gap between where you are and where you want to be, you can start doing something about it.</p>

<p>&ldquo;However this isn't just down to individuals. Gen X risks becoming the first generation to retire worse off than the one before. That should be a wake-up call for the government and policymakers. This is an overlooked generation that needs the tools, support and flexibility to catch up while there is still time.&rdquo;</p>

<p> </p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/the-generation-that-cannot-picture-retirement-27151.htm</link>
<pubDate>Tue, 8 Sep 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Ppf Publish Latest Ppf 7800 Figures For August 2026</title>
		<description><![CDATA[<p>A scheme&rsquo;s s179 liabilities represent, broadly speaking, the premium that would have to be paid to an insurance company to take on the payment of PPF levels of compensation. This compensation may be lower than full scheme benefits.  </p>

<p><strong>Highlights  </strong></p>

<p><img alt="" src="https://www.actuarialpost.co.uk/images/pic_PPF7800AUG0809261.jpg" style="height:195px; width:600px" /></p>

<p><strong>Aaron Pang, PPF Acting Chief Actuary, said:</strong> &ldquo;During August, movements in assets and liabilities were relatively modest across the PPF eligible universe. Asset values edged down by 0.1%, while liability values fell by 0.4%, resulting in a slight improvement in overall funding. The aggregate surplus increased to &pound;273.6bn and the funding ratio rose to 133.4%, reflecting the continued resilience of DB scheme funding levels despite ongoing market uncertainty.&rdquo;</p>

<div><strong>A note on changes to the PPF 7800 Index</strong></div>

<div>In our December 2025 update, we highlighted that the government had announced that it would legislate to allow us to pay prospective indexation starting from 2027 for service accrued pre-1997 for members of schemes who provided this as a right. As well as schemes that have already transferred to the PPF, this will also impact the s179 liabilities of schemes in the PPF universe. In April the Pension Schemes Act received Royal Assent. As we&rsquo;ve signposted, we&rsquo;ll reflect the impact from these changes in the PPF 7800 Index in due course.</div>

<p>View the September update and see the supporting data on the 7800 Index for 31 August 2026 here: <a href="https://www.ppf.co.uk/ppf-7800-index">The PPF 7800 index | Pension Protection Fund.</a></p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/ppf-publish-latest-ppf-7800-figures-for-august-2026-27152.htm</link>
<pubDate>Tue, 8 Sep 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Comments On Latest Ppf 7800 Figures From The Ppf</title>
		<description><![CDATA[<div><strong>Jaime Norman, Senior Actuarial Director, Broadstone, commented: </strong>&ldquo;Pension scheme funding is continuing to weather persistent volatility, with funding ratios nudging up thanks to resilient equity market performance. With the UK bond market seeing continued turbulence of late and tensions in the Middle East appearing to be a long way from resolution, trustees will be considering the implications of future interest rate calls and preparing their investment strategies for the potential of further market movements. The de-risking market remains extremely competitive but many schemes will still be looking to capitalise on funding levels to secure member benefits through the insurance market. With a growing number of options available to trustees, however, it will be important to consider all endgame options, particularly around the use of surplus, which could promote the advantages of schemes to run on.&rdquo;</div>

<div> </div>

<div>
<p><strong>Vishal Makkar, Managing Director, UK Wealth Consulting at Gallagher comments: </strong>&ldquo;The rise in the aggregate DB surplus to &pound;271.3bn comes at an important moment for the pension sector. The closure of the Department for Work and Pensions&rsquo; consultation to give well-funded DB schemes greater flexibility to release surplus has laid the groundwork for a new paradigm. The overall guidelines are still taking shape, and it is possible the final iteration of the guidance will be more streamlined. In the interim, it's important that trustees continue to pursue their scheme's long-term objectives. For some schemes, a strong surplus may be a catalyst to explore their options in the buy-out market. For others, particularly those with strong governance and sponsor support, retaining the scheme and taking a longer-term approach could offer greater scope to respond to changing circumstances and investment opportunities. As the market evolves, greater freedom must be matched by strong governance. Trustees must consider a wider range of options, including longer-term investment opportunities, in a manner consistent with both their fiduciary duties and their members&rsquo; interests. Each scheme will have its own individual circumstances and objectives, and strategies should be drawn up accordingly.&quot;</p>

<p><a href="https://www.actuarialpost.co.uk/article/ppf-publish-latest-ppf-7800-figures-for-august-2026-27152.htm">PPF publish latest PPF 7800 figures for August 2026</a></p>
</div>

<p> </p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/comments-on-latest-ppf-7800-figures-from-the-ppf-27154.htm</link>
<pubDate>Tue, 8 Sep 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Put Off By Student Debt </title>
		<description><![CDATA[<div>As thousands of students prepare to head to university in the coming weeks, new analysis from the retirement specialist Standard Life highlights the financial trade-offs facing parents who want to help to meet the cost. With student debt attracting renewed attention amid rising tuition fees and fresh debate over the interest charged on student loans, Standard Life finds that 11% of parents financially supporting their adult children are helping with university fees to reduce their child&rsquo;s student debt.</div>

<div> </div>

<div>However, parents looking to shield their children from borrowing could risk putting their own retirement finances under pressure. With maximum tuition fees in England now &pound;9,790 a year for the 2026/27 academic year, and living costs adding significantly to the bill, the headline cost of a three-year degree can now reach around &pound;90,000, or more than &pound;106,000 in London.</div>

<div> </div>

<div>Standard Life analysis finds that a parent aged 55 who withdrew &pound;90,000 from their pension - equivalent to the potential cost of a three-year university degree - could reach retirement with &pound;119,000 less in their pension pot.3 For those covering the equivalent cost of studying in London, the potential retirement hit rises to &pound;140,000. The findings come as nearly three quarters (74%) of parents providing financial support to adult children say doing so has affected their own finances.</div>

<div> </div>

<div><strong>The hidden cost of dipping into a pension</strong></div>

<div>The figures are based on an individual who, at the age of 55, has a pot of &pound;425,000 &ndash; just large enough to cover the potential full headline cost of a three-year degree from their pension tax-free cash. If they accessed no pension money until the age of 68, they could build up a pot of &pound;677,000 by the age of 68, allowing for inflation.</div>

<div> </div>

<div>If they withdrew &pound;90,000 at age 55 to cover the cost of a three-year degree outside of London, this could reduce their retirement fund at 68 to &pound;558,000 in today's prices - &pound;119,000 less than if the money had remained invested. Someone withdrawing &pound;106,000 to cover the cost of studying in London could see their retirement fund fall to &pound;537,000, a difference of &pound;140,000.</div>

<div> </div>

<div>While the remaining pension savings could continue to grow, the money that has been withdrawn would no longer be invested and so would miss out on potential growth in the years leading up to retirement. As a result, some of the reduction in the pension pot is potentially recovered through future investment returns, but not enough to fully offset the impact of the withdrawal without significantly increasing contributions later on.</div>

<div> </div>

<div><img alt="" src="https://www.actuarialpost.co.uk/images/pic_StandardLifeUni0809261.jpg" style="height:150px; width:600px" /></div>

<div><span style="font-size:11px"><em>*assuming salary of &pound;50,000 at the age of 55, 3.50% salary growth per year, and 5% a year investment growth. 7% employer and 7% employee pension contributions. Figures account for 2% inflation. Annual Management cost of 0.75%.</em></span></div>

<div> </div>

<div><strong>Neil Jones, Tax and Estate Planning Specialist at Standard Life, said:</strong> &quot;It's understandable that many parents look at the size of student loan balances today and want to do everything they can to help their children avoid taking on that debt. Concerns about the interest charged on student loans have also added to the debate about whether young people are getting value from the current system. And, with unspent pension pots set to fall within the scope of inheritance tax from April 2027, gifting money to children during their lifetime could be a sensible estate planning strategy for some parents.</div>

<div> </div>

<div>&quot;At the same time, it&rsquo;s important to remember that student finance works differently from most other forms of borrowing. Repayments are linked to earnings rather than simply the amount owed, so paying off or avoiding student debt altogether won't always deliver the financial benefit families might expect.</div>

<div> </div>

<div>&quot;Pension savings are different - money withdrawn today is no longer there to benefit from future investment growth, and for people approaching retirement there may be limited time to rebuild what has been taken out. Major life moments often involve balancing competing financial priorities. Supporting children through university can be incredibly rewarding, but it's important that parents also consider the impact on their own long-term financial future. Taking time to understand the trade-offs can help families make decisions with greater clarity and confidence, while helping to protect their long-term financial security and the retirement they are working towards.&rdquo;<br />
 </div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/put-off-by-student-debt--27155.htm</link>
<pubDate>Tue, 8 Sep 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Oil Surges  Borrowing Costs Rise As Healey Faces Tough Test</title>
		<description><![CDATA[<p><strong>Susannah Streeter, Chief Investment Strategist, Wealth Club: </strong>&lsquo;&rsquo;As the war with Iran appears even more entrenched, energy prices are on the rise again, creating a mood of caution. As inflationary risks stay elevated the FTSE 100 has fallen back as traders keep a close eye on Brent Crude, the benchmark which has scurried back above $97 a barrel. The moves come after attacks between the US and Iran intensified. American forces have targeted three oil tankers, after Iranian strikes on US warships. With the US trying to maintain a blockade on Iran crude exports, and the strikes from both sides turning the Strait of Hormuz into dangerous waters, supply concerns keep swirling. The energy crunch deep in a chronic phase but risks turning more acute with $100 a barrel prices back in sight.</p>

<p>While higher crude prices are a bonus for oil majors, it&rsquo;s a big headache for other industries, as the costs of keeping the light on, customers warm, and factories whirring becomes more onerous. They raise inflationary risks too, with the prospect of companies passing on the higher overheads as higher prices. Those hoping for relief from higher borrowing costs have been left sorely disappointed, with markets pricing in multiple hikes. The Bank of England is forecast to raise rates potentially three times over the next year, while the Fed is also expected to start another hiking cycle, especially after the strong jobs numbers which landed on Friday. Even if central bankers stay more cautious, and don&rsquo;t end up hiking, to this extent, the damage of predictions is already done, as market pricing of future moves influences everything from business loan rates to mortgage deals and government borrowing costs. The yield on 10-year gilts, is staying painfully elevated, ticking up higher to &pound;5.165, it means the government has to pay more to finance its debt pile, when it wants to raise more funds.</p>

<p>It&rsquo;s a highly awkward backdrop for John Healey, the Chancellor to make his big speech later on revitalising growth in the economy. Crushing energy bills, fractious geopolitics, tense trade relations and the high cost of borrowing mean he&rsquo;s walking a precarious tightrope. He&rsquo;ll want to convince bond investors that he&rsquo;s going to be prudent with the finances, and not lead to another bond market strop out, but at the same time is expected to show the government is serious about funding investment.</p>

<p>He&rsquo;s set to unveil a &pound;150 million fund for companies with high growth potential in the North of England. He&rsquo;s also expected to make a pitch about how sparking regional growth will be a key driver of the government's economic strategy, using state money to crowd in private capital, while handing city regions more power to decide where investment should go. It comes at a time when a regional growth spurt is clearly needed.  Although British tech appears to have had a renaissance this year in terms of raising capital, it&rsquo;s highly skewed to the London region. The British Business Bank has already invested more in the last nine months than in the previous four years. Total investment is expected to scale to over &pound;400m this year. It&rsquo;s helped open the door, to a surge of UK venture capital investment, which reached &pound;14.4 billion in the first half of 2026, with AI companies attracting the bulk of that, but the vast majority of them are based in the capital.</p>

<p>So, while the British tech scene remains highly promising and a source for future jobs, the regions are still set to struggle. The timing is particularly awkward given the fresh warning from Jaguar Land Rover. The carmaker has launched a voluntary redundancy programme as it targets around &pound;1.7bn of savings over the next two years, with up to 4,000 jobs potentially affected. JLR is being squeezed by falling sales, US tariffs, rising costs and increasingly fierce competition from cheaper Chinese manufacturers. While investment in tech firms is welcome, job creation will lag, just as Britian&rsquo;s industrial base in being battered by global competition.</p>

<p>It&rsquo;s also raising fresh questions about how a new social contract is needed to give younger workers a leg up and reduce the generous uprating terms of the state pension. The argument to scrap the triple lock is again hitting the headlines with the British Chambers of Commerce arguing for it to be abandoned to save billions of pounds.</p>

<p>The universal triple lock does give an especially strong protection to one age group at a time when younger generations face high rents, struggle to buy homes and have a heavier tax burden to support an ageing population.</p>

<p>But all this speculation is potentially harmful as people need certainty to plan for retirement. Whether you're 30, 40 or 50, you need to have some idea of what the State Pension will provide so you can work out how much you need to save privately. If the triple lock is clearly becoming unaffordable and needs reform, there is a strong argument for making those changes sooner rather than later, rather than leaving people in limbo. Constant speculation muddies the playing field and makes it harder for people to know how much they will actually need to put aside for their later years.&rsquo;&rsquo;</p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/oil-surges--borrowing-costs-rise-as-healey-faces-tough-test-27146.htm</link>
<pubDate>Mon, 7 Sep 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>A Question Of Surplus</title>
		<description><![CDATA[<p><strong>By Amber Patel, Consultant, LCP</strong></p>

<p>For trustees, the focus may often be on whether members should take a share of the surplus assets. For sponsors, the discussion may centre on how surplus can be used most effectively, whether through a refund, supporting another pension arrangement or wider business investment.</p>

<p>The Government's proposed changes to <a href="https://www.lcp.com/en/media-centre/press-releases/surplus-flexibility-regulations-welcome-but-simplification-and-clarity-needed-to-make-the-policy-as-effective-as-possible">DB surplus flexibilities</a> could widen the options available to schemes. One area that will become key is trustees and sponsors understanding what methods of surplus distribution have worked elsewhere and why.</p>

<p>Drawing on our experience of supporting 150+ schemes through the post-transaction phase, we looked at cases where surplus was ultimately distributed.</p>

<div><strong>Who benefitted from the surplus?</strong></div>

<div>Our analysis shows there is no one-size-fits-all approach. In around half of cases, the sponsor was the sole beneficiary of the surplus. Members were the sole beneficiary in 14% of cases, and 36% of the time the surplus was shared between both parties.</div>

<p>Where surplus is shared, it is most commonly (but not always) shared equally between members and the sponsor</p>

<p><img alt="" src="https://www.actuarialpost.co.uk/images/pic_LCPAmberPatel10709261.jpg" style="height:347px; width:600px" /></p>

<div><strong>How do sponsors distribute DB surplus?</strong></div>

<div>A refund to the sponsor was the single most common  outcome, accounting for 43% of cases. However, where sponsors had input, there were several other routes depending on their objectives and wider commitments.</div>

<p>Interestingly, we found that in nearly a quarter of cases, sponsors redirected the surplus back into another group pension arrangement, including DC or &ldquo;sister&rdquo; DB Schemes with the same or overlapping DB memberships.</p>

<p>This reflects the reality of many surplus discussions. Trustees and sponsors are often looking for an outcome that recognises the interests of multiple parties, rather than directing all of the value to a single one.  This can create opportunities to reach an outcome that works across a wider workforce, rather than viewing the surplus decision solely through the lens of the scheme being wound up.<strong><img alt="" src="https://www.actuarialpost.co.uk/images/pic_LCPAmberPatel20709261.jpg" style="height:461px; width:600px" /></strong></p>

<div><strong>How can members benefit from a DB surplus?</strong></div>

<div>Where surplus was used to improve members&rsquo; benefits, one-off uplifts were the most common approach, used in roughly two-thirds of the time. Other approaches included improving pension increase caps, using enhanced factors and selecting a more generous GMP equalisation method.</div>

<p>However, this doesn&rsquo;t mean that one-off uplifts are simply the Trustee&rsquo;s preferred choice. Practical considerations can be just as important as the principle behind sharing surplus. Trustees and sponsors should consider whether an enhancement can be:</p>

<div><em>accurately calculated;</em></div>

<div><em>clearly communicated to members;</em></div>

<div><em>administered without disproportionate cost or delay; and</em></div>

<div><em>accommodated by the insurer.</em></div>

<p>Insurer appetite and operational processes can have a significant influence on the options available. An attractive enhancement on paper may be less convincing if it is difficult to insure, creates additional data requirements or delays the transition to buyout and wind-up.</p>

<div><strong>What the Pension Schemes Act 2026 changes for surplus</strong></div>

<div>We expect that the additional flexibilities introduced in the <a href="https://www.lcp.com/en/pensions-benefits/uk-pension-schemes-act-2026">Pension Schemes Act 2026</a> may impact some of the choices made by Trustees. Different options may become available before and after scheme wind-up, so care will need to be taken over the process. We are beginning to see more schemes opt to complete additional analysis before triggering wind-up to navigate this, and to support discussions between trustees and sponsors early on.<strong><img alt="" src="https://www.actuarialpost.co.uk/images/pic_LCPAmberPatel30709261.jpg" style="height:297px; width:600px" /></strong></div>

<div><strong>What should Trustees and sponsors do now?</strong></div>

<div>A good starting point is to review the scheme rules and take advice early. In some schemes, the rules are clear about what must happen to any surplus and leave little room for choice. Other schemes give trustees more discretion. Where there is discretion, trustees and sponsors should agree the principles that will guide their discussions before they start negotiating the amounts involved.</div>

<p>Again, the changes introduced by the Pension Schemes Act 2026 may provide additional flexibility to alter restrictive scheme rules. However, it remains to be seen whether Trustees will view this as appropriate in many cases, and what the legal advice will support.</p>

<p>Over the past 12 months, we have seen several cases where surplus was materially higher than expected, or where a surplus emerged late in the process. This can happen for a range of reasons, including changes in market conditions, insurer pricing, any unexpected data issues, and the final terms of a transaction. A scheme that assumed only a modest surplus may therefore find itself facing a much more challenging decision further down the line. Having discussions on these potential issues early can help avoid delays and more difficult conversations later on.</p>

<p><strong>Questions to consider as part of these discussions could include:</strong></p>

<div><em>What is the purpose of any surplus?</em></div>

<div><em>What outcome would be fair to members and the sponsor?</em></div>

<div><em>Does the scheme&rsquo;s history matter? For example, past contributions or benefit changes?</em></div>

<div><em>How and why did the surplus arise?</em></div>

<div><em>Which options are workable once tax, legal, insurer and administration considerations are taken into account?</em></div>

<p>Proposed changes to the surplus rules could bring these conversations forward. If schemes have greater scope to access surplus before wind-up, trustees and sponsors may need to address it as part of their wider endgame planning, alongside funding, investment, member benefits and the sponsor&rsquo;s objectives.</p>

<p>The key is not to wait until the numbers are known. Agreeing the principles early gives trustees and sponsors a better chance of reaching an outcome that is fair, practical and able to stand up to scrutiny by both members and the Regulator.</p>

<p><strong>Key Takeaways</strong></p>

<div><em>Surplus can potentially be refunded back to the sponsor or used to enhance member benefits&hellip; or a combination of both.</em></div>

<div><em>Sponsors may choose to use the surplus in a variety of ways, including supporting another pension scheme.</em></div>

<div><em>Trustees and Sponsors should consider the proposed changes to surplus rules carefully, how they impact the options available and how it fits into their wider post-transaction timeframes</em></div>

<div><em>Trustees, lawyers and advisors need to be aware of the scheme rules, along with any additional flexibilities introduced by the changes in the Pension Schemes Act 2026.</em></div>

<div><em>When there is flexibility for surplus use, Trustees and Sponsors should think about the key principles early.</em></div>

<p> </p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/a-question-of-surplus-27149.htm</link>
<pubDate>Mon, 7 Sep 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Don  039 t Just Grow Your Pension  Help It Flourish </title>
		<description><![CDATA[<div><strong>According to the <a href="https://expertise.scottishwidows.co.uk/retirement-report/retirement-report-2026-saving-for-retirement/">2026 Scottish Widows Retirement Report:</a></strong></div>

<div> </div>

<div><em><strong>12.2 million people at risk:</strong> Almost a third (31%) of UK adults are on track to fall below even a minimum standard of living in later life.</em></div>

<div><em><strong>A three-way split:</strong> The UK population is divided almost equally: 31% face less-than-minimum standards, 30% are heading for a basic retirement and 30% are on target for a comfortable one.</em></div>

<div><em><strong>The self-employed gap:</strong> Over a third of part-time and self-employed workers risk falling short, compared with fewer than one in five full-time employees.</em></div>

<div> </div>

<div><strong>Robert Cochran, Pensions Expert at Scottish Widows, said: </strong>&ldquo;Nobody wins a giant vegetable competition by looking at their pumpkin once a year and hoping for the best. The growers who produce extraordinary results give their plants regular attention throughout the season. Retirement saving works much the same way. You don't need to make dramatic changes, but regularly checking in on your pension and taking small actions can make a surprisingly big difference over time.&rdquo;</div>

<div> </div>

<div>Robert shares five giant-growing secrets for a bigger pension:</div>

<div> </div>

<div><strong>Plant early</strong></div>

<div>Champion growers know that the earlier they start, the longer their vegetables have to grow. Pensions benefit from time too. Starting earlier gives contributions more opportunity to benefit from investment growth and compounding. Even relatively small sums paid in earlier can have a meaningful impact over the long term.</div>

<div> </div>

<div><strong>Feed growth regularly</strong></div>

<div>A prize-winning vegetable needs regular nourishment. For a pension, that means contributing consistently and reviewing what you pay in when your circumstances change. A pay rise, bonus or reduction in another expense can create an opportunity to add a little more. If your employer offers contribution matching above the standard level, check whether you are making full use of it.</div>

<div> </div>

<div><strong>Give it room to grow</strong></div>

<div>Giant growers concentrate resources on the crop they want to develop. In pension terms, that means understanding what you already have and avoiding forgotten savings. Use the Government&rsquo;s free Pension Tracing Service, alongside your CV or employment history, to identify schemes from previous jobs. Many providers also offer tracing support. The Scottish Widows app, for example, allows customers to trace old pensions and consider possible next steps.</div>

<div> </div>

<div><strong>Check the growing conditions</strong></div>

<div>Successful growers monitor the soil, weather and progress throughout the season. Pension saving also benefits from an occasional check-in. Download your pension provider&rsquo;s app, review your workplace and private pensions, and check your State Pension forecast. The HMRC app can show what you are currently on track to receive and when.</div>

<div> </div>

<div><strong>Know what you are growing towards</strong></div>

<div>Every giant grower has a target. For retirement, the aim is a lifestyle rather than a weigh-in. Pensions UK&rsquo;s Retirement Living Standards illustrate minimum, moderate and comfortable retirement lifestyles and their potential costs. Once you have a sense of the retirement you want, a retirement calculator can help you explore how contributions, investment growth or retirement age could affect the outcome.</div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/don--039-t-just-grow-your-pension--help-it-flourish--27145.htm</link>
<pubDate>Mon, 7 Sep 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Focus On Scale Should Be To Drive Better Outcomes</title>
		<description><![CDATA[<p>TPT supports the Government&rsquo;s objective of increasing scale in workplace pensions in principle but argues that the detailed framework must align with how assets are invested and governed in practice. Measures to increase scale will have to recognise existing scale, measure it consistently and avoid creating artificial distinctions or governance conflicts.</p>

<p>TPT believes the regime should support larger, better-governed investment pools without overriding sound investment design, excluding assets that already contribute to scale, or weakening the accountability of trustee boards. Ultimately, TPT believes that scale should support better outcomes, not become an end in itself. TPT&rsquo;s specifically calls for the regime to:</p>

<p><em><strong>Include all assets contributing to the same investment scale: </strong>TPT welcomes the proposed Common Investment Strategy (CIS) definition as an appropriate way of identifying where assets share the same investment strategy and decision-making framework. However, where assets satisfy both CIS and same-scheme (connected) criteria, including common governance and investment decision-making, government must not create further arbitrary distinctions based on scheme structure and policy exemption status.</em></p>

<p><em><strong>Avoid governance conflicts for connected schemes:</strong> The established common-control test is workable, but common ownership alone should not allow separate schemes to aggregate where independent trustee boards set different strategies. Any aggregation should reflect where strategic investment decisions are actually made and avoid creating conflicts between trustee responsibilities.</em></p>

<p><em><strong>Define MSDAs by substance: </strong>Technical or inadvertent defaults, and differences arising only from charges, administration or sectional structure, should not split what is effectively a single investment proposition. However, genuinely distinct investment strategies should continue to be recognised separately.</em></p>

<p><em><strong>Accommodate distinct ethical and belief-based defaults:</strong> Where a separate investment strategy is used to satisfy specific member and employer needs, smaller arrangements should be accommodated. The Government should provide greater clarity on what would qualify for this treatment, as forcing consolidation in these cases could move members out of an arrangement designed around those preferences without clear evidence that outcomes would improve.</em></p>

<p><strong>Ruari Grant, Head of Policy at TPT, said: </strong>&ldquo;We support the Government&rsquo;s objectives regarding scale in principle, but the framework needs to recognise where scale already exists in practice. Where assets are invested under the same strategy, governance and decision-making framework, their legal or sectional structure should not prevent them from counting towards any scale measurement.</p>

<p>&ldquo;Ultimately, scale should be a means to achieving better outcomes for members, rather than an end in itself. The rules therefore need to distinguish between artificial fragmentation and genuinely different investment propositions, while giving trustees sufficient flexibility to design strategies that effectively meet members&rsquo; needs.&rdquo;</p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/focus-on-scale-should-be-to-drive-better-outcomes-27147.htm</link>
<pubDate>Mon, 7 Sep 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Dashboard Programme Could Help Bereaved Families On Iht</title>
		<description><![CDATA[<p>According to the Pensions Policy Institute* there&rsquo;s an estimated &pound;31.1bn in unused pension pots, with almost &pound;10,000 in each pot. From 6 April 2027, Inheritance Tax (IHT) will be applied to any unused pension pots of those who have died. RSM UK says a joined-up approach is needed on IHT and the pensions dashboard launch, to enable grieving families meet their IHT and probate responsibilities.</p>

<p>The government expects the executor of the will to ensure the right amount of IHT is paid on any unused pensions pots within six months of a person&rsquo;s death. As most people hold several pensions over their lifetime, grieving families can find it difficult to identify all of these and ensure the correct IHT is paid within the six-month window.</p>

<p><strong>Andrew Aston, pensions audit director at RSM UK, said:</strong> &ldquo;Now is the ideal time for the government to apply some joined up thinking ahead of the pensions dashboard launch. Probate is already a complex and unwieldy process, which can create additional stress for families at an upsetting time. As IHT could be due on unused pension pots from April 2027, this adds yet more complexity. We&rsquo;d like to see the government build in the ability for executors of wills to see all unused pension pots via the dashboard. This could simplify the probate process, enabling grieving families to meet the deadline to pay inheritance tax within six months of a relative&rsquo;s death.&rdquo;</p>

<p>Those who miss the six-month window to pay inheritance tax will face interest charges from HMRC on the amount owed. On large pension pots, this can mount up to significant sums.<br />
 </p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/dashboard-programme-could-help-bereaved-families-on-iht-27148.htm</link>
<pubDate>Mon, 7 Sep 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Infectious Disease And What Covid19 Revealed In Insurability</title>
		<description><![CDATA[<div><strong>By Lucy StanbroughHead of Emerging Risk and H&eacute;l&egrave;ne Galy Managing Director, The Willis Research Network</strong></div>

<div> </div>

<div>What was less well understood was how a health emergency could propagate through systems, creating simultaneous operational, economic and insurance impacts across sectors and geographies. Shortly before the outbreak, it had also been shortlisted as a severe disruptor within our airport risk index project with Cambridge Centre for Risk Studies, a risk capable of halting operations across global transport networks. The emergence of COVID-19 did not introduce a new risk. It revealed how an infectious disease event could cascade through economic, operational and insurance systems.</div>

<div> </div>

<div>As the pandemic unfolded in 2020, the Willis Research Network also worked with , a specialist in infectious disease analytics, to deepen understanding of how outbreaks could spread and translate into organisational, economic and insurance impacts. This work reflected WRN&rsquo;s broader role: connecting scientific modelling with the practical challenge of resilience. It examined not only the infectious disease hazard, but also how climate change, urbanisation and growing connectivity could shape exposure and vulnerability, increasing the potential for zoonotic epidemics to develop into wider pandemics.</div>

<div> </div>

<div><strong>Pandemic as a systemic, interconnected disruptor</strong></div>

<div>COVID-19&rsquo;s impacts extended far beyond healthcare systems. The virus triggered a cascade of disruption across multiple domains:</div>

<div> </div>

<div><em>Passenger demand collapsed across aviation and travel</em></div>

<div><em>Supply chains stalled as production and logistics faltered</em></div>

<div><em>Workforces were constrained by illness, lockdowns and regulatory measures</em></div>

<div><em>Government intervention reshaped economic and loss dynamics</em></div>

<div> </div>

<div>These effects were not isolated. They occurred simultaneously across geographies and sectors, showing how a health event could become an economic shock, a financial stress and an operational disruption.</div>

<div> </div>

<div>This reflects a defining feature of pandemic risk: it is inherently systemic. A single trigger propagates through systems, creating correlated losses that unfold over time rather than as a single event. It also aligns with a core finding from the WTW Emerging and Interconnected Risks Survey: no risk operates in isolation, and impacts often arise from how risks combine and cascade. Formal assessments that treat risks as independent can underestimate the scale, speed and secondary effects of major shocks.</div>

<div> </div>

<div>For insurers, the significance of this systemic behaviour was not only the scale of disruption, but the way losses accumulated across portfolios  simultaneously and over an extended period. Traditional insurance relies on diversification: losses are expected to occur independently, allowing them to be managed across a portfolio. COVID-19 challenged this assumption. Instead of diversification, the industry faced global correlation: losses occurring everywhere at once, testing policy wordings and coverage assumptions. This created three core challenges for insurability:</div>

<div> </div>

<div><strong>01 Global synchronisation of losses</strong></div>

<div>Events that affect all regions simultaneously cannot be offset across portfolios.</div>

<div><strong>02 Complex loss drivers</strong></div>

<div>Losses were driven not only by the disease itself, but by policy decisions, behavioural responses and network effects.</div>

<div><strong>03 Scale beyond private capacity</strong></div>

<div>The economic impact exceeded what private insurance markets could absorb alone.</div>

<div> </div>

<div>These dynamics exposed significant protection gaps, particularly in business interruption, where many losses fell outside traditional coverage structures.</div>

<div> </div>

<div><strong>From foresight to sustained preparedness</strong></div>

<div>COVID-19 was not a failure of foresight. It was a failure to translate foresight into resilience. The pandemic exposed the gap between recognising a risk in theory and building the capabilities, partnerships and financial mechanisms needed to withstand it in practice.</div>

<div> </div>

<div>This same idea of national preparedness and resilience shaped WTW&rsquo;s involvement in the National Preparedness Commission, which emphasised whole-of-society approaches to crisis readiness. The lesson was that preparedness cannot sit with any single institution: it depends on stronger connections between government, business, science and civil society before crises unfold.</div>

<div> </div>

<div>Despite the scale of COVID-19, pandemic risk has already begun to fall down many organisational risk agendas as attention shifts towards technology, cyber and geopolitical risks. But this reflects changing attention, not changing likelihood. The underlying exposure remains, even as focus moves elsewhere.</div>

<div> </div>

<div>For pandemic risk, the implication is clear: preparedness is not a one-off exercise after a crisis, but a capability that has to be maintained after attention moves on. The key question is whether organisations and markets will sustain the memory, partnerships and practical tools needed to respond before focus shifts elsewhere.</div>

<div> </div>

<div><strong>From event to insight: the insurability frontier</strong></div>

<div>COVID-19 prompted a reassessment of how organisations approach emerging risk, particularly where risks are systemic and difficult to model using historical data alone. It reinforced the value of scenarios and storylines as practical tools for exploring uncertainty, testing assumptions and supporting decision-making.</div>

<div> </div>

<div>COVID-19 should not, however, become the new worst-case benchmark. Although globally disruptive, it did not combine the highest plausible levels of transmissibility and severity. A future outbreak could produce a more extreme tail-risk combination, with faster spread, greater mortality or morbidity, and deeper disruption to critical systems. Scenarios should test conditions beyond recent experience, rather than treating the last crisis as the outer limit of what is plausible.</div>

<div> </div>

<div>The implications also extend beyond infectious disease. Climate, cyber and supply chain risks share similar characteristics: losses across regions and business classes can be correlated, disruption can spread across systems and dependencies can amplify shocks. Each raises similar questions about diversification, modelling and scale. COVID-19 demonstrated how globally synchronised, long-duration disruption can challenge traditional assumptions about insurability.</div>

<div> </div>

<div><strong>Remembering what we learned</strong></div>

<div>The Willis Research Network was founded to bridge science and real-world risk management. COVID-19 reinforced the importance of that mission. It demonstrated three key takeaways for future resilience:</div>

<div> </div>

<div><em><strong>Keep foresight connected to action: </strong>identified risks need ownership, investment and preparedness plans. Even if that&rsquo;s a conscious decision to park a risk with well-defined reasons.</em></div>

<div><em><strong>Plan for correlation:</strong> pandemic risk showed how losses can accumulate across sectors, geographies and lines of business at the same time.</em></div>

<div><em><strong>Use scenarios to test resilience: </strong>storylines, scientific partnerships and stress testing can help organisations challenge assumptions, explore a broader range of consequences and better understand how systemic risks may evolve before the next crisis unfolds.</em></div>

<div> </div>

<div>Perhaps most importantly, it highlighted a recurring challenge: risks can fall from attention more quickly than they fall from reality. The next pandemic may not arrive as a surprise &mdash; but whether it is insurable may depend on which lessons endure, which uncertainties remain under scrutiny and whether leaders invest in finding the answers before the next crisis exposes the gaps.</div>

<div> </div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/infectious-disease-and-what-covid19-revealed-in-insurability-27144.htm</link>
<pubDate>Fri, 4 Sep 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>2 000  Private Sector Db Schemes To Survive The Next Decade</title>
		<description><![CDATA[<div><em>70% of respondents predicted that 2,000 or more schemes will survive the next decade, with over half (52%) of expecting between 2,000 and 2,500 schemes to remain in 2035.</em></div>

<div><em>Almost a third (31%) selected 2,500 schemes, making it the single most common answer.</em></div>

<div><em>Only 18% believed the market will shrink to 1,000 or fewer schemes.</em></div>

<div><em>Attendees were also asked what factors Trustees should consider when setting DB scheme strategy.</em></div>

<div><em>Just 3% said this should be limited to the security of past benefits.</em></div>

<div><em>Nearly a quarter (23%) said Trustees should also consider member experience, option terms and administration standards. A further 23% felt potential member upside, such as inflation cap removal and benefit uplifts, should also be considered.</em></div>

<div><em>The largest group, more than half (51%), supported the broadest approach considering security, member experience, potential member upside and the potential for sponsor refunds.</em></div>

<div> </div>

<div><strong>Maria Keen, Trustee Director, Independent Governance Group, who chaired the event, said: </strong>&ldquo;The SPP polling results highlight the scale of opportunity for the private sector DB market to evolve over the next decade. With 70% of attendees expecting at least 2,000 schemes to remain by 2035, the future is unlikely to be simply about consolidation and wind-up.</div>

<div> </div>

<div>Trustee strategy is becoming broader than security alone, with member experience, improved member outcomes and sponsor interests increasingly part of the conversation. The next decade will be about finding new ways for DB schemes to deliver better outcomes while adapting to changing market conditions.&rdquo;</div>

<div> </div>

<div>Further SPP conference events this month will cover topics including innovations in the DC market, the future of fiduciary duty and improving equity in pension outcomes. <a href="https://the-spp.co.uk/events/upcoming-events/">Details for each of these events are available here</a>: </div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/2-000--private-sector-db-schemes-to-survive-the-next-decade-27141.htm</link>
<pubDate>Fri, 4 Sep 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Prison For Directors Behind  70 Million Pension Fraud Scam</title>
		<description><![CDATA[<p><strong>Sarah Coles, head of personal finance at AJ Bell, comments: </strong>&ldquo;<a href="https://www.gov.uk/government/news/prison-for-directors-behind-70-million-investment-fraud">Three men are being sentenced for a &pound;70 million pension fraud scam</a>, which put significant slices of around 3,000 pension funds into worthless investments. It&rsquo;s a horrible reminder of how criminals can destroy people&rsquo;s retirement prospects, and why it&rsquo;s so important to protect ourselves from scammers.</p>

<p>&ldquo;The scheme worked by cold calling people and persuading them to have a &lsquo;pensions review&rsquo;. During the process, they were recommended to invest funds in a security called Ethical Forestry Ltd. Around 3,000 UK investors took money out of their pension funds and invested in what they thought was an environmentally sound forestry scheme in Costa Rica.</p>

<p>&ldquo;Unfortunately, while trees were planted, no money was set aside to manage or harvest them, so there could never have been a return. Instead, funds were used to pay for the lavish lifestyles of the company directors.</p>

<p>&ldquo;It&rsquo;s a variation on a worryingly common theme, where scammers offer high risk, unregulated investment opportunities, which often promise sky high returns over short periods of time. These will sometimes come with exorbitant fees and levels of risk that haven&rsquo;t been made clear to investors. The fact that they&rsquo;re not regulated by the FCA or protected by the Financial Services Compensation Scheme (FSCS), means you have little or no protection if things go wrong. In some cases, the investment doesn&rsquo;t exist, or will never pay out, and your money is used to line the pockets of criminals.</p>

<p><strong>Five signs of a pension scam</strong></p>

<p>&ldquo;This is why it&rsquo;s so important to do what you can to protect yourself from fraudsters and be aware of five signs of pension scams:</p>

<div><em><strong>Any call, text or email out of the blue offering a review of your pension.</strong> Increasingly, approaches come through social media too. Cold calling isn&rsquo;t permitted within pension regulations, so it should always ring alarm bells. As a general rule, if someone you don&rsquo;t know contacts you about your pension, don&rsquo;t engage with them.</em></div>

<div><em><strong>Anyone promising early access to your pension.</strong> This simply isn&rsquo;t possible within the rules, so is a sure-fire sign of a scam.</em></div>

<div><em><strong>Anyone promising huge, guaranteed investment returns &ndash; often over relatively short periods. </strong>Risk and reward just don&rsquo;t work like this: low risk tends to come with low returns, so this is simply too good to be true. The investments that scammers offer access to could include unusual things like forestry, but can look like relatively ordinary stock market investments too.</em></div>

<div><em><strong>Anyone not regulated by the FCA.</strong> At the heart of scams are often unregulated &lsquo;introducers&rsquo; selling unregulated investments. While there is nothing fundamentally wrong with investing in unregulated assets, there&rsquo;s a risk they are being vastly overhyped. Even where it&rsquo;s a real investment, if you&rsquo;re the victim of mis-selling you won&rsquo;t qualify for FSCS protection. If someone selling you a pension investment tells you they are regulated, don&rsquo;t take them at their word, because fraudsters will sometimes impersonate a real firm. Instead, break contact, use the FCA website to check the business is regulated, find a phone number on the official website, and approach them yourself.</em></div>

<div><em><strong>Anyone putting you under any pressure. </strong>This is a classic scam tactic, where you are told there&rsquo;s a deadline and that you need to act fast. Never allow anyone to put you under pressure like this. Take the time to investigate the company and the investment, talk to people you trust, and if you want help with your options or are unsure what to do, consider speaking to a regulated financial adviser or visit the government-backed retirement guidance service <a href="https://www.moneyhelper.org.uk/en/pensions-and-retirement/pension-wise">Pension Wise.</a></em></div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/prison-for-directors-behind--70-million-pension-fraud-scam-27143.htm</link>
<pubDate>Fri, 4 Sep 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Hymans Robertson Strengthens Cdc Leadership</title>
		<description><![CDATA[<p>She will work with clients to explore and implement CDC arrangements and other collective retirement savings. Alongside this, the firm&rsquo;s Senior Partner, Jon Hatchett has obtained a CDC Scheme Actuary Practising Certificate. This makes him one of a small number of actuaries in the UK qualified to act as CDC Scheme Actuary, further strengthening the leading pensions and financial services firm&rsquo;s Collective Defined Contribution (CDC) capabilities.</p>

<p>Lauren joined Hymans Robertson in 2020 as part of the firm&rsquo;s DB actuarial team and is a Senior Actuarial Consultant, advising a range of scheme trustees and sponsors. She has played a key role in developing the firm&rsquo;s CDC proposition, with strong thought leadership involvement and engagement with policymakers.</p>

<p><strong>Commenting on Lauren's appointment and the continued growth of Hymans Robertson's CDC practice, Jon Hatchett, Senior Partner and CDC Scheme Actuary at Hymans Robertson, said: </strong>&ldquo;CDC has the potential to become an important new form of pension provision for UK savers.  Lauren&rsquo;s skills, energy and expertise make her the right person to lead its development within our firm.</p>

<p>&ldquo;The next few years will be critical for the development of the UK CDC market.  It's exactly the right time for us to be investing in our CDC capabilities. Policymakers, providers and employers are increasingly focussed on how to deliver sustainable retirement incomes.  So, collective solutions are attracting significant interest. Our&rsquo; firm&rsquo;s purpose is to deliver better futures. With the retirement adequacy and gender pension gap challenges facing the DC only generations of pension savers, I&rsquo;m excited about the role Collective DC can play in improving these issues.</p>

<p>&ldquo;Lauren's appointment and my CDC Scheme Actuary Practising Certificate strengthen our ability to help clients navigate this rapidly developing market and take advantage of the opportunities it creates.&rdquo;</p>

<p><strong>Commenting on her promotion and new role, Lauren said: </strong>&ldquo;This is an exciting time for CDC pensions in the UK. After many years of policy development, the first multi-employer whole-of-life CDC schemes will start applying for authorisation over the next few months.  Work continues on the legislative framework required to enable retirement-only CDC arrangements.</p>

<p>&ldquo;CDC has the potential to transform retirement outcomes by allowing members to benefit from scale, longevity pooling and smoothing investment risk over time. By managing key retirement risks collectively, CDC can provide a more efficient means of generating sustainable retirement incomes than many individuals can achieve on their own.</p>

<p>&ldquo;I am enjoying working with our clients, supporting them as they navigate this evolving market, designing whole of life and retirement CDC schemes to meet the needs of UK pension savers them I&rsquo;m also looking forward to continuing to contribute to industry policy discussions and further developing our talented team of CDC specialists as demand for these solutions grows.&rdquo;</p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/hymans-robertson-strengthens-cdc-leadership-27136.htm</link>
<pubDate>Thu, 3 Sep 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Insuring An Income In Retirement</title>
		<description><![CDATA[<p><strong>By Dale Critchley, Workplace Policy Manager, Aviva</strong></p>

<p>When we reach retirement age the risk of dying remains, but for defined contribution pensioners, living longer, also comes into play.</p>

<p>I remember writing letters to retirees in the 1980&rsquo;s wishing those people taking their pension &ldquo;a long and happy retirement&rdquo;. It&rsquo;s what we all hope for. While I have been told that money doesn&rsquo;t buy happiness, an adequate pension income is something we all aim to receive. As for the length of retirement, there is a growing recognition that savers need to insure themselves against having a retirement that is too long and running out of money. Research by Aviva and Age UK recently highlighted that many people underestimate just how long retirement can last, and the financial impact that comes with it. Today's retirees can easily spend 20, 25 or even 30 years in retirement. That's a wonderful achievement, but it creates a challenge: how do you make sure your money lasts as long as you do?</p>

<p>In many ways retirement income solutions are another form of insurance, where a mixture of insurance, investment expertise and actuarial skill can mitigate the risk of quite literally living beyond our means.</p>

<p>The most obvious, and currently the only guaranteed solution, is of course an annuity. Longevity risk sharing and a guarantee underpinned by appropriate investments and provider backing ensures that an annuity will pay out a level of income for the whole of the annuitant&rsquo;s life. </p>

<p>The premium for this guarantee is the price of the annuity. This is increasing set based on detailed information about the customers health and lifestyle. The result is that consumers are more likely to get good value from their annuity, even if they are not in the best of health. </p>

<p>Underwriting is of course a common feature of any insurance, designed to ensure the cost of the insurance reflects the chance that that a risk will crystallise. If we are looking at the risk of outliving our pension pot, not everyone&rsquo;s risk will be the same, and so a single conversion rate of pension fund to pension income cannot be right either.</p>

<p>While an insurance company guarantee provides certainty, there is the option to simply spread the risk across a population large enough to allow for self-insurance. If we have representatives from across the whole population then we know what the average experience is likely to be, barring any great scientific breakthrough. If investment risk is managed, the insured risk can be absorbed by the group, through an acceptance that income could fluctuate, and there we have collective defined contribution.</p>

<p>The cost of this lower value promise might be less, but there are two premiums that are payable. The first is the potential loss of a payment to loved ones should someone die before they have obtained full value, cross subsidy seems to be inherent within CDC solutions, requiring an acceptance that the risk of outliving your income is greater than the risk of early death. As to whether this is true, we should maybe ask an underwriter, but it will not be true of everyone. </p>

<p>The second cost is that the pension must increase by at least the consumer price index (CPI). This means that savers must accept a lower initial level of income, as a cost of insuring against inflation. While this may make sense to some, for those who don&rsquo;t live as long, or those who might be more active in the early years of their retirement, a higher real terms income when they first retire might be preferable.  This might allow them to enjoy life more when they are healthier and more able.</p>

<p>Insurance can be great, it can ease worries over unforeseen circumstances, but when it comes to retirement we need to guard against a singular focus on the risk of a long retirement and balance it with the need for a happy one.                                                    </p>

<p>                                                   </p>

<p> </p>

<p> </p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/insuring-an-income-in-retirement-27137.htm</link>
<pubDate>Thu, 3 Sep 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Savers Want Best Returns Wherever Their Pension Is Invested</title>
		<description><![CDATA[<p>The results come as the Government has built on the Mansion House Accord, with mandation powers now written into the Pension Schemes Act 2026 granting it a restricted reserve power to require workplace defined contribution pension funds to invest more in the UK. There is now greater pressure on those pension schemes, to increase their domestic allocations.</p>

<p>However, PensionBee&rsquo;s surveys of customers in its Global Leaders Plan (PensionBee&rsquo;s &lsquo;default&rsquo; fund for the under 50s) and 4Plus Plan (the default for those over 50) suggest many savers are unconvinced by the case for home bias, if it comes at the expense of returns.</p>

<p>Savers were told that the UK currently makes up around 3% of global stock markets, a weighting mirrored in PensionBee's all-equities Global Leaders Plan, and asked which statement came closest to their own view on UK investment. In response, 61% said they simply want the best returns, wherever in the world that is. A little over a fifth (21%) said they would support more UK investment, while only 16% had no strong view.</p>

<p>Among those who do back more UK investment, their support comes with conditions. Of those savers, more than half (52%) said they would only support it if it didn't reduce their returns, and 31% would need a better tax incentive. Only 16% of those who were broadly positive about investing in the UK said they'd support more investment at home, even if it meant lower returns.</p>

<p>On stewardship, savers ranked ending child and forced labour (47%) and paying real living wages (38%) as the issues that matter most to them, ahead of companies using fair tax practices (27%) and reducing greenhouse gas emissions (26%).</p>

<p>The survey also points to strong support for PensionBee's global approach more broadly. Over eight in ten (84%) respondents across both plans said they are satisfied or very satisfied with the plans that they are invested in, against just 3% who are dissatisfied.</p>

<p><strong>Key findings at a glance:</strong></p>

<div><em>61% of savers in PensionBee&rsquo;s default funds want the best returns wherever in the world that is, versus 21% who'd support more UK investment.</em></div>

<div><em>Of those open to more UK investment, 52% said they would only be in support if it didn't reduce their returns, and 31% suggested they would support it only with a better tax incentive.</em></div>

<div><em>Savers' top stewardship priorities include ending child and forced labour (47%) and paying real living wages (38%).</em></div>

<div><em>Across both defaults (Global Leaders Plan and 4Plus Plan), 84% of savers said they were satisfied or very satisfied with PensionBee&rsquo;s global approach.</em></div>

<p><strong>Clare Reilly, Chief Investment Solutions Officer at PensionBee, said:</strong> &ldquo;Our job is to seek the best returns for our default customers, wherever in the world they're found, which is why 84% of survey respondents told us they're happy with our global approach to growing their retirement savings. Our survey found little appetite for a greater UK tilt. And even among the minority who wanted one, most said they wouldn't accept it if it meant lower returns.</p>

<p>&ldquo;If savers are telling us that they don't want their retirement pots steered towards the UK unless it leaves them better off, then these insights may give the Government pause for thought. Without a clear returns rationale or other tax incentives to sweeten the deal for savers in the workplace, then they are asking ordinary savers to shoulder the long term consequences of decisions made for them, not by them.&rdquo;</p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/savers-want-best-returns-wherever-their-pension-is-invested-27135.htm</link>
<pubDate>Thu, 3 Sep 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Fca Bans And Fines Daniel Thomas For Pension Transfer Advice</title>
		<description><![CDATA[<p>The Financial Conduct Authority (FCA) has decided to ban Daniel Thomas from working in financial services and fine him &pound;742,700 after finding he recklessly gave defined benefit pension transfer advice he was neither qualified nor allowed to give.  </p>

<p>Mr Thomas was a director and financial adviser at DPT Financial Solutions Limited. Over 5 years Mr Thomas advised 53 clients about 63 transfers out of defined benefit pension schemes and is believed to have earned more than &pound;173,000 in fees. </p>

<p>Mr Thomas repeatedly misled clients and pension providers about his professional qualifications, destroyed client records and failed to co-operate with the FCA's investigation.  </p>

<p>Mr Thomas&rsquo; firm was an appointed representative. This meant another firm (known as a principal) had responsibility for overseeing its actions. Mr Thomas provided misleading information to his principal firm about his involvement in the pension transfer cases.  </p>

<p>It is not normally in consumers&rsquo; best interests to transfer out of defined benefit pensions because they provide valuable, guaranteed benefits which increase annually. That is why only those advisers with specialist qualifications and the correct permissions can advise people on whether to transfer out. </p>

<p><strong>Therese Chambers, executive director of enforcement and market oversight at the FCA, said: &quot;</strong>When you advise someone on their pension, you hold their future in your hands. Mr Thomas recklessly betrayed that responsibility. We will not stop acting against those ignoring our rules and unfairly putting people and their hard-earned money at risk.&rdquo; </p>

<p> </p>

<div><em><a href="https://www.fca.org.uk/publication/decision-notices/daniel-philip-thomas-2026.pdf">Decision Notice: Daniel Philip Thomas</a> </em></div>

<div><em>DPT Financial Solutions Limited was an appointed representative of Quilter Financial Services Ltd (the principal firm). An appointed representative is a firm or person who carries on a regulated activity on behalf, and under the responsibility of, a firm authorised by the FCA. The FCA has made no findings against Quilter in connection with this matter.</em></div>

<div><em>Defined benefit pension schemes provide valuable, guaranteed retirement income that cannot be replicated by other investments, in most cases, the FCA expects consumers to remain in these schemes. Advice on transfers must be provided, or checked, by a qualified Pension Transfer Specialist. Mr Thomas did not hold the qualifications required to perform this role.</em></div>

<div><em>In 2021, the FCA confirmed measures to improve the defined benefit pension transfer market. Read the finalised guidance.</em></div>

<div><em>See the <a href="https://www.fca.org.uk/consumers/pension-transfer-defined-benefit/advice-checker">FCA&rsquo;s defined benefit pension transfer advice checker</a> to check if you received poor transfer advice.The FCA has the power to impose financial penalties under section 66 of the Financial Services and Markets Act 2000 and to prohibit individuals under section 56 of that Act. </em></div>

<div><em>Information for customers wishing to make a complaint to Quilter. </em></div>

<div><em>Information for customers wishing to make a complaint to the Financial Ombudsman Service.</em></div>

<div><em>Some of Mr Thomas&rsquo; clients were members of the British Steel Pension Scheme and were in a particularly vulnerable position when he was advising them. The FCA has previously taken enforcement action against a wide range of firms and individuals for misconduct involving advice given to consumers to transfer out of the British Steel Pension Scheme. </em></div>

<div><em>In addition to fining him &pound;173,000 (plus interest), the penalty imposed includes an amount to reflect the seriousness of the misconduct, which is based on a percentage of Mr Thomas&rsquo; relevant income from DPT Financial Solutions Limited during the period connected to the breach. It also includes an uplift for failing to cooperate with the FCA&rsquo;s investigation. The full calculation is set out at paragraph 6 of the Decision Notice.</em></div>

<div><em>Find out more information about the FCA.</em></div>

<div><em>Find out more information about the Upper Tribunal (Tax and Chancery Chambers).</em></div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/fca-bans-and-fines-daniel-thomas-for-pension-transfer-advice-27138.htm</link>
<pubDate>Thu, 3 Sep 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Charity Db Schemes Must Prioritise Endgame Decisions</title>
		<description><![CDATA[<div>The report: <a href="https://www.actuarialpost.co.uk/downloads/cat_1/Hymans-2026-outlook-for-charity-db-pension-funding.pdf">2026 Outlook for charity DB pension funding</a>, shows that the largest 40 charities in England & Wales that sponsor DB pensions schemes now have combined DB pensions schemes reserves worth &pound;47bn. The analysis also shows there&rsquo;s been a 5% rise in average funding level of these charity DB schemes since 2025 and a rise of 25% since 2019.</div>

<div> </div>

<div>The 2026 report from the leading pensions and financial services consultancy assesses the charities&rsquo; DB pension&rsquo;s exposures by looking at reserve levels, income, DB funding levels and DB pension contributions over the last 8 years. It reveals that pension schemes are entering a period of significant change, and that all schemes should be actively considering endgame options.</div>

<div> </div>

<div>The report reveals that the changes charity DB schemes will be facing are driven by improved funding levels, as well as evolving regulation and increasing innovation in endgame options.  There are now three broad endgame routes now available to charity DB schemes: traditional insurance solutions, run-on strategies and alternative endgame solutions. Trustees need to decide what is best for their scheme and will provide the best outcomes for members. The increase in funding levels has come from a combination of falling liabilities and relatively resilient asset values. Total charity income from fundraising and charitable activities now sits at &pound;15bn; restricted income fell to &pound;4bn and unrestricted remained at &pound;11bn. </div>

<div> </div>

<div><strong>Commenting on why all charity DB schemes should be considering their endgame options, Heather Allingham, Partner and Head of DB Pensions Consulting for Charities, says: </strong>&ldquo;All charity DB schemes, regardless of their funding position,, should be actively considering their endgame options. Improved funding levels mean many schemes now have more choice - buy-out is no longer the only path to achieving long-term security. Charities should focus on articulating their objectives for their schemes and their members and exploring the full range of solutions available, from traditional insurance through to run-on strategies, superfunds and other innovative models.</div>

<div> </div>

<div>&ldquo;Different endgame options deliver different outcomes for members and sponsors, so the key is understanding which approach best aligns with a charity&rsquo;s objectives. All these options should be considered through a fresh lens and understanding how you could implement them for your scheme.</div>

<div> </div>

<div>&ldquo;Now is the time,  when charities need to connect funding, investment, legal risk and covenant in one joined-up plan. Better funding is welcome, but it does not remove the need for careful governance. Trustees and sponsors should test whether their investment strategy still fits their long-term objective and make sure their data and benefit records are ready or a plan is in place to address them. Schemes that act early will have more flexibility, more negotiating power and a better chance of securing the best outcome for members and the charity.&rdquo;</div>

<p> </p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/charity-db-schemes-must-prioritise-endgame-decisions-27139.htm</link>
<pubDate>Thu, 3 Sep 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Early Planning Key As Db Surplus Choices Become More Complex</title>
		<description><![CDATA[<div><strong>Key findings from the analysis include:</strong></div>

<div><em>In around half of cases, the sponsor was the sole beneficiary of the surplus. Members were the sole beneficiary in 14% of cases, while surplus was shared between members and sponsors in 36% of cases.</em></div>

<div> </div>

<div><em>A refund to the sponsor was the most common individual outcome, accounting for 43% of cases. However, other options were sometimes used, such as redirecting surplus into another group pension arrangement, whether a defined contribution (DC) scheme or a sister DB scheme.</em></div>

<div> </div>

<div><em>Increasingly, Trustees and sponsors are looking to have conversations about surplus early, particularly in light of the new options available from the Pension Schemes Act 2026.</em></div>

<div> </div>

<div><strong>Amber Patel, Consultant at LCP, commented: </strong>&ldquo;The key is not to wait until the numbers are known. Agreeing the principles early gives trustees and sponsors a better chance of reaching an outcome that is fair, practical and able to stand up to scrutiny from both members and the Regulator.&rdquo;</div>

<div> </div>

<div><strong>Kenneth Hardman, Partner at LCP, added:</strong> &ldquo;We expect that the additional flexibilities introduced in the Pension Schemes Act 2026 may affect some of the choices available to trustees. Different options may be available before and after scheme wind-up, so care will be needed over both the process and timing.</div>

<div>We are beginning to see more schemes undertake additional analysis before triggering wind-up, helping trustees and sponsors navigate these issues and begin discussions at an earlier stage.&rdquo;</div>

<p> </p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/early-planning-key-as-db-surplus-choices-become-more-complex-27140.htm</link>
<pubDate>Thu, 3 Sep 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>September 2026 Edition Of The Actuarial Post Magazine</title>
		<description><![CDATA[<p><a href="https://library.myebook.com/ActuarialPost/actuarial-post-september-2026/6763/#page/1"><img alt="" src="https://www.actuarialpost.co.uk/images/pic_APMagazineSEPTEMBER2026.jpg" style="float:right; height:277px; width:199px" /></a>With the school holidays coming to a close and parents up and down the country breathing a sigh of relief it seems that other events are also coming to a close from last month; the heatwave and connected wildfires; Andy Burnham&rsquo;s first month in power in which he among others; established an AI task force headed up by Lord Vallance; scrapped VAT on electricity; decentralisation and No 10 North perhaps being the eye catching move. And of course, the seemingly never-ending Iran war and Strait of Hormuz crisis. </p>

<p> </p>

<div><a href="https://library.myebook.com/ActuarialPost/actuarial-post-september-2026/6763/#page/6">News</a></div>

<div><a href="https://library.myebook.com/ActuarialPost/actuarial-post-september-2026/6763/#page/8">Movers & Shakers</a><br />
<a href="https://library.myebook.com/ActuarialPost/actuarial-post-september-2026/6763/#page/8">City Dealings</a></div>

<div><a href="https://library.myebook.com/ActuarialPost/actuarial-post-september-2026/6763/#page/10">Redefining Health Insurance Through Smarter Innovation and Analytics by Lisa Balboa, Snr Dir, ICT and Jessica Plewes, Snr Dir, ICT, WTW</a></div>

<div><a href="https://library.myebook.com/ActuarialPost/actuarial-post-september-2026/6763/#page/12">Clear Information Isn't Enough: Pension Savers Need More Support in Retirement by Dale Critchley, Aviva</a></div>

<div><a href="https://library.myebook.com/ActuarialPost/actuarial-post-september-2026/6763/#page/12">Stars of the Future sponsored by Star Actuarial Futures - Nominate Now!</a></div>

<div><a href="https://library.myebook.com/ActuarialPost/actuarial-post-september-2026/6763/#page/14">Soft Markets, AI and the Next Steps for Evolving London Market Pricing by Charl Cronje, Partner LCP</a></div>

<div><a href="https://library.myebook.com/ActuarialPost/actuarial-post-september-2026/6763/#page/16">Flood Risk in a Changing Climate: What Risk Managers Need to Know by Neil Gunn, Head of Flood & Water Mgmnt Research, WRN and Hayley Fowler professor Climate Change Impacts, Newcastle Uni.</a></div>

<div><a href="https://library.myebook.com/ActuarialPost/actuarial-post-september-2026/6763/#page/18">Retirement Puzzle by Alex White from Gallagher</a></div>

<div><a href="https://library.myebook.com/ActuarialPost/actuarial-post-september-2026/6763/#page/20">Lights, Camera, Actuary! by Claire Chowne from Bolton Associates</a></div>

<div><a href="https://library.myebook.com/ActuarialPost/actuarial-post-september-2026/6763/#page/22">Information Exchange by Tom Lawrie-Fussey, Ass VP of Insurance Product Mgmnt, LexisNexis Risk Solutions</a><br />
<a href="https://library.myebook.com/ActuarialPost/actuarial-post-september-2026/6763/#page/24">Recruitment</a></div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/september-2026-edition-of-the-actuarial-post-magazine-27134.htm</link>
<pubDate>Wed, 2 Sep 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Db Trustees Report 34  Average Rise In Scheme Running Costs</title>
		<description><![CDATA[<p>New research from TPT Retirement Solutions indicates that defined benefit (DB) trustees continue to face significant cost pressures, with the scale of reported cost increases varying across schemes.</p>

<p>Trustees reported an average increase of 34% in running costs over the past 12 months, with the findings published in the second Insight Report from the TPT Retirement Solutions: DB Trustee Pulse 2026*. This year&rsquo;s findings remain relatively consistent with the 2024 iteration of the research, when responding trustees reported average cost inflation of 37%, indicating that cost pressures remain a significant issue for many UK DB schemes.</p>

<p>Legal services were identified by 37% of trustees as the area seeing the largest absolute cost increase, followed by technology and data services (34%). However, analysis of the findings suggests that cost pressures facing schemes are broad-based as opposed to being driven by one dominant factor: governance and administration services were both cited by 28% of trustees, while major project undertakings such as GMP equalisation or Pensions Dashboard preparation, alongside covenant services, (also both 27%) all ranked close behind.</p>

<p><strong>Cost pressures diverge with larger schemes reporting the steepest rises</strong></p>

<p><img alt="" src="https://www.actuarialpost.co.uk/images/pic_TPTDB0209261.png" style="height:266px; width:585px" /></p>

<p>Trustees across both scheme-size groups reported rising costs, with the largest increases more commonly reported by trustees overseeing larger schemes (see Graph 1).</p>

<p>The research showed that almost half (44%) of trustees overseeing schemes with &pound;1bn or more in assets reported running cost increases of more than 50% over the past year, compared with just 7% of those overseeing schemes below that threshold.</p>

<p>The divergence was even more pronounced at the upper end of the range: none of the trustees overseeing schemes below &pound;1bn in assets reported cost increases of over 76%, compared with almost one in five (18%) trustees managing schemes with assets above that threshold.</p>

<p><strong>Jonathan Jackaman, Head of Client Relations at TPT Retirement Solutions said:</strong> &ldquo;Rising scheme costs are no longer simply a budgetary concern but instead, are becoming a strategic challenge for trustee boards to navigate. Trustees are spending more on the building blocks of good governance, from legal support and administration to data and governance itself. And the data suggests that size alone does not insulate schemes from these pressures, with the steepest increases being reported among the larger schemes that responded.</p>

<p>&ldquo;For some trustee boards, consolidation can be one way to manage that complexity more efficiently working to reduce duplication, improve cost certainty and provide access to specialist capabilities at scale. The aim is not simply to cut costs, but to ensure trustee time and scheme resources are focused where they can have the greatest impact on long-term strategy in order to improve outcomes and continue delivering for members.&rdquo;</p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/db-trustees-report-34--average-rise-in-scheme-running-costs-27131.htm</link>
<pubDate>Wed, 2 Sep 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>760 000 Matured Child Trust Funds Remain Unclaimed</title>
		<description><![CDATA[<p>Figures from HMRC show that 760,000 matured Child Trust Funds, worth an average of &pound;2,000 each, remain unclaimed. That means hundreds of thousands of young people could be missing out on money that could go towards new laptops, textbooks, rent deposits or the everyday costs of student life &ndash; or setting them up with savings for their future.</p>

<p>Some companies, including those advertising on social media, are offering to 'find' and claim Child Trust Funds on people's behalf &ndash; often for a hefty fee or a cut of the final payout. The FCA has seen cases where customers were charged &pound;400 to locate the account and even seen some firms charging a monthly subscription for a one-off tracing service. But missing funds can be traced for free without losing a penny to a middleman.  </p>

<p><strong>Chris Knight, director of insurance at the FCA, said: </strong>&quot;A Child Trust Fund can be a welcome source of extra cash at a time when many young people need it most. But you don't need to pay someone else to claim what's rightfully yours &ndash; tracing and accessing your own Child Trust Fund costs nothing, so think twice about handing over a chunk of your savings to a claims firm for a job you can do yourself.&quot;</p>

<p><strong>Myrtle Lloyd, HMRC&rsquo;s chief customer officer said: </strong>&quot;If you&rsquo;re between 15 and 24, you could be sitting on a savings payout and not even realise it. Just search 'find my Child Trust Fund' on GOV.UK to find your savings account today.&quot;</p>

<div><strong>How to check if you have a Child Trust Fund</strong></div>

<div>Anyone aged 18 or over who was born between 1 September 2002 and 2 January 2011 could have a Child Trust Fund that they can access. Checking is straightforward and free:</div>

<div> </div>

<div><em>If you know which provider holds your Child Trust Fund, you can contact them directly to arrange withdrawal or transfer.</em></div>

<div><em>If you're not sure where your account is held, you can use <a href="https://www.gov.uk/child-trust-funds/find-a-child-trust-fund">HMRC's free online tracing tool</a> on GOV.UK to find out.</em></div>

<div><em>You'll need to prove your identity to the provider, but there is no cost involved.</em></div>

<p>Tracing a Child Trust Fund might be offered by firms who are regulated by the FCA, for example as claims management companies. But the tracing service itself is not an activity that generally needs FCA authorisation. This means firms offering this service may not be covered by the FCA&rsquo;s cap on claims management fees and customers may not be able to take complaints to the Financial Ombudsman Service.</p>

<p>FCA review</p>

<p>The FCA is also launching a review into Child Trust Funds. This will look at issues including cases where young adults cannot be contacted when they turn 18 and risk losing touch with their savings altogether. It will also look at how firms are ensuring Child Trust Fund customers receive fair value under the Consumer Duty, and whether there are barriers to vulnerable young adults accessing their money. This will report next year.</p>

<div><em>Child Trust Funds were available to children born between 1 September 2002 and 2 January 2011, with the scheme now closed to new applicants.</em></div>

<div><em>Around 6.3m accounts were opened.Existing accounts will continue to mature until 2029, with young adults able to access them once they reach 18.</em></div>

<div><em>Young adults can trace a lost Child Trust Fund for free using <a href="https://www.gov.uk/child-trust-funds/find-a-child-trust-fund">HMRC's online tool at GOV.UK.</a></em></div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/760-000-matured-child-trust-funds-remain-unclaimed-27132.htm</link>
<pubDate>Wed, 2 Sep 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Retirement Blind Spots Risk Savers Being Short At Retirement</title>
		<description><![CDATA[<p>More than a third (34%) of workers over 50 have not yet decided on how they will access their pension savings as they approach retirement, according to Scottish Widows&rsquo; latest Retirement Report. </p>

<p>While 46% of those still working expect to take their tax-free cash as soon they can, in reality 64% did this. This gap shows how priorities can change as retirement moves from a future plan to something more immediate. </p>

<p>Before retirement, 27% of workers expect to keep most of their pension invested and take a regular income, while 20% plan to buy an annuity. However, 28% of retirees actually choose an annuity, highlighting the appeal of a guaranteed income for life. </p>

<div><strong>A critical decision point</strong></div>

<div>Reaching the milestone age of 55* &ndash; when most savers can begin accessing their pension - opens the door to a range of complex decisions about how to take their money, understand how much tax they may have to pay and create an income that will last throughout retirement.</div>

<p>The research shows that four in 10 (41%) over-50s who are still working have little or no understanding of the different ways they can access their pension savings in retirement. Only a quarter (25%) feel confident they know all the main options available to them.</p>

<p>The gap is even more pronounced among women. Nearly half (46%) of women over 50 who have not yet retired say they have little or no knowledge of their retirement options, compared with just over a third (35%) of men.</p>

<div><strong>Leaving it too late</strong></div>

<div>The good news is that most people recognise the value of advice and guidance. More than four in five (81%) over-50s agree it is important to seek support before accessing their pension.</div>

<p>The challenge is timing. Almost a fifth (19%) plan to seek advice only in the year they retire, leaving limited time to consider their options and put a plan in place. A further 15% do not know when they will seek help, while just 8% do not expect to seek advice or guidance at all.</p>

<p>Leaving decisions until the last minute increases the risk of unintended consequences, from larger-than-expected tax bills to lower income later in retirement.</p>

<div><strong>Technology can help close the gap</strong></div>

<div>As the industry looks for ways to engage people earlier and make retirement planning simpler, technology has an important role to play.</div>

<p>Insight from Scottish Widows shows that people are open to new forms of support, with 42% saying they would use AI tools to help explain complex pension terminology and translate industry jargon into plain English.</p>

<p>By making retirement choices easier to understand and encouraging earlier engagement, technology has the potential to help more people make informed decisions and achieve better outcomes in later life.</p>

<p><strong>Carolyn Jones, Retirement Director, Scottish Widows commented:</strong> &ldquo;Turning 55 opens the door to pension savings built up over a lifetime, but while access to that money brings opportunity, it also brings important decisions that can shape retirement for decades to come.</p>

<p>&ldquo;That's why we need to bring the conversation forward. Too many people only fully engage in their retirement planning when they approach the point of taking action. By then, valuable opportunities to plan, prepare and make informed choices may already have been missed.</p>

<p>&ldquo;The industry is making progress. Targeted support, guided retirement journeys, digital advice and workplace education are all helping people navigate increasingly complex decisions. But we need to go further.</p>

<p>&ldquo;Our rallying cry is simple -  engage earlier, understand your options and seek advice sooner. And, as an industry, we have a shared responsibility to give every customer the knowledge and support they need. For example, Scottish Widows&rsquo; app helps customers better understand what they have in terms of pension savings, track lost pots and decide what to do with them in just three simple steps. The earlier people think about their income needs, the more choices and confidence they have to achieve the lifestyle they want.&rdquo;</p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/retirement-blind-spots-risk-savers-being-short-at-retirement-27133.htm</link>
<pubDate>Wed, 2 Sep 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>L g Secure  1 65bn Buyin For The Wood Pension Scheme</title>
		<description><![CDATA[<div>For this transaction, member experience was a decisive factor in the Trustee&rsquo;s insurer selection process, with L&G&rsquo;s in-house administration and customer service teams proving a key differentiator. By supporting members directly through its UK-based teams, L&G delivers continuity of service and long-term support throughout retirement.</div>

<div> </div>

<div>The transaction reflects a wider shift in the PRT market, with trustees placing increasing weight not only on price and execution certainty, but also on the quality of member experience after a transaction completes. Recent research commissioned by L&G found that, outside of price, insurer financial strength and member experience were the dominant priorities for trustees, together accounting for almost 90% of first-choice rankings.</div>

<div> </div>

<div>LCP acted as lead transaction adviser. The Trustee was advised by Gowling WLG, Wood Group was advised by Pinsent Masons and L&G was advised by CMS.</div>

<div> </div>

<div><strong>Gareth Mee, CEO, Institutional Retirement, L&G, said: </strong>&ldquo;Working closely with the Trustee, sponsor and LCP, we were able to deliver our shared goal of securing members&rsquo; benefits and ensuring they are well supported over the long term. The importance placed on member experience and cultural alignment speaks directly to what L&G&rsquo;s Institutional Retirement business has built over the last four decades: deep PRT expertise, a trusted brand and the experience needed to support customers well beyond the point of transaction. As the market continues to grow, our focus remains on using our scale and capabilities selectively to support high-quality transactions that deliver lasting value for schemes and their members.&rdquo;</div>

<div> </div>

<div><strong>Elaine Hanna, Head of Global Retirement, Wood Group, said: </strong>&quot;The completion of this buy-in is an important step in securing the long-term future of the Wood Pension Plan. It provides greater certainty for our members while significantly reducing pension risk for Wood. Throughout the process, we have worked closely with the Trustee, supported by our advisers and L&G, with a shared focus on achieving a positive long-term outcome for members. We're grateful for the collaboration and commitment that has helped make this possible.&quot;</div>

<div> </div>

<div><strong>Mervyn Walker, Chair of Wood Pensions Trustee, said:</strong> &ldquo;We are delighted to have completed a buy-in with L&G after a thorough and competitive process. The buy-in is a significant milestone for the Wood Pension Plan in reducing risk and improving further the security of our members&rsquo; benefits. The Trustee&rsquo;s objectives in approaching the market were to secure excellent value for money and to ensure that the outstanding service we provide to members through the Wood Pensions team would continue into the long-term future. In L&G, we are confident that we have selected a partner that fully meets our objectives, while also sharing our values and commitment to member service and experience.&rdquo;</div>

<div> </div>

<div><strong>Clive Wellsteed, Partner and lead transaction adviser, LCP, said:</strong> &ldquo;This transaction demonstrates the value of a well-prepared and carefully managed process. We worked closely with the Trustee and Wood to present the Plan clearly and compellingly to the market. This drove strong insurer engagement and competition on price, alongside tailored solutions to address the non-price features that mattered most to the Trustee and members. From a strong final round, L&G&rsquo;s proposal stood out for the way it met the Plan&rsquo;s specific requirements and the wider objectives of the Trustee and sponsor.&rdquo;</div>

<div> </div>

<div>As one of the UK&rsquo;s largest PRT providers, with a long track record across transactions of all sizes, L&G is able to take a disciplined and selective approach to the market. L&G focuses on opportunities where its scale, asset origination capabilities and customer service model can deliver strong outcomes for schemes, sponsors and members, while seeking to optimise value over the full lifetime of each deal.</div>

<div> </div>

<div> </div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/l-g-secure--1-65bn-buyin-for-the-wood-pension-scheme-27125.htm</link>
<pubDate>Tue, 1 Sep 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Planning To Make Your Holiday Permanent  </title>
		<description><![CDATA[<p><strong>By Emma Furlonger, Managing Director for Workplace Pensions at Standard Life</strong></p>

<p>For example, people living in countries such as Australia, Canada and New Zealand do not currently receive annual increases and instead have their State Pension frozen at the rate they first receive.</p>

<div><strong>The cost of a State Pension freeze</strong></div>

<div>The impact of frozen payments can build significantly over time. For example, someone receiving the full new State Pension of &pound;179.60 a week in 2021/22 who moved to a country where their pension was frozen at that level would still receive just &pound;9,339.20 a year today. By comparison, someone entitled to annual increases would now receive &pound;241.30 a week, or &pound;12,547.60 a year &ndash; a difference of more than &pound;3,200 annually. Compared to people entitled to the full new State Pension and receiving all annual upratings awarded between 2022/23 and 2026/27, that is more than &pound;9,500 in missed out on State Pension income during that time period.</div>

<p><img alt="" src="https://www.actuarialpost.co.uk/images/pic_StandardLifePerm0109261.png" style="height:157px; width:600px" /></p>

<p><strong>Emma Furlonger, Managing Director for Workplace Pensions at Standard Life, said:</strong> &quot;Returning home after a good summer holiday can make the idea of living abroad particularly appealing, and for some people that dream will eventually become reality. However, one thing many people don't realise is that where you choose to live can have a direct impact on your retirement income. While your UK State Pension can still be paid overseas, people living in certain countries won't receive future annual increases. Over a long retirement, missing out on those increases could make a significant difference to your income.</p>

<p>&quot;Private pensions also bring their own considerations, from whether you can continue contributing to how you access your savings and the tax you may pay. Understanding the rules before you move can help avoid unexpected surprises later.&quot;</p>

<p><strong>Emma Furlonger shares six key pension considerations for those thinking about moving abroad:</strong></p>

<div><strong>1. What will happen to my UK pension plan if I move abroad?</strong></div>

<div>&quot;Your UK workplace and private pension plans won't automatically move overseas with you. Unless you arrange a transfer, they will normally remain with your existing UK providers. You can still access your pension savings while living abroad once you meet the relevant age and your scheme's conditions. The normal minimum pension age is currently 55 and will rise to 57 from April 2028, although some people may be able to access their pension earlier depending on their circumstances and scheme. How you receive your money can depend on your provider. Some may pay directly into an overseas bank account, while others may require a UK bank account. Charges and exchange-rate movements could also affect how much you receive, so it's worth checking when considering a move.&quot;</div>

<div> </div>

<div><strong>2. What will happen to my State Pension?</strong></div>

<div>&quot;You can still claim your UK State Pension abroad as long as you've paid enough National Insurance contributions to qualify and notify the Department for Work and Pensions of your move. However, where you choose to live can make a significant difference. In some countries your State Pension will be frozen, meaning it stays at the rate you first receive there and won't benefit from future annual increases, including those awarded under the triple lock. This applies in popular destinations such as Australia, Canada and New Zealand. By contrast, people living in the EU and countries such as the United States currently continue to receive annual increases. It's therefore important to check the rules for your chosen destination before making the move. Over a long retirement, missing annual increases could make a meaningful difference to your income.&quot;</div>

<div> </div>

<div><strong>3. Can I transfer my UK pension to the country I move to?</strong></div>

<div>&quot;You may be able to transfer UK pension savings overseas, but the receiving scheme must normally be a Qualifying Recognised Overseas Pension Scheme, known as a QROPS. If the receiving scheme doesn't qualify, your provider may refuse the transfer or you could face a tax charge of at least 40%. Even where the receiving scheme is a QROPS, a separate 25% overseas transfer charge can apply in some circumstances depending on where you live and where the scheme is based. Moving a pension overseas is a major decision and won't be right for everyone. Some transfers can also require regulated financial advice before they proceed.&quot;</div>

<div> </div>

<div><strong>4. Can I continue paying into a UK pension while living abroad?</strong></div>

<div>&quot;This depends on your provider and your pension scheme's rules. Some providers may allow overseas contributions, but UK pension tax relief isn't automatic and may be restricted. Whether you can continue receiving tax relief depends on your individual circumstances, including your earnings and how recently you lived in the UK. Check the position with your provider and consider taking financial advice if your tax position will involve more than one country.&quot;</div>

<div> </div>

<div><strong>5. How will my UK pension be taxed if I move abroad?</strong></div>

<div>&quot;You may be taxed on pension income both by the UK and by the country where you live, which is why it's important to notify HM Revenue & Customs when you move overseas. The UK has double-taxation agreements with many countries, meaning it may be possible to claim relief and avoid paying tax twice on the same pension income. While up to 25% of a pension can usually be taken tax-free in the UK, different countries may apply different tax treatments, so it's important to understand the local rules before taking money from your pension.&quot;</div>

<div> </div>

<div><strong>6. Will UK inheritance tax apply to a pension transferred overseas?</strong></div>

<div>&quot;From April 2027, most unused pension funds and pension death benefits will be brought into the value of an estate for UK Inheritance Tax purposes, although some benefits are excluded. Transferring a pension overseas won't necessarily remove it from UK Inheritance Tax considerations. Whether tax applies will depend on factors including your residence status and where the pension scheme is established. If inheritance planning forms part of your decision to transfer a pension overseas, it's important to understand both the UK and local rules and consider taking specialist advice.&quot;</div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/planning-to-make-your-holiday-permanent---27128.htm</link>
<pubDate>Tue, 1 Sep 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Pmi Launches New Evidence based Qualification</title>
		<description><![CDATA[<div>The Level 5 Experienced Pensions Professional Certificate (EPPC) acknowledges the role administration plays in delivering high-quality pensions, and aims to raise professional standards across the industry. </div>

<div> </div>

<div>Leading pensions administration company Aptia played a key role in developing the structure and content of the EPPC, ensuring the qualification reflects the realities and demands of modern pensions administration. </div>

<div> </div>

<div><strong>Vanessa Jackson, Chief Learning Officer at PMI, said: </strong>&ldquo;Administration is the backbone of the pensions industry. It is how the promises made to savers are delivered. The EPPC recognises that expertise, giving experienced professionals the recognition they deserve and the confidence to drive better outcomes for members. We&rsquo;re hugely grateful to Aptia for their insight and collaboration in shaping this important qualification.&rdquo; </div>

<div> </div>

<div><strong>Phil Wadsworth, Aptia&rsquo;s Chief Actuary, said: </strong>&quot;As the pensions industry continues to evolve, professional qualifications have an increasingly important role to play in ensuring the sector has the skills and expertise needed to meet future challenges. The EPPC qualification represents a major step forward in the continued professionalisation of pensions administration, recognising the knowledge and experience of established professionals while encouraging a culture of continuous learning and development. We are proud to support an initiative that has the potential to raise standards across the industry and enhance outcomes for millions of pension savers.&rsquo; </div>

<div> </div>

<div><strong>David Fairs, Chair of the Pensions Administration Standards Association, said: </strong>&ldquo;Pensions administration sits at the heart of delivering good outcomes for savers, so investing in and recognising the people who perform these roles is critical. We welcome initiatives which provide experienced pensions professionals with opportunities to gain formal recognition for the expertise they have developed throughout their careers. Continuing to strengthen professional development and recognition across pensions administration will help raise standards, build capability and reinforce administration&rsquo;s standing as a profession.&rdquo;  </div>

<div> </div>

<div>The EPPC &ndash; the PMI's first new qualification since 2022 - offers a new route to professional recognition, assessing competence through real-world evidence rather than exams or coursework.  </div>

<div> </div>

<div>Candidates build a portfolio demonstrating their expertise and impact, helping to create a workforce equipped to deliver better outcomes for savers. </div>

<div> </div>

<div>The launch aligns with the Government&rsquo;s updated Pensions Roadmap, which calls for improved governance, transparency, and value for money. The PMI&rsquo;s new qualification ensures the people delivering these reforms have the professionalism and capability to make them a success. </div>

<div> </div>

<div>Anyone interested in registering their interest in the EPPC can now do so at Register your interest - EPPC | The Pensions Management Institute (PMI) </div>

<div> </div>

<div>The EPPC is the latest step in the PMI&rsquo;s drive to raise standards in pensions administration. Through convening the Administration Industry Group, the PMI has brought the sector together to set higher expectations for professional practice.  </div>

<div> </div>

<div>In parallel, the PMI sits on PASA&rsquo;s Careers Working Group to secure alignment and buy-in for our expanding suite of administration qualifications, including new pathways to PMI Associateship for administration professionals. Work is already underway on a Level 6 administration qualification planned for release in Spring 2027.  </div>

<div> </div>

<div> </div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/pmi-launches-new-evidence-based-qualification-27127.htm</link>
<pubDate>Tue, 1 Sep 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>2026 Natural Catastrophe Losses Europe Heatwaves And El Ni o</title>
		<description><![CDATA[<div> 
<div><iframe allow="accelerometer; autoplay; clipboard-write; encrypted-media; gyroscope; picture-in-picture; web-share" allowfullscreen="" frameborder="0" height="315" referrerpolicy="strict-origin-when-cross-origin" src="https://www.youtube.com/embed/oUdlRDNyTQ8?si=-BO_85fTnNoCKUvq" title="YouTube video player" width="340"></iframe></div>

<p> </p>
</div>

<p> </p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/2026-natural-catastrophe-losses-europe-heatwaves-and-el-ni-o-27126.htm</link>
<pubDate>Tue, 1 Sep 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Lgps National Knowledge Assessment Registrations Now Open</title>
		<description><![CDATA[<div>It will now also be offered annually, a change that will give funds a clear, regular view of the individual Committee and Board members&rsquo; needs, as well as how both groups&rsquo; knowledge levels progress collectively. Further investment and changes to the assessment&rsquo;s format mean that the results are delivered more quickly, with flexible timing to ensure funds can take part at the optimum time in alignment with their training plans.</div>

<div> </div>

<div>The assessment will give funds what they need to assess knowledge levels of newer Committee members at the same time as those that are more experienced. The Hymans Robertson NKA has run biannually since 2020, with 2022 being the year that had the most engagement from committee members across the participating funds (71%). In 2024 the average engagement level sat at just over half (55%) of committee members for the participating funds.</div>

<div> </div>

<div><strong>Commenting on what Committee members should be focussing on, to get the most out of their training, Alan Johnson, Senior Consultant, Hymans Robertson, says: </strong>&ldquo;We&rsquo;ve updated the National Knowledge Assessment so that it meets current requirements under the new regulatory landscape, but also, to satisfy any potential future changes. We have invested in the user interface, making it easier to navigate and save progress, as well as delivering individual results instantly. We&rsquo;ve focused on ensuring it meets the individual needs of the Committee and Board members, and each group as a whole. Moving to an annual assessment allows consistency year on year, and for training needs to be addressed as and when they arise. We are also enabling fund officers to participate, so that results can be used to help inform their own training plans.</div>

<div> </div>

<div>&ldquo;The true value of benchmarking across the LGPS can sometimes be overlooked, but along with gaining an understanding of the relative performance of a Pension Committee and Local Pension Board, against peers when it comes to knowledge, it also helps with engagement. This is why we deliver fund-level reports to help show the collective performance of the Board and Committee and then benchmarking analysis at a national level for all participating LGPS funds.&rdquo;</div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/lgps-national-knowledge-assessment-registrations-now-open-27129.htm</link>
<pubDate>Tue, 1 Sep 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Could  59 A Month Turn Into  1 Million </title>
		<description><![CDATA[<div>The Financial Conduct Authority (FCA) has highlighted figures from HMRC that show  760,000 matured Child Trust Funds, worth an average of &pound;2,000 each, remain unclaimed. Child Trust Funds were designed to give a generation of children a financial head start. Eligible children born between 1 September 2002 (now aged 23 - 24) and 2 January 2011 (now aged 15) received a tax-free account seeded with Government money.</div>

<div> </div>

<div>Anyone aged 18 or over with a matured Child Trust Fund can access their money, whether to help with study and living costs or to put some towards their long-term financial future.</div>

<div> </div>

<div><strong>Maike Currie, VP Personal Finance at PensionBee, comments:</strong> &ldquo;September means back to school, college and university - new starts, new routines and, for many families, new costs. It&rsquo;s also a great opportunity to talk about money and one of the biggest financial advantages we can give our children: starting early and giving their money time to compound.</div>

<div> </div>

<div>&ldquo;For some young adults, that conversation could start with &pound;2,000 they didn&rsquo;t even know they had. A forgotten Child Trust Fund could help with university costs, a first car or simply starting adult life. But if you don&rsquo;t need the money today, think about what it could do for you tomorrow.</div>

<div> </div>

<div>&ldquo;A pension might be the last thing on an 18-year-old&rsquo;s mind, but that&rsquo;s precisely when time is most on their side. Once a Child Trust Fund matures at 18, the money belongs to the young adult. They could choose to withdraw some or all of it and contribute it to a pension, subject to the usual pension contribution and tax relief rules, giving that money decades to potentially grow.&rdquo;</div>

<div> </div>

<div><strong>Could &pound;59 a month turn into &pound;1 million?</strong></div>

<div>Parents of younger children could start even earlier. A Junior pension or SIPP allows you to contribute up to &pound;2,880 net a year for a child with no earnings, with tax relief potentially taking that to &pound;3,600 gross. You don&rsquo;t have to contribute anywhere near that amount either. Small sums invested regularly can become surprisingly large when you give them enough time.</div>

<div> </div>

<div>The table below shows what could happen if a family contributed to a Junior pension or SIPP every month from birth until age 18, stopped contributing at that point and left the money invested until age 67.</div>

<div> </div>

<div>Under these assumptions, contributing just &pound;59 a month from birth to 18 could result in a pension worth around &pound;187,000 at age 67 assuming 5% annual growth, or around &pound;1 million assuming 8% annual growth.</div>

<div>At &pound;240 a month, a family would contribute &pound;2,880 a year, with tax relief increasing the gross amount invested to &pound;3,600. Under the same assumptions, this could potentially grow to around &pound;761,500 at 5% growth or &pound;4.1 million at 8% growth by age 67.</div>

<div><img alt="" src="https://www.actuarialpost.co.uk/images/pic_PensionBeeTrust0109261.jpg" style="height:481px; width:600px" /></div>

<div><span style="font-size:11px"><em>Tax relief figures are rounded. *&pound;240 a month is the monthly equivalent of the &pound;2,880 net annual contribution that can normally receive tax relief for a child with no relevant UK earnings. Figures assume contributions are made from birth until age 18, with no further contributions thereafter and the money remaining invested until age 67. Projections assume investment growth of either 5% or 8% a year, after a 0.70% annual management fee. These are illustrations only. Investment returns are not guaranteed and actual outcomes may be higher or lower.</em></span></div>

<div> </div>

<div><strong>Currie continues:</strong> &ldquo;The million-pound figure is eye-catching, but that&rsquo;s not really the point, the real lesson is what time can do. Contributing &pound;59 a month is less than &pound;2 a day from the family, with tax relief adding to the amount invested. Start when children are young and keep going until 18 and then leave that money alone - a Junior pension or Sipp gives them 50 years or more for the investment returns to compound with tax relief boosting every eligible contribution along the way.  Whether you're saving for their first steps into adulthood or helping them build financial security for later life, starting early means time can do more of the heavy lifting.&rdquo;</div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/could--59-a-month-turn-into--1-million--27130.htm</link>
<pubDate>Tue, 1 Sep 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Ikeas Pos Home Insurance Threatens Insurers Legacy Channels</title>
		<description><![CDATA[<p>According to GlobalData&rsquo;s 2025 UK Insurance Consumer Survey, 30% of consumers said that they would be willing to buy a home insurance policy from IKEA if it were to offer it. Among all alternative providers, IKEA recorded the highest proportion of respondents stating they would be willing to buy a home insurance policy from the brand. In contrast, Amazon, which launched a similar initiative but discontinued it in 2024, attracted 18.4% of positive responses. Meanwhile, only 15.4% of consumers were familiar with the brand Urban Jungle, signaling the partnership is a massive win for the insurtech.</p>

<p><strong>Beatriz Benito, Lead Insurance Analyst, GlobalData, comments:</strong> &ldquo;The IKEA and Urban Jungle partnership reflects the continued market move toward greater convenience, as more partnerships emerge and the embedded insurance move continues to gain traction.&rdquo;</p>

<p>IKEA customers purchasing furniture or home furnishings will be offered contents and buildings insurance cover in the same transaction&mdash;before many of them even thinking about the need for insurance&mdash;creating a frictionless and more-streamlined experience.</p>

<p><strong>Benito continues:</strong> &ldquo;The partnership differs from Amazon&rsquo;s proposition, in which the online giant offered home insurance as if it were a price comparison website (PCW), requiring manual quote inputs, yet working only with a few underwriters. In contrast, IKEA&rsquo;s partnership is solely focused on Urban Jungle&rsquo;s products and is streamlined at the checkout, with no further input required.&rdquo;</p>

<p><strong>Benito concludes:</strong> &ldquo;The rise of embedded insurance partnerships poses a continued threat to traditional distribution channels, particularly insurance brokers and PCWs. Both brokers and PCWs act as middlemen between consumers and insurance underwriters, but the embedded model removes the need for this by integrating insurance at the POS with other products, placing insurance directly in the customers&rsquo; primary journey. While insurers could potentially arrange their own embedded partnerships, the model will naturally disrupt intermediaries, particularly for less-complex cover.&rdquo;</p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/ikeas-pos-home-insurance-threatens-insurers-legacy-channels-27124.htm</link>
<pubDate>Fri, 28 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Market Snapshot   Ripples Across The Pond</title>
		<description><![CDATA[<p>That the company would produce another set of blockbuster results was never in question. However, the additional surprise was its assertion that it would see revenue growth of 70% in 2028, far higher than the 44% analysts were expecting, and further proof that the AI trade is far from exhausted. Indeed, the relief which Nvidia provided came with the suggestion that the AI build-out remains in its early stages where supply simply cannot keep up with demand.</p>

<p>As Nvidia shares rose by almost 9% in reaction, the renewed enthusiasm spilled over into gains of 4.5% for Broadcom, 4% for Intel and 2% for SK Hynix, with the VanEck Semiconductor ETF ahead by 3% as concerns over whether the return on the extraordinary investment on capital will be achievable were put to bed &ndash; at least for the time being.</p>

<p>Elsewhere, software also had a stellar session with Salesforce spiking by almost 23% after beating revenue forecasts and announcing an expanded partnership to pair Anthropic&rsquo;s Claude chatbot with its platform, with the news reading across to the likes of Adobe and Autodesk, whose shares rose by 5.7% and 6.2% respectively. Nor did the rallies end there &ndash; cybersecurity firms Okta and CrowdStrike saw gains of 28% and 20.5% after raising their outlooks and beating estimates, with the boom in demand due to AI at the centre of the additional growth.</p>

<p>The euphoria is set to wane, however, as investors turn their attention to Federal Reserve Chair Warsh will deliver his keynote speech at Jackson Hole. There is much anticipation over his comments on the current Fed thinking, although it has already been made quite clear that the new Chair is happy to eschew the forward guidance to which investors had become accustomed. While there may be a passing reference to the Fed&rsquo;s determination to return the inflation rate to the 2% target, it may also provide less of a clue than is being called for. Indeed, he could disappoint if he simply sticks to the script, with the theme of the symposium being &ldquo;Financial Innovation: Implications for Payments and Policy&rdquo;.</p>

<p>Even so, the Nvidia effect sent the main indices higher and edging once more to the records which each recently set. In the year to date, the Dow Jones has now added 11.5%, the S&P500 12.9% and the Nasdaq 14.2% with the broad tech gains sending the index comfortably higher yesterday.</p>

<p>Inevitably the FTSE100 missed out on the AI party given the relative lack of tech exposure among its constituents and the index limped to a weak close. Its appearance as a tracker without a real technology angle has been both a blessing and a curse this year, missing out on tech-led gains while coming back into fashion as a haven in times of turbulence in other markets. On balance, however, the FTSE100 has enjoyed a sturdy gain of 9.1% so far this year, with an average 3% dividend yield providing an extra boost to total returns.</p>

<p>The generally improved sentiment enabled the primary index to reverse some of the losses from yesterday, with a broad mark-up which encapsulated a cautious risk-on approach lifting the miners, while the banks also ticked higher and 3I Group rose after a broker upgrade. Losses were limited to a marginal decline in the likes of BAE Systems and Babcock International, and the gains hoisted the index to within 0.7% of the record closing high set in February.&rdquo;</p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/market-snapshot---ripples-across-the-pond-27122.htm</link>
<pubDate>Fri, 28 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Government Must Balance Member Protection On Db Surplus</title>
		<description><![CDATA[<p>The Government's DB surplus flexibility consultation reflects the improved funding position many DB schemes now enjoy, raising important questions about how surplus can be used more effectively.</p>

<p>As policymakers now consider how the new surplus regime should operate as the consultation comes to an end, it will need to address a number of pitfalls, says Broadstone.</p>

<p>Greater clarity is needed on how surplus release should interact with a scheme's wider strategy. Decisions regarding surplus extraction should not be considered in isolation but alongside funding, investment and endgame objectives. While funding sufficiency is clearly important, trustees will also need confidence that surplus payments remain consistent with their long-term investment strategy and journey plan. Clearer guidance in this area would support more consistent and practical decision-making.</p>

<p>The supporting TPR guidance should place greater emphasis on operational readiness, including data quality, benefit accuracy and administration preparedness. Equally important is ensuring the regime remains proportionate and practical, particularly for smaller schemes and those seeking to release surplus on a recurring basis as part of a run-on strategy.</p>

<p>A key unanswered question remains how members are expected to benefit from surplus release. Greater clarity on the role of benefit improvements and the balance between employer and member interests would support more consistent trustee decision-making and help ensure the regime delivers fair and visible member outcomes.</p>

<p><strong>David Brooks, Head of Policy at Broadstone, said:</strong> &ldquo;The Government's objective of making run-on a credible option alongside buyout and consolidation is a positive step.</p>

<p>&quot;However, the success of the reforms will depend on striking the right balance between member protection and practical usability. Greater clarity on member benefit-sharing, proportionality and operational requirements will be essential if schemes are to use these new flexibilities with confidence.</p>

<p>&quot;Ultimately, the regime should be judged not only on whether surplus can be released safely, but whether it genuinely influences trustee and sponsor decision-making across the market.&rdquo;</p>

<p> </p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/government-must-balance-member-protection-on-db-surplus-27121.htm</link>
<pubDate>Fri, 28 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Jackson Hole Could Show Warsh s Vision For Future Of The Fed</title>
		<description><![CDATA[<div>While markets will naturally be focused on interest rates, the bigger story this year is Kevin Warsh's first appearance at Jackson Hole as Federal Reserve Chair and what it may reveal about his vision for the future of the Fed.</div>

<div> </div>

<div>&ldquo;Investors will be keen to assess whether Warsh's previous references to a &quot;regime change&quot; at the Federal Reserve signal a meaningful departure from the communication style and policy framework of recent years. Since taking over as Chair, Warsh has shown a clear preference for reducing reliance on detailed forward guidance, instead encouraging markets to focus on economic outcomes rather than attempting to interpret every signal from policymakers.</div>

<div> </div>

<div>&ldquo;As a result, it would be surprising if his speech were used to provide explicit guidance on the next interest rate decision or the near-term path of monetary policy. Instead, Jackson Hole presents an opportunity for Warsh to outline a broader philosophy for how the Federal Reserve should operate in an increasingly complex economic environment. The focus is likely to be on the role of the central bank, the effectiveness of policy communication and the need to maintain credibility in delivering price stability over the long term.</div>

<div> </div>

<div>&ldquo;One of the most notable shifts under Warsh's leadership has been his apparent desire to reduce the market's dependence on Federal Reserve forecasts and policy projections. Jackson Hole could reinforce this approach, with a message that policymakers should retain flexibility and avoid becoming constrained by overly prescriptive guidance. That would represent a continued move away from a framework where market expectations are heavily shaped by central bank forecasts and towards one where incoming economic data plays a greater role in determining policy outcomes.</div>

<div> </div>

<div>&ldquo;For investors hoping for a clear roadmap on rates, the message may therefore prove somewhat frustrating. Rather than focusing on the next policy meeting, Warsh is likely to emphasise the challenges facing central banks in a world characterised by structural economic change, geopolitical uncertainty, rapid technological innovation and evolving financial markets. Ultimately, the significance of this year's symposium may not be what Warsh says about the next few months, but what he signals about how the Federal Reserve intends to operate over the next decade.&rdquo;</div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/jackson-hole-could-show-warsh-s-vision-for-future-of-the-fed-27123.htm</link>
<pubDate>Fri, 28 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Insuring Physical Ai  Robotics Reshaping Risk And Liability</title>
		<description><![CDATA[<p><strong>By Sonal Madhok, Technology and Future Liability Analyst, Willis Research Network</strong> </p>

<p>Morgan Stanley estimates the humanoid robotics market could reach $5 trillion by 2050, with nearly 1 billion robots in use. A more detailed discussion of the market outlook, growth drivers, and adoption trends is available in the companion article.</p>

<p>The technology is already being tested in the real world. In June 2026, Waymo recalled 3,871 robotaxis after reports that some vehicles entered closed freeway construction zones and continued driving at speed. While no injuries were reported, the incident highlighted a growing challenge for autonomous systems: software must interpret and respond to unpredictable physical environments, where road layouts, hazards and operating conditions can change rapidly.</p>

<p>The more AI moves from software into machines that interact with the physical world, the nature of risk changes. A software error that might once have resulted in an incorrect recommendation, biased output or data breach can now lead to bodily injury, property damage, operational disruption and complex liability disputes.</p>

<div><strong>How physical AI turns digital failures into physical losses</strong></div>

<div>Physical AI relies on advanced software intelligence (e.g. machine learning algorithms, generative AI, and autonomous decision systems running in software) and introduces direct interaction with the real world. Software risks tend to be intangible, including bias, IP infringement, privacy breaches or incorrect decisions. Robotics does not replace those risks, but introduces physical consequences such as collisions, fires and operational incidents on top of them.</div>

<p>Examples illustrate these risks: warehouse robots colliding with workers, autonomous vehicles running red lights and crashing, a delivery drone dropping a package on a pedestrian, or an AI-controlled manufacturing machine sparking a fire. U.S. occupational data found 77 robot-related accidents from 2015&ndash;2022 that caused 93 recorded injuries, including finger amputations and fractures. As adoption grows, both frequency and severity of incidents may increase.</p>

<p><strong>Many incidents originate in software failures. </strong>OSHA guidance shows accidents often occur during programming, testing or maintenance, when robots may activate unexpectedly due to control or state-management errors. This risk is heightened in testing environments, where safety mechanisms may be temporarily bypassed.</p>

<p>Cyber threats may also have physical consequences. A compromised robot may not simply lose data; it could disrupt operations, damage property or injure people. As robotics becomes more connected, the boundary between cyber, operational and physical risk continues to erode.</p>

<div><strong>Who is liable when a robot causes harm?</strong></div>

<div>Physical AI expands the liability landscape and introduces shared responsibility. While traditional industrial robots typically operate in controlled environments, humanoid robots are increasingly being designed to work alongside people in factories, hospitals, homes and public spaces. As AI moves into these less predictable settings, questions around supervision, maintenance and responsibility for harm become significantly more complex.</div>

<p>For example, in a warehouse accident where a humanoid robot drops a heavy box on a contractor, liability may fall on different actors:</p>

<div><em>A manufacturer, if there is a design flaw</em></div>

<div><em>A software developer, if an algorithm misjudges balance</em></div>

<div><em>An operator, if safety procedures or training are inadequate</em></div>

<div><em>A maintenance provider, if a sensor or component fails</em></div>

<p>This creates overlapping exposures across product, general, professional liability and cyber lines, complicating accountability and coverage.</p>

<div><strong>Global shifts in liability and regulation for physical AI</strong></div>

<div>Regulators are beginning to adapt legal frameworks to reflect AI operating in the physical world. In Europe, the Product Liability Directive and AI Act strengthen accountability for AI-enabled products and other high-risk systems, including many robotics applications. In the United States, regulation continues to evolve through state legislation and sector-specific guidance. For example, Texas and Arizona have clarified that companies can be held accountable for traffic violations by autonomous systems.</div>

<p>Despite different regulatory approaches, the direction of travel is clear. Responsibility is increasingly being shared between manufacturers and the organizations deploying autonomous systems, placing greater emphasis on governance, operational controls and human oversight.</p>

<div><strong>How insurance is adapting to physical AI</strong></div>

<div>Most physical AI incidents will still trigger traditional insurance policies, but the boundaries between lines of business are becoming increasingly blurred.</div>

<p>Key lines of coverage may include:</p>

<div><em><strong>General liability:</strong> bodily injury and property damage caused by robotic systems</em></div>

<div><em><strong>Product liability: </strong>defects in design or manufacturing of robots</em></div>

<div><em><strong>Cyber insurance: </strong>hacking or software failures leading to physical consequences</em></div>

<div><em><strong>Workers&rsquo; compensation:</strong> employee injuries caused by workplace robots</em></div>

<div><em><strong>Business interruption:</strong> operational disruption caused by robotic failure or downtime</em></div>

<p>The convergence of risks creates overlaps and potential gaps. In response, insurers are clarifying coverage through exclusions and endorsements, developing robotics-specific products and exploring integrated policies combining multiple coverage areas. For instance, some cyber insurance policies now explicitly mention coverage (or exclusions) for AI-driven incidents like algorithmic errors or malicious use of AI.</p>

<p>Specialty underwriters are exploring coverage for autonomous fleets, combining elements of auto, product and cyber liability. Reinsurers are also examining systemic loss scenarios, such as software faults affecting large numbers of robots simultaneously. For example, a software update, cloud outage, navigation error or vulnerability in a widely deployed robotic platform could affect thousands of devices simultaneously. This raises accumulation concerns for insurers and reinsurers. Multiple organizations may often rely on the same operating systems, AI models or software suppliers. While such scenarios remain speculative, they underscore the need for agility in insurance.</p>

<p>Innovation is emerging globally. In 2025, China Pacific Insurance launched &ldquo;Ji Zhi Bao,&rdquo; a policy covering a robot lifecycle from production to deployment, including property damage, third-party liability and short-term testing risks for humanoid robots. Products such as these illustrate how insurers are moving beyond traditional silos, combining liability and asset protection in a single solution.</p>

<div><strong>Lifecycle risks of physical AI</strong></div>

<div>Because robots are physical assets, risk extends across their entire lifecycle, from sourcing and manufacturing to deployment and disposal.</div>

<p>Robotics systems depend on specialized inputs such as semiconductors, sensors and batteries, creating exposure to geopolitical and supply chain disruption. Their high value also introduces transportation and logistics exposures, increasing demand for marine, cargo and transit insurance.</p>

<p>Environmental risks also become more important as deployment increases. Battery production, storage and disposal introduce potential pollution, fire and hazardous waste exposures and contamination that may not be fully covered under traditional property policies, increasing demand for specialist environmental liability cover.</p>

<div><strong>Risk management and governance: building safe deployment</strong></div>

<div>Insurance cannot replace effective risk management. As Willis Research Network partner Dr. Anat Lior JSD, LL.M observes, insurers often play a &ldquo;quasi-regulatory&rdquo; role by requiring risk mitigation measures of their policyholders. In the context of physical AI, these may include safety audits, human oversight and bias or hazard testing. In this way, insurance acts as a lever to improve safety across the market.</div>

<p><strong>As AI moves into these less predictable settings, questions around supervision, maintenance and responsibility for harm become significantly more complex.</strong></p>

<p>This approach is increasingly reflected in international standards governing collaborative and autonomous robots. For example, emerging guidance ISO 25782-1 drafts robot safety for advanced use cases like bipedal humanoids, where they have fail safe mechanisms so a 100kg robot doesn&rsquo;t topple onto someone during a power loss. Together, these place growing emphasis on human oversight, fail-safe mechanisms, safe human-robot interaction and robust operational controls, particularly as robots move beyond factories into public and domestic environments.</p>

<p>Evidence shows these measures are critical. A study from the New South Wales government on working safely with robots notes that incomplete risk assessments for collaborative robots (cobots) can leave hidden risks that only surface after an injury or near-miss. Risk managers may consider thorough hazard analysis before robots go live, proactively addressing questions like: What happens if the robot loses power or connectivity? How will human supervisors intervene if it malfunctions?</p>

<p><strong>Organizations may consider the following key practices:</strong></p>

<div><em><strong>Risk assessments before deployment </strong>including potential failure modes and safety hazards for each robotic application. Many early accidents have revealed oversights in risk assessment.</em></div>

<div><em><strong>Engineer the environment</strong> such as geofencing and zoning to separate robots from vulnerable humans, safety sensors and shutoff systems, and well-defined visual or audio indicators of a robot&rsquo;s status.</em><em>These measures can prevent common errors like unexpected startup of robots when humans are nearby.</em></div>

<div><em><strong>Training and human oversight</strong> to ensure safe operation, maintenance and intervention when required. Many accidents occur when workers assume a machine is inert or offline when it is not. Human supervisors should be ready to intervene if an AI deviates from safe parameters.</em></div>

<div><em><strong>Monitor regulatory change</strong> because robotics and AI regulations are evolving quickly worldwide (from the EU AI Act to local safety rules). Staying ahead of these expectations improves both safety and insurability.</em></div>

<p>These measures reduce operational risk and may improve insurance outcomes. Insurers are increasingly incorporating questions on AI usage and controls in underwriting applications, echoing the way cyber insurers evolved questionnaires on IT security. Demonstrating robust AI governance and safety culture can help companies negotiate better terms or premiums, whereas poor controls might lead to exclusions or higher rates.</p>

<div><strong>Conclusion: Insurability in a new risk paradigm</strong></div>

<div>The transition to physical AI presents significant economic opportunity and introduces complex, overlapping risks. A single incident may span product, cyber and professional risk, making traditional risk boundaries less relevant. Managing safety, cybersecurity and operations together is key. Proactive steps such as reviewing insurance coverage and strengthening safety culture are also essential to reduce exposure. Ultimately, resilience depends on preventing incidents where possible and ensuring clarity in contracts and coverage when they occur.</div>

<p> </p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/insuring-physical-ai--robotics-reshaping-risk-and-liability-27118.htm</link>
<pubDate>Thu, 27 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Debt Nerves And Inflation Jitters As Nvidia Has Mega Results</title>
		<description><![CDATA[<p><strong>Susannah Streeter, Chief Investment Strategist, Wealth Club: </strong>&lsquo;&rsquo;The Footsie may have flirted with fresh closing highs yesterday, but sentiment looks set to become more cautious as investors refocus on worries about inflation proving sticky, huge government debt piles and the prospect of interest rates lingering at elevated levels. The key central bankers&rsquo; meeting at Jackson Hole is getting underway, and Fed chair Kevin Warsh&rsquo;s speech tomorrow will be closely watched for hints about the future path of interest rates. While headline inflation has dipped back, it&rsquo;s not such a benign picture if you look at the Fed&rsquo;s preferred measure, the Personal Consumption Expenditures Price Index. It captures a broader range of prices and spending behaviour, and it&rsquo;s still running hot - headline PCE is at 3.7%, while core PCE came in at 3.3%, above forecasts. That leaves the Fed with a tricky balancing act, with inflation still well above its 2% target just as signs of a cooling economy and a weakening jobs market come to the fore.</p>

<p>There is some relief on the energy front, however, with Brent crude falling back again to $87 a barrel. Hopes are growing that a framework being worked on by Iran and Oman could pave the way for safer shipping through the Strait of Hormuz, easing fears of prolonged disruption to global oil supplies. That is taking some of the geopolitical risk premium out of the price of crude, although the waterway is not yet fully reopened and the wider conflict remains far from resolved, so the risk of renewed volatility remains.</p>

<p>Bond markets have also been febrile, demanding higher yields amid concerns about unruly deficits and precarious levels of national debt. So investors are becoming more cautious about the global outlook, which could weigh on sentiment towards the internationally focused FTSE 100. Given its tech-lite nature, it&rsquo;s also missing out on the renewed surge of enthusiasm for AI stocks after chip star Nvidia&rsquo;s latest bumper set of results. Nasdaq and S&P 500 futures, however, indicate a stronger start for Wall Street, despite wariness about monetary policy, as investors pile back into technology.</p>

<p>The AI juggernaut is rumbling on with Nvidia smashing through expectations, amid voracious demand for the tech backbone of the AI revolution. The results solidified high expectations for the company&rsquo;s mega revenues going forward, and shares firmed up, leaving behind the post-results wobbles seen after previous updates. Given the might of Nvidia, which carries the largest weight of any company in the S&P 500, the results are closely watched as a gauge of sentiment towards AI adoption, and the prospects for the index, which so many portfolios track.</p>

<p>Quarter by quarter Nvidia&rsquo;s revenues are accelerating, landing at $96 billion for the second quarter, more than double a year ago, and the trend looks set to continue with revenue of $108 billion in the next quarter and strong demand stretching into 2028. Demand for its Blackwell chips has been particularly significant, showing that customers are continuing to spend heavily on Nvidia&rsquo;s newest generation of AI accelerators rather than simply filling existing capacity. With demand still running ahead of supply, Blackwell is helping to power the next leg of the AI infrastructure build-out.</p>

<p>However, once the initial excitement settles, questions are likely to resurface about the durability of this boom in revenues. It&rsquo;s becoming less about whether Nvidia can keep climbing the AI mountain, and more about how long it can sustain this extraordinary pace of ascent and whether the vast sums being poured into AI infrastructure will ultimately deliver the returns needed to justify the colossal investment.&rsquo;&rsquo;</p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/debt-nerves-and-inflation-jitters-as-nvidia-has-mega-results-27116.htm</link>
<pubDate>Thu, 27 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Comment On Fca Ai Findings  Pensions Are No Exception</title>
		<description><![CDATA[<p><strong>Donna Walsh, Head of Master Trust and IGC Governance at Standard Life, said:</strong> &ldquo;AI is rapidly becoming part of the way younger people navigate their finances, and pensions are no outlier. Our research1 found that almost three in ten (29%) 18-34-year-olds have already used AI to get information about pensions or saving for retirement, compared with 16% of 35-54-year-olds and just 6% of those aged 55 and over. That makes it increasingly important that people understand both what these tools can offer and where their limitations lie.</p>

<p>&ldquo;There are clear positives if AI can help make pensions feel simpler and more accessible. Among younger people who have used it for retirement information, 41% have turned to AI to understand how pensions work, a third (33%) have used it to navigate pension tax rules and 32% to explore how they could save more. However, this isn&rsquo;t simply passive research - 62% say AI has influenced decisions they&rsquo;ve made about their pension or retirement saving to at least some or a great extent. That underlines why accuracy, appropriate safeguards and knowing when to turn to trusted or regulated sources really matter, particularly at a time when scams and fraudulent activity are becoming increasingly sophisticated and technology can make it harder to distinguish credible information from misleading content.</p>

<p>&ldquo;Used well, AI could have an important role in helping people engage earlier with their retirement planning, breaking down jargon and prompting questions they might otherwise never ask. At the same time, it should be a starting point rather than the final word. Pensions are long-term and often complex, and as use of AI grows, the priority should be helping people combine the convenience of new technology with reliable information, appropriate guidance, targeted support and, where possible, regulated financial advice.&rdquo;</p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/comment-on-fca-ai-findings--pensions-are-no-exception-27117.htm</link>
<pubDate>Thu, 27 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Dc Strategies Rebound As Providers Maintain Long term Focus</title>
		<description><![CDATA[<div>Isio has published its latest analysis of the investment performance and asset allocation of 14 major UK DC master trust providers.</div>

<div> </div>

<div>The latest quarterly update highlights how maintaining exposure to growth assets through periods of short-term volatility can support stronger long-term member outcomes.</div>

<div> </div>

<div>Global equities rebounded strongly in Q2 2026 as geopolitical tensions eased and oil prices fell, improving investor sentiment. Emerging market equities outperformed developed counterparts, led by the technology-heavy markets of South Korea and Taiwan. UK equities underperformed the US and Europe, while credit markets delivered positive returns despite continued uncertainty around interest rates.</div>

<div> </div>

<div><strong>Providers maintain long-term focus through market volatility</strong></div>

<div>Periods of short-term volatility remain an expected feature of long-term investing, particularly for growth-phase strategies with higher exposure to equities and other return-seeking assets.</div>

<div> </div>

<div>Following a challenging start to the year, all growth-phase strategies in Isio&rsquo;s analysis delivered positive returns during Q2, ranging from 11.9% to 19.8%. This compared with a range of +0.9% to -4.5% in Q1 and demonstrated how quickly market conditions can change &ndash; and how difficult short-term movements can be to navigate successfully.</div>

<div> </div>

<div>Longer-term outcomes remained significantly stronger, with one-year returns ranging from 21.1% to 34.3% and three-year annualised returns ranging from 14.3% p.a. to 22.7% p.a.</div>

<div><img alt="" src="https://www.actuarialpost.co.uk/images/pic_IsioGrowth12708261.png" style="height:291px; width:600px" /></div>

<div>The variation in outcomes continues to highlight the importance of strategic design decisions within default strategies. While equity allocations remain a key driver of returns, regional and sector positioning can also produce meaningful differences between providers.</div>

<div> </div>

<div>Providers are also gradually introducing private market exposures and broadening diversification. As allocations to private equity, real assets and private credit become more established, they have the potential to introduce additional sources of return and lead to greater differentiation between strategies over time.</div>

<div> </div>

<div><strong>Diversification supports positive outcomes at retirement</strong></div>

<div>At-retirement strategies also delivered positive returns during Q2, ranging from 4.6% to 7.9%. One-year returns ranged from 8.9% to 16.4%, while three-year annualised returns ranged from 7.6% p.a. to 12.3% p.a.</div>

<div>Importantly, performance was not determined solely by the level of equity exposure. Providers with lower equity allocations were still able to deliver competitive outcomes, reflecting differences in regional positioning, fixed income and alternative asset exposures, and overall portfolio construction.</div>

<div><img alt="" src="https://www.actuarialpost.co.uk/images/pic_IsioGrowth22708261.png" style="height:329px; width:600px" /></div>

<div>This highlights that while asset allocation remains an important determinant of long-term returns, implementation decisions can also have a meaningful impact on member outcomes. As strategies become more diversified, performance differences are likely to be driven by a broader range of factors than equity allocation alone.</div>

<div> </div>

<div>Recent discussions on pension adequacy have reinforced the importance of achieving sufficient investment growth throughout a member&rsquo;s savings journey. Evidence supporting the Pensions Commission&rsquo;s Interim Report indicates that net investment returns could account for around two-thirds of a final pension pot.</div>

<div> </div>

<div>This becomes a more complex balancing act as members approach retirement. While reducing investment risk can help protect accumulated savings, doing so too early may limit the growth needed to deliver adequate retirement income.</div>

<div> </div>

<div><strong>Mark Powley, Head of DC Master Trust Research at Isio, said:</strong> &ldquo;Q2 was a reminder of how quickly market conditions can change. Following a volatile start to the year, markets rebounded strongly and all of the growth-phase strategies in our analysis delivered positive quarterly returns.</div>

<div> </div>

<div>&ldquo;What&rsquo;s notable is that providers have generally maintained a disciplined, long-term approach rather than reacting to short-term market movements. Members who remain invested are better positioned to participate when markets recover, while attempting to time those turning points remains extremely difficult.</div>

<div> </div>

<div>&ldquo;We also continue to see the importance of diversification at retirement. Equity exposure remains an important driver of returns, but it does not explain the full range of outcomes. Regional positioning, fixed income, alternatives and implementation decisions all matter as providers balance capital preservation with the need for continued growth.&rdquo;</div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/dc-strategies-rebound-as-providers-maintain-long-term-focus-27119.htm</link>
<pubDate>Thu, 27 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Government Must Give More Guidance On Multi employer Schemes</title>
		<description><![CDATA[<p>TPT supports the Government&rsquo;s objective of unlocking surplus in well-funded DB schemes while maintaining member protections. It believes the framework strikes a sensible balance between enabling surplus extraction and maintaining appropriate protections for members.</p>

<p>However, as a DB master trust, TPT thinks it is important that DWP and The Pensions Regulator (TPR) should provide additional guidance in a number of areas to ensure the regime can be implemented consistently and effectively across different scheme structures, including multi-employer schemes (MES). TPT also looks forward to engaging on the equivalent surplus release regulations for superfunds in due course, which it expects will largely reflect this regime.</p>

<p>TPT&rsquo;s response focuses on a small number of areas where further clarity would improve the operation of the regime:</p>

<div><em><strong>Low dependency funding test:</strong> TPT argues that the regulations should make clear whether the test is based on a scheme&rsquo;s existing low dependency funding basis or whether an updated basis can be used. Greater certainty is also needed over who determines the basis and how it should be applied.</em></div>

<div><em><strong>Sectionalised and multi-employer schemes: </strong>TPT strongly supports the inclusion of provisions allowing surplus to be assessed and released at section level, which TPT views as particularly important for DB master trusts and sectionalised arrangements. However, the regulations should more clearly distinguish between sectionalised and multi-employer schemes, clarify how employer consent operates at section level, and provide guidance on the allocation of surplus between participating employers. In many circumstances, TPT believes that an employer in a multi-employer scheme wishing to release surplus may find it more straightforward to move into a standalone arrangement.</em></div>

<div><em><strong>Member surplus payments and revaluation:</strong> TPT welcomes the inclusion of provisions covering deferred member surplus payments, but believes the regulations should provide greater clarity on how revaluation should operate, including when revaluation ceases and the implications for members with protected pension ages. Clear rules would help ensure consistent administration, actuarial treatment and member communications.</em></div>

<p>TPT also suggested that the Government could consider allowing schemes to release surplus to pay contributions into a scheme held in a separate trust. Schemes are already able to use surplus to pay DC contributions within the same trust, so TPT believes allowing surplus to be diverted elsewhere could be beneficial in some circumstances. This could include where an employer has open accrual in a CDC scheme that is separate from its closed DB scheme.</p>

<p><strong>Ruari Grant, Head of Policy at TPT, said:</strong> &ldquo;We support the Government&rsquo;s objective of unlocking surplus in well-funded DB schemes while maintaining appropriate protections for members. The proposed regime will provide a workable framework, but greater clarity in a number of areas will be important if it is to operate consistently across the full range of scheme structures.</p>

<p>&ldquo;In particular, the regulations need to reflect the practical complexities of DB master trusts, sectionalised arrangements and multi-employer schemes. As innovative schemes and solutions continue to change the market, regulations must keep pace to ensure there is adequate flexibility for these schemes to fairly and sustainably support their members.&rdquo;</p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/government-must-give-more-guidance-on-multi-employer-schemes-27120.htm</link>
<pubDate>Thu, 27 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Sarah Mcivor Joins Hymans Robertson Wind up Team</title>
		<description><![CDATA[<p>Sarah brings extensive knowledge of the UK pensions and risk transfer market. Prior to Sarah&rsquo;s operations role, she held several senior roles across Scottish Widows&rsquo; bulk annuity teams and also spent more than six years at Mercer advising clients on their pension strategy. With a background spanning pricing, operations and consulting, Sarah has experience across the full endgame journey, most recently leading the transition of schemes through post-transaction milestones, helping trustees and sponsors progress confidently towards wind-up.</p>

<p><strong>Commenting on what Sarah will bring to the role, Christine Cumming, Head of Buy-Out and Wind-Up Transition Services, Hymans Robertson said: </strong>&quot;We are very pleased to welcome Sarah to the team. She brings a vast knowledge and experience from the insurer side of the market, having held a variety of leadership positions across bulk annuity pricing and operations. Her insight into how insurers assess opportunities, manage transactions and support clients post transaction will be invaluable as pension schemes continue to explore their endgame options.</p>

<p>&ldquo;Sarah's appointment further strengthens our ability to support trustees and sponsors. Her combination of technical expertise, commercial understanding and operational experience will help ensure our clients continue to receive the high-quality, pragmatic advice they need to achieve the best outcomes.&quot;</p>

<p><strong>Commenting on her new role, Sarah added: </strong>&quot;I'm excited to be joining Hymans Robertson at a time when the pensions market is evolving rapidly and more schemes than ever are considering their long-term objectives. Having spent much of my career working within the insurer market, I'm looking forward to bringing that perspective to clients and helping them navigate an increasingly complex landscape.</p>

<p>&ldquo;What stood out to me about Hymans Robertson was its strong focus on delivering the right outcomes for clients, combined with a collaborative and people-focused culture. I'm looking forward to working alongside colleagues across the business and helping clients make informed decisions about their future.&quot;</p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/sarah-mcivor-joins-hymans-robertson-wind-up-team-27112.htm</link>
<pubDate>Wed, 26 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Households Brace For Another Bill Rise As Crude Prices Fall</title>
		<description><![CDATA[<p>The AI revolution has turbocharged demand for copper, with data centres, electricity grids, electric vehicles and wider electrification all big channels of demand for the metal.</p>

<p><strong>Susannah Streeter, Chief Investment Strategist, Wealth Club: </strong>&ldquo;The Footsie is on the back foot in early trade, as investors assess the latest geopolitical moves pushing down crude prices. A sharp rise in copper prices is keeping mining stocks buoyant, but investors also have their eye on inflationary risks as energy bills are set to rise again in the Autumn.</p>

<p>Another winter of discontent could be looming for household finances, with energy bills set to rise again just as the colder months approach. Ofgem has increased the energy price cap by 4% from October, adding around &pound;60 a year to the typical household bill and taking the annualised cap from &pound;1,663 to &pound;1,723. The regulator says the increase reflects higher wholesale gas prices, with international gas markets remaining the dominant driver of the change.</p>

<p>It&rsquo;s another unwelcome step up for households, particularly after the sharp rise in the cap earlier this year. And while the Government&rsquo;s decision to remove VAT from domestic electricity bills from October is cushioning the blow, it only provides limited protection against higher wholesale costs. Ofgem estimates that without the VAT intervention, the increase would have been around &pound;45 higher.</p>

<p>The latest increase also shows how quickly geopolitical shocks can filter through into household finances. The Middle East conflict has pushed up international gas prices, while extreme heat across parts of Europe has also increased demand for electricity for cooling, adding to pressure on gas-fired power generation.</p>

<p>Consumers have already had to get used to higher prices at the pumps and have been adjusting their spending accordingly. July retail sales volumes fell 0.5% month-on-month, although sales remained relatively resilient overall and were still 1.6% higher than a year earlier. With energy bills rising again in the autumn, the crucial run-up to Christmas, so important for retailers and hospitality businesses, looks set to become tougher, particularly if households continue to prioritise essentials over discretionary spending.</p>

<p>That puts the Government in an increasingly tricky position. It has already intervened by removing VAT from domestic electricity bills, but if international energy prices remain elevated, there is only so much that fiscal measures can do to shield households from global markets.</p>

<p>There are, however, glimmers of better news in the energy markets this morning with Brent crude falling to $86 a barrel amid signs of encouraging diplomatic moves around the Strait of Hormuz. Iran and Oman are discussing a temporary maritime corridor and mine-clearance arrangements to help restore safer navigation through the strategically vital waterway.  Trump hasn&rsquo;t liked the US being left out of the discussions, with his irritation spilling over into threats against Oman, but this latest development hasn't prompted any further sabre-rattling. Tighter US sanctions on Iran are aimed at pushing Iran into concessions, and that&rsquo;s also been having a downward effect on crude prices.</p>

<p>Meanwhile, CIA Director John Ratcliffe has travelled to Moscow for undisclosed meetings with Russian officials. The purpose of the trip has not been confirmed, so suggestions that it could be aimed at persuading Russia to distance itself from Iran or helping to advance a Ukraine settlement remain speculation. But any diplomatic progress on either front could potentially reduce geopolitical risk premiums embedded in energy prices.</p>

<p>Lower crude prices are pulling down energy giants in early trade, with Shell and BP under pressure. That is putting the Footsie on the back foot despite fresh gains for mining stocks.</p>

<p>Copper is gleaming, with the red metal hitting record highs as inventories outside the US tighten and production disruptions continue to constrain readily available supply. Trump&rsquo;s tariff war is also distorting the market to some extent. Traders have been rushing copper towards the US ahead of potential tariffs on refined copper from 2027, attracted by the prospect of higher American prices. That has pushed US inventories to record levels while stocks elsewhere have become increasingly tight.</p>

<p>At the same time, there have been genuine supply disruptions, including mining problems and a smelter outage in Indonesia, adding to concerns about how quickly global production can respond to stronger demand. And demand for copper is increasingly being turbocharged by the AI revolution. Data centres require enormous amounts of electricity, and copper is crucial for the cables, transformers and power networks needed to deliver it. Electric vehicles, renewable energy projects and the wider electrification of the economy are adding further sources of demand.</p>

<p>This has all helped provide a bit of a tailwind for London-listed miners and demonstrates why the FTSE 100 can often show more resilience when other tech-reliant markets are struggling, given its heavyweight exposure to mining and commodities.&rdquo;</p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/households-brace-for-another-bill-rise-as-crude-prices-fall-27110.htm</link>
<pubDate>Wed, 26 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title> 1 28bn Payment Fraud Bill Shows Importance Of 159 Service</title>
		<description><![CDATA[<p>The warning comes as the latest UK Finance Annual Fraud Report reveals criminals stole &pound;1.28 billion through payment fraud during 2025, up 4% year-on-year. Authorised Push Payment (APP) fraud alone accounted for &pound;576.4 million in losses, including &pound;75.6 million in business losses. Everywhen believes the figures underline the importance of businesses preparing employees for increasingly sophisticated social engineering, where a fraudulent call may appear entirely genuine.</p>

<p><strong>Neil D&rsquo;Mello, Client Director at Everywhen, said: </strong>&ldquo;The growing number of calls to 159 demonstrates just how important the service has become, but the question businesses should be asking is: would your employees know when to use it?  A scam call doesn't necessarily sound like a scam anymore. Fraudsters can be professional, knowledgeable and reassuring. The warning sign may only come when that trust turns into pressure to act immediately.</p>

<p>&ldquo;If somebody is telling you there isn't time to verify who they are, that's exactly when you should stop, hang up and call 159!&rdquo;</p>

<p>Launched in 2021, the 159 service provides a simple route for people receiving unexpected calls about financial matters to end the conversation and independently contact their bank. Working on a similar principle to 101 for the police and 111 for the NHS, callers dial 159 and select their bank before being connected safely. The service now connects customers representing more than 99% of UK retail bank current accounts.</p>

<p>For businesses, Everywhen says its importance lies not just in the number itself, but in the behaviour, it encourages: stop the conversation, remove the pressure and verify independently. That principle can also be applied to unexpected requests apparently coming from suppliers, IT providers, customers or senior colleagues.</p>

<div><strong>Telephone fraud can carry a disproportionate cost</strong></div>

<div>The latest UK Finance figures also demonstrate why suspicious calls should remain firmly on the business radar. 17% of APP fraud cases in 2025 originated through telecommunications, these accounted for 28% of all APP fraud losses. Overall, APP fraud losses increased 19% to &pound;576.4 million during the year, with 248,070 cases recorded.</div>

<p>Developments such as AI-assisted communications and voice cloning add another dimension to the threat, reinforcing why businesses should increasingly focus on verification rather than recognition. A familiar voice, professional manner or knowledge of an organisation should not automatically be considered proof that a caller is genuine.</p>

<p><strong>Neil D&rsquo;Mello added:</strong> &ldquo;The question is no longer simply, &lsquo;Does this sound like a scam?&rsquo; It should be, &lsquo;Should I independently verify that this is genuine?</p>

<p>&ldquo;Cyber scams continue to evolve in sophistication and can have significant financial and reputational consequences for clients. Brokers should understand how cyber-related information, alerts, and tools are being used within their advice and client service processes, and ensure appropriate oversight is in place. This can help reduce the risk of clients falling victim to fraud, phishing, social engineering, or other cyber threats&rdquo;.</p>

<p>Ultimately, clients will continue to look to their broker for trusted professional advice and guidance, including risk management support, in helping them navigate an increasingly complex cyber risk landscape.</p>

<p><strong>Neil concludes:</strong> &ldquo;Cyber insurance can provide an important line of defence when an incident occurs, but resilience also depends on people and processes. Employees should feel confident stopping and challenging an unexpected request, regardless of how convincing the person making it seems to be. 159 is a simple example of that principle in action. It is well worth making sure that your employees are fully aware of these three very important numbers.&rdquo;</p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/-1-28bn-payment-fraud-bill-shows-importance-of-159-service-27115.htm</link>
<pubDate>Wed, 26 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Pension Surplus Options Open Before April 2027 Flexibilities</title>
		<description><![CDATA[<div><strong>Conducted during the spring of this year, the survey covered 350 DB schemes in the UK. Key findings include:</strong></div>

<div><em>Among schemes in surplus and intending to run-on, 76% had not yet agreed how to share surplus between employers and members. Among respondents where the position had been agreed, 62% were distributing part of the surplus solely to the employer. A further 17% were distributing part of the surplus to benefit members only, with the remaining 21% sharing distributions of surplus between employers and members.</em></div>

<div> </div>

<div><em>Among schemes in buyout surplus and intending to buyout, 50% were yet to agree how to share surplus between employers and members. Among respondents where the position had been agreed, around 66% were returning surplus only to the employer, with the remainder sharing this with members or providing surplus to members only.</em></div>

<div> </div>

<div><em>73% of schemes with a threshold for surplus release were adopting a threshold above the low dependency basis.</em></div>

<div> </div>

<div><em>11% of schemes distributed some form of surplus to members in 2025.</em></div>

<div> </div>

<div><em>The most common approach was to grant a discretionary pension increase, with 7% of schemes granting one in 2025, down from 13% in 2024.</em></div>

<div> </div>

<div><strong>James Patten, Partner in the UK Endgame Strategy team, Aon, said: </strong>&ldquo;Despite 57% of schemes being at least fully funded on a buyout basis - and thus generally having a surplus - the majority remain undecided around its use. It therefore seems that there is all to play for as schemes consider the new surplus flexibilities to be introduced next April.</div>

<div> </div>

<div>&ldquo;For schemes in surplus that are intending to run on, and where a decision has been reached, we found the majority intend to distribute part of the surplus solely to the employer. In some cases, this is an interim position of using part of the surplus to finance expenses, ongoing accrual of DB provision, or employer DC contributions. In many cases, we expect this will be reviewed again by sponsors and trustees ahead of the 2027 surplus flexibilities.</div>

<div> </div>

<div>&ldquo;For schemes in surplus, intending to buyout and where a decision has been reached, we again see that the majority intend to return surplus solely to the employer. However, this will often be influenced by scheme rules, with 50% of respondents having rules where the use of surplus on wind-up is ultimately determined by the employer. Next year&rsquo;s flexibilities are likely to prompt conversations around whether the distribution of some surplus - above that needed for buyout - can be accelerated, rather than waiting for the buyout and wind-up process to play out in full.</div>

<div> </div>

<div>&ldquo;Most schemes are yet to consider a threshold for surplus release. However, where a decision has been reached, it is notable that the vast majority are adopting a threshold generally above the minimum low dependency basis proposed under the new surplus flexibilities. For example, this might involve including a buffer above the low dependency basis in the threshold for surplus release.&rdquo;</div>

<div> </div>

<div><strong>Nick Coates, Head of Member Distributions, Aon, said: </strong>&ldquo;From a member perspective, our survey suggested the use of discretionary pension increases remained the most popular way of distributing surplus to members. But this is likely to change considerably from April 2027 when there is the option of lump sum provision. A key question for some trustees next year, will be whether to provide discretionary pension increases or lump sums as a way of distributing surplus to members. These options will also lead to surplus being shared in radically different ways among members.</div>

<div> </div>

<div>&ldquo;It is also interesting to see that just 7% of respondents had provided such an increase - down from 13% in 2024. Funding levels generally rose over the period, but this change is likely to have been driven by the more benign inflationary environment. The new flexibilities will bring future distributions of surplus to members into sharp focus for many trustees next year, particularly given the expected need to inform members of any lump sum returns of surplus to sponsors.</div>

<div> </div>

<div>&ldquo;A key development since last year&rsquo;s survey is that among schemes that are running-on and which have decided to share part of the surplus with members, 43% intend to use it to provide independent financial advice. There is growing demand from members for this, and, where it is not offered, there are potential pitfalls where members &lsquo;phone a friend&rsquo; - often in the form of artificial intelligence - to inform significant financial decisions.&rdquo;</div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/pension-surplus-options-open-before-april-2027-flexibilities-27113.htm</link>
<pubDate>Wed, 26 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Young Investors Trust Ai More Than Tv Or Celebrities</title>
		<description><![CDATA[<p>But the research from the Financial Conduct Authority (FCA) also revealed that these investors may be misunderstanding the level of protection if they rely on AI to support their investing decisions:</p>

<div><em>Almost half (44%) mistakenly believe AI-generated financial information is regulated. </em></div>

<div><em>More than one in three (38%) believe it&rsquo;s fine to make an investment decision based solely on the outputs of AI.</em></div>

<div><em>Around a third (32%) wrongly think they'd get compensation from the Financial Services Compensation Scheme (FSCS) or Financial Ombudsman Service (FOS) if AI advice went wrong.</em></div>

<p>But almost three quarters (73%) know that AI can provide inaccurate information. And 86% understood the need to check the sources referenced when using AI. It&rsquo;s vital investors remember this when they&rsquo;re using AI to research an investment.</p>

<p>General purpose AI chatbots are not regulated, although tools which are specifically set up to provide financial advice would be likely to fall within the FCA&rsquo;s remit.</p>

<p><strong>Lucy Castledine, Director of Consumer Investments at the FCA, said: </strong>&ldquo;AI can help you research companies, understand jargon or explore options before you make a decision. But you need to understand how you&rsquo;re protected and continue to use your own judgement. Our InvestSmart website can also help you make more informed decisions.&rdquo;</p>

<p><strong>Here are five tips for using AI safely when it comes to your money:</strong></p>

<div><em><strong>Stay in the driving seat.</strong> AI can inform your decisions, but the final call is yours.</em></div>

<div><em><strong>Check your sources.</strong> Ask the AI where it got its information from, then verify it yourself. </em></div>

<div><em><strong>Know there's no safety net. </strong>Unlike regulated financial advice, AI-generated tips from general-purpose chatbots mean you are not covered if things go wrong. </em></div>

<div><em><strong>Past performance is not a guide to future returns.</strong> AI can only provide you with historical data, it cannot predict how your investment will perform.</em></div>

<div><em><strong>Think long-term.</strong> Investing isn't a get-rich-quick scheme, whether the tip came from AI or your mate down the pub.</em></div>

<p>Learn more about investing and risk on the <a href="https://www.fca.org.uk/investsmart">FCA&rsquo;s InvestSmart website.</a></p>

<p> </p>

<div><em>General purpose AI tools are not regulated by the FCA. These tools can respond to a variety of prompts and topics but aren&rsquo;t set up to help consumers with financial advice, research, or decision making. This differs from a tool deployed specifically to provide financial advice, which would be likely to fall within our remit.</em></div>

<div><em>This research was conducted by the FCA via the platform Attest using a quantitative usage & attitudes (U&A) study. The survey was conducted on 24 July 2026 to understand consumer adoption, trust, comfort, and future expectations regarding the use of AI tools for personal investment research and financial decision-making in the UK market.</em></div>

<div><em>The sample comprised 666 respondents based in the United Kingdom, open to all adults across the 18 to 40 age range. All participants either currently own investments or would consider buying investments in the next 12 months.</em></div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/young-investors-trust-ai-more-than-tv-or-celebrities-27111.htm</link>
<pubDate>Wed, 26 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>The Retirement Reality Gap</title>
		<description><![CDATA[<p>Britons are surprisingly optimistic about the retirement they want, but far less confident about their ability to pay for it, new research from PensionBee reveals.</p>

<p>More than half of UK adults (56%) say they feel hopeful or excited about retirement. Most can picture what they want their later years to look like, with more time with family (59%), travelling (55%) and simply resting (51%) among the most popular ambitions.</p>

<p>Yet this emotional optimism is rarely matched by financial certainty. Just 16% have both worked out how much they will need and feel confident they&rsquo;re on track to reach their retirement goals. More than a third (38%) have no idea how much their desired retirement will cost. 18% say they are confident they&rsquo;ll achieve their retirement goals despite having no idea what those goals will cost.</p>

<div><strong>Optimism meets an uncomfortable price tag</strong></div>

<div>Part of the problem is that many people appear to be underestimating the cost of the retirement they want. More than three quarters (77%) put the annual cost of a comfortable retirement below the &pound;45,400 benchmark set by Pensions UK for a single person. Nearly half (47%) estimate it would cost &pound;30,000 a year or less. That is at least &pound;15,400 below the comfortable benchmark, and even below the &pound;32,700 Pensions UK defines as a moderate retirement &ndash; a standard that includes an annual overseas holiday and eating out a couple of times a month.</div>

<p>This is a substantial gap because the State Pension only covers part of the cost. The full new State Pension is worth &pound;12,548 a year in 2026/27, leaving &pound;32,852 a year to be funded from other income and savings for anyone targeting a comfortable retirement. Pensions UK estimates that currently only around 9% of the working population is currently on track to reach that standard.</p>

<div><strong>The confidence gap isn&rsquo;t simply about apathy</strong></div>

<div>The findings suggest that a lack of financial preparation isn&rsquo;t always a lack of motivation. Among the 39% who feel they&rsquo;ve left retirement planning too late, affordability is the biggest barrier. Nearly a third (32%) say they couldn&rsquo;t afford to engage with their pension sooner. That is twice the proportion who say they didn&rsquo;t know where to start (16%) and nearly three times the proportion who found pensions too complicated (12%).</div>

<p>The financial pressure facing households helps explain why. Recent ONS data found that 35% of adults think they would be unable to save any money at all over the next 12 months, while 56% say their cost of living has risen in the past month.</p>

<p>The Pensions Commission has also warned that millions of working-age adults are not saving enough for retirement, showing that the gap between retirement aspirations and financial preparedness is not simply a question of individual behaviour.</p>

<div><strong>Every generation feels the gap differently</strong></div>

<div>The confidence gap also looks different across generations. Gen Z are the most likely to feel anxious or overwhelmed by retirement, with 42% saying they feel this way or try not to think about it, including 17% who avoid the subject altogether.</div>

<p>At the other end of the spectrum, Gen X are the most likely generation to feel they have left retirement planning too late, at 48%. Across all age groups, 43% of adults say they did not seriously think about their pension until they were 36 or older, while for one in four (26%), nothing has yet made retirement feel real.</p>

<p><strong>Maike Currie, VP Personal Finance at PensionBee, said:</strong> &ldquo;Britons aren&rsquo;t short of retirement dreams. What they&rsquo;re short of is confidence that their finances will make those dreams a reality. That&rsquo;s the irony in these findings. People are far more certain about the retirement they want than they are about their ability to pay for it. </p>

<p>&ldquo;For plenty of people, the barrier is money, not motivation. No amount of encouragement can fix a month that doesn&rsquo;t balance. When the choice feels like paying today&rsquo;s bills or funding a retirement decades away, today will win. </p>

<p>&ldquo;But financial confidence can be built. For people who are in a position to take action, the first steps don&rsquo;t need to be complicated. A retirement calculator can help put a rough price on the future they want. Finding out what they already have and bringing old pensions together can give them a clearer picture of where they stand. Turning a distant hope into something tangible that you can put a number on is a powerful first step. Once you know what you&rsquo;re aiming for, you can start making a plan to get there.&rdquo;</p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/the-retirement-reality-gap-27114.htm</link>
<pubDate>Wed, 26 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Us Sanctions  Ai Jitters And The Search For Safer Ground</title>
		<description><![CDATA[<p><strong>Susannah Streeter, Chief Investment Strategist, Wealth Club: </strong>&ldquo;Markets are in wait-and-see mode, as stricter US sanctions on Iran take hold and investors wait for the latest snapshot of demand for AI infrastructure from tech giant Nvidia. The FTSE 100 looks set to continue to grind higher, extending its run as heavyweight miners bolster the blue-chip index. The London market is proving remarkably resilient given the cocktail of geopolitical tensions, stubborn inflation concerns and uncertainty over the path of interest rates. The Footsie&rsquo;s relatively low exposure to the tech sector is also helping it avoid some of the turbulence rippling through global tech shares, giving investors a different mix of sectors to rely on.</p>

<p>Gold in particular has been shining, hovering around a more than three-month high, as investors position for a weaker dollar amid concerns about US debt, government borrowing and the potential for currency devaluation. The so-called &ldquo;debasement trade&rdquo; is gathering momentum, with investors seeking assets that are harder to devalue through monetary policy. So, gold is regaining its lustre as a traditional hedge against weakening currency. At the same time, more speculative bets on Bitcoin are being placed as a digital alternative. Bitcoin has surged above $80,000 in one of its strongest multi-day rallies in years, as expectations of dollar weakness fuel demand. The US Treasury&rsquo;s move to increase purchases of longer-dated government bonds in an attempt to lower borrowing costs appears to have fuelled the moves, with investors questioning whether this could ultimately put further pressure on the dollar. For the Footsie, it&rsquo;s had beneficial knock-on consequences as higher gold and other metals prices are boosting the earnings outlook for mining giants, giving the index an advantage over more technology-heavy markets.</p>

<p>Energy prices are steadying, with Brent crude settling just under $92 a barrel, as traders assess the latest stage of the chronic crisis in the Middle East. Iran says it&rsquo;s in it for the long haul as the US tightens the screws on its economy, attempting to clamp down on oil exports. President Donald Trump is giving Iran&rsquo;s customers, including China, a deadline to cut their commercial ties or risk facing US sanctions of their own.</p>

<p>For investors, though, it&rsquo;s still highly unclear whether this stance will force the conflict towards a breakthrough or simply add another layer of uncertainty and push back hopes of a deal and the reopening of the Strait of Hormuz.</p>

<p>Tech investors are shifting uneasily in their seats ahead of Nvidia&rsquo;s latest results tomorrow. The chip giant has fast become the financial pulse of the AI revolution and, given how heady valuations have become, it has to prove that demand is still accelerating. Its crucial customers are the hyperscalers - big tech names such as Microsoft, Meta, Amazon and Alphabet, and investors will be looking for more signs of long-term commitment to the AI infrastructure build-out.</p>

<p>Bumps in the road ahead are becoming more visible. There&rsquo;s a growing backlash against data-centre construction, there are worries about whether AI-fuelled returns will justify the spending, and Chinese chip rivals are marching in for business. Memory chip stocks have again come under selling pressure, after fresh cracks appeared in the incumbents&rsquo; hold on the market. Micron and SanDisk fell back sharply, while South Korea&rsquo;s stars Samsung and SK Hynix suffered fresh declines. It comes amid reports that Apple is seeking permission to source memory chips from Chinese manufacturers, including CXMT, as it looks for ways to ease pressure from the global memory shortage. The Trump administration has publicly pushed back against the move, with Commerce Secretary Howard Lutnick saying Washington does not want Apple buying Chinese memory.</p>

<p>However, the capricious nature of the US administration&rsquo;s policymaking, particularly when it comes to trade, makes it hard to see a clear path ahead. The US stance on Iran creates fresh geopolitical uncertainty for the semiconductor industry. If Washington follows through with secondary sanctions on countries and companies continuing to do business with Iran, the fallout could extend beyond energy markets and into corporate supply-chain decisions. With China already at the centre of the debate over memory chips, any escalation in US-China trade tensions may make Western technology groups even more cautious about sourcing critical components from Chinese manufacturers. At the same time, the memory shortage and the enormous demand generated by AI data centres are creating a powerful commercial incentive to look for alternative sources of supply. It leaves companies like Apple caught between cost, availability and increasingly complicated geopolitical considerations.</p>

<p>With geopolitics still so fraught, and US economic policy increasingly being questioned, it&rsquo;s little surprise there&rsquo;s been a continued drive to diversify away from US assets after such an eye-watering bull market run. One of Europe&rsquo;s wealthiest families is providing a striking example of this shift. The Rausing family, heirs to the fortune built through Tetra Pak, has sold more than $1 billion of US equities in the second quarter, roughly a fifth of its US stock holdings. That included a 15% stake in Sensient Technologies worth at least $660 million, alongside more than 100 other US positions, including holdings in Wells Fargo, Chipotle and Abbott Laboratories.</p>

<p>Instead, the family has been building its position in Swedish private equity giant EQT, with its holding now around 6%, making it one of the company&rsquo;s largest shareholders. It&rsquo;s another example of how investors with long-term horizons are becoming more highly focused on diversification, given how stretched some valuations have become.</p>

<p>That doesn&rsquo;t mean a correction is imminent, as markets can remain expensive for a very long time, but it does underline the growing concerns about US equities, particularly the technology sector, being priced for an exceptionally rosy future.</p>

<p>By increasing exposure to private equity, the Rausings&rsquo; actions also highlight the appeal of investing in businesses away from the daily noise of public markets. The shift towards EQT comes as the private-markets giant continues to return capital to investors, totalling almost &euro;17 billion in the first half of the year,  showing the scale of capital being recycled through private markets.</p>

<p>It&rsquo;s clear that after a spectacular run in US equities, some of the world&rsquo;s most established pools of private wealth are becoming more selective, taking profits and looking for diversification beyond the US stock market.&rdquo;</p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/us-sanctions--ai-jitters-and-the-search-for-safer-ground-27103.htm</link>
<pubDate>Tue, 25 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Demystifying Life Actuarial Technology</title>
		<description><![CDATA[<p><strong>By Mark Brown, Global Proposition Lead, Life Financial Modeling, Insurance Consulting and Technology, WTW</strong></p>

<p>But what do these concepts mean? And what implications do they have for life insurers and actuarial modelling platforms? This article explores the next stage in the evolution of AI systems.</p>

<div><strong>What is MCP?</strong></div>

<div>Large Language Models (LLMs) are very effective at generating text and code. However, they have traditionally operated in isolation. They can answer questions, but they cannot naturally access company systems, databases, modelling platforms or business processes.</div>

<p>The Model Context Protocol (MCP) addresses this challenge. MCP provides a standard way for AI systems to connect to external tools, applications and data sources. Rather than building custom integrations for each AI model and each application, organisations can expose capabilities through MCP connectors.</p>

<p>You can think of MCP as similar to an API (programming interface) for AI to use. An AI agent can connect to many different systems through MCP, just like an app can link to other systems via their APIs.</p>

<div><strong>Examples could include:</strong></div>

<div><em>Document repositories</em></div>

<div><em>Actuarial modelling platforms</em></div>

<div><em>Reporting systems</em></div>

<div><em>Development tools</em></div>

<div><em>Knowledge bases</em></div>

<div><em>Workflow applications</em></div>

<p>Instead of asking an AI model to explain how to run a process, users can ask it to execute the process directly using approved tools.</p>

<div><strong>What is Agent-to-Agent AI?</strong></div>

<div>Agentic AI systems can already perform tasks independently. However, a single agent often becomes complicated when responsible for many different capabilities.</div>

<p>A more scalable approach is Agent-to-Agent collaboration. Under this model, multiple specialist agents work together.</p>

<div><strong>For example:</strong></div>

<div><em>A Planning Agent defines objectives</em></div>

<div><em>A Data Agent gathers information</em></div>

<div><em>A Modelling Agent performs calculations</em></div>

<div><em>A Validation Agent checks results</em></div>

<div><em>A Reporting Agent prepares outputs</em></div>

<p>Rather than relying on one enormously complex system, each agent focuses on a specific responsibility. This mirrors how human teams operate today.</p>

<div><strong>Why does MCP matter for Agentic AI?</strong></div>

<div>Agentic AI becomes far more powerful when agents can interact not only with each other but also with enterprise systems. Without MCP, Agents can reason, can write content and have limited access to operational systems.</div>

<p>With MCP, Agents can retrieve data, can update records, can trigger workflows, can access governed business applications and can collaborate across technology platforms.</p>

<p>The combination enables AI systems to move from &quot;advising&quot; to &quot;doing&quot;.</p>

<div><strong>What could this mean for life insurers?</strong></div>

<div>Many insurance processes involve gathering information from multiple systems and coordinating work across many different specialists.E</div>

<div> </div>

<div><strong>Examples include:</strong></div>

<div> </div>

<div><strong>Financial Reporting</strong></div>

<div><em>Where agents could gather model outputs, retrieve assumptions, validate data quality, generate management commentary and prepare reporting packs.</em></div>

<div><strong>Product Development</strong></div>

<div><em>Multiple agents could review product specifications, generate model requirements, produce test cases, document results and prepare governance evidence.</em></div>

<div><strong>Assumption Management</strong></div>

<div><em>Agent teams could monitor experience studies, identify emerging trends, propose assumption updates, generate approval documentation, track implementation progress.</em></div>

<p>In each case, humans remain responsible for decisions and governance, while AI reduces manual effort.</p>

<div><strong>But isn&rsquo;t that Business Process Excellence?</strong></div>

<div>Both automation (BPE) and agentic AI emulate humans and can alleviate their workloads. Both are helpful to actuaries and in financial reporting. However, they approach the problem from opposite ends, and thus complement rather than compete.</div>

<p>BPE solutions, such as WTW&rsquo;s Unify, replay processes and workflows, including their interactions with other toolsets (via APIs) and humans. They&rsquo;re robust and reliable, provide progress reporting, governance and clear auditability. If something goes wrong, they fail noisily.</p>

<p>Agentic solutions, on the other hand, solve the problem in a creative and dynamic way, again interacting with other toolsets (via MCP) and humans. They&rsquo;re flexible, can cope with the unexpected to an extent; but if something goes wrong, they fail silently and you may never know.</p>

<p>Cost is another important consideration when evaluating Agentic AI against automation. Traditional process automation derives much of its efficiency from being deterministic, with known execution paths and predictable resource consumption. By contrast, agentic AI introduces dynamic decision-making, variable execution paths, and thus higher and less predictable incurred costs.</p>

<div><strong>What does this mean for actuarial reporting?</strong></div>

<div>Historically, actuarial platforms have focused on model definition and calculations. For many companies, this view has already expanded to cover the end-to-end reporting and management information cycles.</div>

<p>Agentic toolsets and application integrations can further reduce the low-value human workloads in both the modelling and reporting arena; including understanding requirements, maintaining documentation, validating changes, investigating issues, preparing reports and communicating the governance. Whether manual or automated, MCP-enabled agent ecosystems allow AI systems to support each stage of this process.</p>

<div><strong>What challenges remain?</strong></div>

<div>Despite the excitement, several challenges remain. Security and governance become increasingly important when AI systems gain access to enterprise tools. Equally in their use, organisations must ensure appropriate permissions, audit trails, data protection considerations, human oversight and human controlled decision-making.</div>

<p>Users also need to be aware of costs. We&rsquo;ve all heard anecdotes of AI spend costing more than the humans it replaced. You should consider:</p>

<div><strong>Is AI appropriate for the task?</strong></div>

<div><em>For example, high-volume repeatable processes are often better automated, reserving AI use for judgement-intensive or highly variable activities.</em></div>

<div><strong>Are you using the right AI models?</strong></div>

<div><em>Some models can consider more options and in more depth than is needed, driving up their costs further than the value added. Many models also prompt for further use beyond the initial ask &ndash; the equivalent to the burger-shop asking &ldquo;would you like fries with that?&rdquo;</em></div>

<div> </div>

<div><strong>Is now the time to invest?</strong></div>

<div>While MCP and Agent-to-Agent AI are still emerging technologies; they&rsquo;re mature enough and clear enough in their direction that many organisations are experimenting with early proof of concepts. What&rsquo;s clear from the early projects, though, is that two areas are key for success:</div>

<div> </div>

<div><strong>Operational Foundations</strong></div>

<div><em>Having robust and reliable tools for the AI agents to interact with. For agents producing management information; this means building them around robust and automated reporting processes. For product design work, direct model access may suffice.</em></div>

<div><strong>Governance</strong></div>

<div><em>Where agents are able to contribute to workflows, either in modelling or reporting, you need a robust governance process that captures their recommendations, the review and approvals of those, and to be able to identify everything impacted by those agents.</em></div>

<div> </div>

<div>The question is no longer whether AI will participate in actuarial processes. The question is how quickly organisations can establish the governance, tooling and operating models needed to do so safely and effectively.</div>

<p> </p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/demystifying-life-actuarial-technology-27106.htm</link>
<pubDate>Tue, 25 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Turning Down Pay Rise  Bonus Or Promotion Over Tax Concerns</title>
		<description><![CDATA[<div>A pay rise should feel like progress, but new research from Standard Life, a retirement specialist focused entirely on retirement savings and income, finds that one in six (16%) have hesitated over or refused a pay rise, bonus or promotion because they were concerned they could lose out financially, including 5% who have turned an opportunity down altogether.</div>

<div> </div>

<div>It&rsquo;s now five years since the income tax threshold was frozen and rising wages are pushing more people into higher tax bands, affecting their eligibility for valuable support. This is shaping how some people feel about future progression. Over a fifth (21%) say paying a higher rate of income tax could make them consider turning down a pay rise, while 7% cite the risk of losing other financial support or allowances and 5% point to losing childcare support.</div>

<div> </div>

<div><strong>Younger workers and parents are more likely to think twice</strong></div>

<div>Younger workers are particularly cautious. Over a quarter of Gen Z (28%) say they have hesitated over or refused a pay increase, compared with 19% of Millennials, 10% of Gen X and just 3% of Baby Boomers.</div>

<div> </div>

<div>Parents with children under 18 are also more likely to have hesitated, at 22% compared with 14% of non-parents. Almost one in ten parents (9%) say losing childcare support could make them turn down a pay increase, versus 4% of non-parents, a figure that may reflect people considering the potential impact on future family plans.</div>

<div> </div>

<div><strong>Less than half know pensions could help</strong></div>

<div>Pension contributions can reduce adjusted net income and may help some people manage the impact of key income thresholds, but the research found that awareness of this is low. Less than half (48%) correctly identify that increasing pension contributions can help reduce the amount of income tax some people pay, while 37% do not know and 15% believe this is false.</div>

<div> </div>

<div>Once the potential benefit is explained, more than half (56%) say they would consider increasing their pension contributions if it helped them retain more of a pay rise or bonus, rising to 63% of Gen Z workers.</div>

<div> </div>

<div><strong>Five years of frozen thresholds</strong></div>

<div>The potential role pensions can play has become more relevant as frozen tax thresholds have fallen behind inflation. Five years after the freeze was announced, Standard Life analysis shows that the Personal Allowance would stand at &pound;16,072 in 2026/27 had it kept pace with inflation - &pound;3,502 above its current level. The higher-rate threshold would be &pound;64,274, rather than &pound;50,270.</div>

<div> </div>

<div><img alt="" src="https://www.actuarialpost.co.uk/images/pic_StandardLifeBonus12508261.png" style="height:132px; width:439px" /></div>

<div> </div>

<div>Based on this, the frozen Personal Allowance adds &pound;700.36 to the annual income tax bill of a basic-rate taxpayer who uses the allowance in full. For someone earning above the inflation-adjusted higher-rate threshold, the combined impact of both frozen thresholds is &pound;3,501.22.</div>

<div> </div>

<div>For some people, increasing pension contributions could help manage this impact by reducing adjusted net income or extending the amount taxed at the basic rate, depending on how contributions are made. This could help them retain more of a pay rise or bonus while also boosting their retirement savings.</div>

<div> </div>

<div><strong>Neil Jones, Tax and Estate Planning Specialist at Standard Life plc, said:</strong> &ldquo;A pay rise, promotion or bonus should be something to celebrate, so it&rsquo;s concerning that some people are thinking twice because they&rsquo;re worried they could end up worse off. It&rsquo;s understandable that people want to protect valuable allowances and manage how much tax they pay, but turning down additional income without fully understanding your options could mean missing out unnecessarily.<br />
 </div>

<div>&ldquo;The findings also highlight a knowledge gap around pensions, with less than half aware that increasing contributions can help reduce the amount of income tax some people pay. For those approaching certain income thresholds, paying more into a pension may, depending on their circumstances, help reduce the tax impact while also putting more aside for retirement.</div>

<div> </div>

<div>&ldquo;With changes to salary sacrifice due from April 2029, one of the tools some employees currently use to increase pension saving and improve tax efficiency could become less effective. That may reduce the options available to help offset the impact of a pay rise or bonus through pension contributions, making it even more important that people understand the options available before deciding whether turning down additional income is the right choice for them.&rdquo;</div>

<div> </div>

<div><strong>Neil&rsquo;s top tips if a pay rise has pushed you into higher-rate tax band in the 2026/27 tax year:</strong></div>

<div> </div>

<div><strong>1. Understand how pension salary sacrifice works</strong></div>

<div>&ldquo;If your employer offers salary sacrifice, increasing pension contributions can reduce your taxable income while putting more into your pension. This can be particularly useful if a pay rise takes you into a higher tax band or across another important income threshold. You may also pay less National Insurance than if you took the additional salary as cash, although the rules around salary sacrifice are due to change from April 2029.&rdquo;</div>

<div> </div>

<div><strong>2. Check you&rsquo;re getting the pension tax relief you&rsquo;re entitled to</strong></div>

<div>&ldquo;Pension contributions benefit from tax relief, and this can become more valuable as your tax rate rises. Basic-rate taxpayers effectively receive 20% tax relief, while higher and additional-rate taxpayers can qualify for relief at 40% and 45%. Depending on how contributions are made, the additional relief may need to be claimed from HMRC, so it&rsquo;s worth checking you&rsquo;re receiving what you&rsquo;re entitled to.&rdquo;</div>

<div> </div>

<div><strong>3. Keep an eye on your Personal Savings Allowance</strong></div>

<div>&ldquo;Moving into a higher tax band can also change how much interest you can earn on savings before paying tax. The Personal Savings Allowance is &pound;1,000 for basic-rate taxpayers, falling to &pound;500 for higher-rate taxpayers, while additional-rate taxpayers don&rsquo;t receive an allowance. If a pay rise moves you into a new band, it&rsquo;s worth checking what that could mean for any cash savings you hold.&rdquo;</div>

<div> </div>

<div><strong>4. Check what a higher income means for family support</strong></div>

<div>&ldquo;For parents, rising income can affect valuable support. The High Income Child Benefit Charge starts when the higher earner&rsquo;s adjusted net income exceeds &pound;60,000, with Child Benefit fully clawed back at &pound;80,000. There&rsquo;s another important threshold at &pound;100,000, when eligibility for Tax-Free Childcare can be lost. Pension contributions can reduce adjusted net income, so it&rsquo;s worth understanding how these thresholds interact if your earnings are increasing.&rdquo;</div>

<div> </div>

<div><strong>5. Watch out for the &pound;100,000 threshold</strong></div>

<div>&quot;If your income exceeds &pound;100,000, you start to lose your Personal Allowance, meaning more of your earnings become taxable. This can result in a surprisingly high tax bill on additional income, including pay rises or bonuses. Pension contributions can reduce your adjusted net income and may help some people preserve more of their Personal Allowance.&quot;</div>

<div> </div>

<div><strong>6. Don&rsquo;t forget Marriage Allowance</strong></div>

<div>&ldquo;Marriage Allowance, worth up to &pound;252 a year, is another benefit that can be lost if either partner becomes a higher-rate taxpayer. A pay rise, bonus or overtime payment could be enough to affect eligibility, so checking your wider financial position when your income changes can help avoid any surprises.&rdquo;</div>

<div> </div>

<div><strong>7. Consider tax on your investments</strong></div>

<div>&quot;The tax impact of frozen thresholds doesn't stop with your salary. In some cases, reducing your taxable income through pension contributions may mean you pay a lower rate of tax on investment gains, making it worth considering how different parts of your finances work together.&quot;</div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/turning-down-pay-rise--bonus-or-promotion-over-tax-concerns-27105.htm</link>
<pubDate>Tue, 25 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Scale Policy Timeline Risks Paralysis And Harming Innovation</title>
		<description><![CDATA[<div>While welcoming the government&rsquo;s ambition to harness scale for Defined Contribution (DC) pension schemes, the representative body highlighted critical areas requiring urgent regulatory clarity and greater flexibility, particularly regarding the definition of Common Investment Strategies (CIS) and the measurement of scheme scale.</div>

<div> </div>

<div><strong>Key Highlights of the SPP&rsquo;s Response:</strong></div>

<div> </div>

<div><strong>Urgent need for interim guidance</strong></div>

<div>The DWP's proposal to wait until late 2027 for draft regulations creates a prolonged period of uncertainty. The SPP urges the government to issue interim guidance on policy direction, exemptions, and transitional arrangements to prevent providers from pausing vital strategic investments.</div>

<div> </div>

<div><strong>Expanding eligible assets in the Main Scheme Default Arrangement (MSDA)</strong></div>

<div>The SPP supports Assets Under Management (AUM) as the core scale metric, provided clear operational guidelines exist for valuations, illiquids, and market volatility. Crucially, the SPP calls for bespoke default arrangements and self-select options using common building blocks to be included in MSDA calculations, ensuring employer engagement is not penalised and scheme scale is not understated.</div>

<div> </div>

<div><strong>Flexibility beyond age-based criteria</strong></div>

<div>The SPP strongly cautions against restricting Common Investment Strategy (CIS) variations strictly to chronological age. Restricting CIS flexibility threatens target-date funds, limits decumulation and guided retirement pathways (under the Pension Schemes Act 2026), and jeopardises the viability of Sharia-compliant and ESG-focused default options.</div>

<div> </div>

<div><strong>Replacing restrictive &lsquo;Common Control&rsquo; tests</strong></div>

<div>The SPP argues that relying on existing Regulation 29(5) tests excludes contract-based Group Personal Pensions (GPPs) and multi-trust provider structures. The SPP recommends replacing this with a Corporate Group Test paired with investment strategy alignment to capture true economic purchasing power.</div>

<div> </div>

<div><strong>Addressing joint governance conflicts</strong></div>

<div>Managing a joint CIS across connected schemes or separate trustee boards introduces natural governance friction. The SPP emphasises that clear regulatory framework rules are required to prevent conflicting strategic preferences between trustee boards.</div>

<div> </div>

<div><strong>Chris Austin, Chair of the SPP Investment Committee, commented: </strong>&quot;While the SPP understands the government&rsquo;s goal of leveraging scale to deliver better outcomes for pension savers, clarity and speed are paramount. Waiting until late 2027 for draft regulations leaves the industry in limbo, threatening to stall vital investment and stifle innovation at a time when providers should be preparing for 2030.</div>

<div> </div>

<div>Furthermore, scale cannot be a one-size-fits-all exercise. An overly rigid, age-only definition of investment strategies risks penalising engaged employers, undermining guided retirement pathways, and cutting off essential choices like Sharia-compliant or ESG-focused funds. Government must introduce sensible flexibility and early guidance so that the industry can execute these changes effectively.&quot;</div>

<div> </div>

<div><a href="https://the-spp.co.uk/document/the-spps-response-to-the-dwp-discussion-paper-on-key-elements-of-the-scale-policy/">The SPP&rsquo;s consultation response is available in full, here.</a></div>

<div> </div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/scale-policy-timeline-risks-paralysis-and-harming-innovation-27104.htm</link>
<pubDate>Tue, 25 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Cohabiting Over 55   10 Risks And How To Protect Yourself</title>
		<description><![CDATA[<p><strong>Sarah Coles, head of personal finance at AJ Bell, comments: </strong>&ldquo;The estimated number of older people living together without tying the knot has risen more than 50% in just ten years. We&rsquo;re not trying before we&rsquo;re buying &ndash; increasingly people aren&rsquo;t buying into the whole idea of marriage at all: most cohabitees under age 65 have never been married to anyone.</p>

<p>&ldquo;There are all sorts of reasons people might not be keen on the legalities. If the couple met when they were older, after one or both had a former spouse pass away, they may have death benefits they could lose if they tied the knot again.</p>

<p>&ldquo;They may also have children from a former relationship and they want to protect their assets in the event the marriage came to an end. If that is the case, it&rsquo;s worth keeping an eye on proposed changes to the rules around cohabitation, which are expected to give cohabiting partners some rights after they have lived together for a certain number of years. It may mean they don&rsquo;t have the protection they expect.</p>

<p>&ldquo;Regardless of why they choose not to get married, they are running some financial risks that could seriously damage their finances, especially in the event of a split, or if their partner passes away. As you get older you have more to lose, less time to make up for losses, and the chance of your partner dying increases. It means it&rsquo;s vital to understand the risks and take steps to protect yourself.&rdquo;</p>

<div><em>If you split up, you have no right to your partner&rsquo;s pension. If you&rsquo;re retired, this could wipe out the lion&rsquo;s share of your income, with no time left to rebuild. It&rsquo;s why building pensions in your own name is so important.</em></div>

<div> </div>

<div><em>You have no right to any spousal maintenance &ndash; payments made to a former partner after separation - even if you have given up work to care for your children and all private pensions are in your partner&rsquo;s name.</em></div>

<div><em>In the event of a split, you have no right to any assets unless they&rsquo;re held jointly or in your own name. It&rsquo;s why you need to consider the ownership of assets carefully. Similarly with debts, there&rsquo;s no right for them to be split fairly, even if you borrowed in your own name for joint expenses. It&rsquo;s why you need to be careful about how you borrow. You can also draw up a cohabitation agreement to lay out what would happen in the event of a split, which could prove useful if you end up in court.</em></div>

<div> </div>

<div><em>If your partner owns your home in their name alone, you have no automatic right to a share in it if you split, even if you contribute towards bills and the mortgage. If this happens later in life, you could have to move out with no way of paying for a roof over your head. It can make sense to change the ownership of the property to reflect your contributions in order to give you those rights. If you own the property, your partner can make a claim for some of the value in it if you split up. They would need to go to court and it&rsquo;s difficult to prove, but it can be done.If either partner dies without a will, their assets are split according to intestacy rules. That means the children of the person who passes will inherit their assets, and if they have no children it will go to the parents, then siblings. The rules give nothing to unmarried partners. If you own property jointly or have joint accounts you will receive these, but nothing else. It&rsquo;s one reason why it&rsquo;s so essential for unmarried couples to have up-to-date wills.</em></div>

<div> </div>

<div><em>If they die without completing a nomination of beneficiaries form for their personal pension, it&rsquo;s up to the pension trustees as to whom receives any death benefits. The trustees will require you to evidence your dependence on your partner but they may also choose to follow any expression of wish your partner had given them. It&rsquo;s important to understand who your partner has nominated. If you&rsquo;re relying on this pension as your main income, this can be devastating.</em></div>

<div> </div>

<div><em>If they have life insurance that isn&rsquo;t written in trust it will pay into their estate when they die. If they don&rsquo;t have a will, it will be distributed according to intestacy rules, so their partner could receive nothing. If they have death in service cover, and they haven&rsquo;t told their employer it should pay out to you, there may be the discretion to pay to a long-term partner, but there will be a need to investigate the circumstances and there could be a delay.</em></div>

<div> </div>

<div><em>You can&rsquo;t take advantage of the rules that apply to married couples on death, which let you pass as much of your assets to your spouse without inheritance tax (IHT) after your death. Within marriage IHT is calculated on the death of the second partner and nil rate bands can be transferred to your spouse, effectively resulting in a married couple having twice the IHT exemption of a single person. Unmarried couples don&rsquo;t have this benefit at all, so if you&rsquo;re leaving more than your nil rate bands there will be IHT to pay. It means it&rsquo;s worth considering gifts during your lifetime, which may escape the IHT net.</em></div>

<div> </div>

<div><em>You can&rsquo;t inherit state pension rights if you&rsquo;re not married. For married couples, these rights only exist if you retired before the introduction of the new state pension in 2016 or have protected payments under the old system, but they can make a significant difference</em></div>

<div> </div>

<div><em>You have fewer rights when it comes to bereavement support payments too. These may apply if you&rsquo;re married and you are under state pension age when your partner dies. However, these only apply to unmarried partners when they also qualify for child benefit &ndash; or if they&rsquo;re pregnant. This becomes less likely when they&rsquo;re older.</em></div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/cohabiting-over-55---10-risks-and-how-to-protect-yourself-27107.htm</link>
<pubDate>Tue, 25 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Rise Of The  golden Gap Year </title>
		<description><![CDATA[<p>For some, it follows redundancy or burnout. For others, children leaving home, caring responsibilities easing or retirement coming into view creates a natural window. For many, it may simply be a case of deciding that some of their retirement dreams are worth enjoying sooner rather than later.</p>

<p>The trend also reflects a wider rethink about later life. Government research found that 55% of people aged 40 to 75 who had not yet retired said they would definitely or probably consider a Midlife MOT, designed to help people take stock of their finances, skills and wellbeing.</p>

<p><strong>Maike Currie, VP Personal Finance at PensionBee, comments:</strong> &ldquo;For years, the words &lsquo;gap year&rsquo; conjured up images of backpacks, hostels and young people heading off to see the world before starting their careers. But increasingly, it&rsquo;s older generations who are taking time out.</p>

<p>&ldquo;And rightly so - why should gap years be wasted on the young? After decades spent working, raising families, paying mortgages and saving for retirement, it&rsquo;s understandable that more people want to enjoy some of that freedom while they&rsquo;re fit and healthy enough to make the most of it.&rdquo;</p>

<p>However taking a gap year at 58 is financially very different from taking one at 18. Time away from work can mean lost salary, missed workplace pension contributions and potentially a gap in your National Insurance (NI) record. For those considering dipping into their pension to pay for the adventure, there can be longer-term tax consequences.</p>

<p><strong>Five money checks before taking a golden gap year.</strong></p>

<div><strong>Check your State Pension record</strong></div>

<div>Time away from work could leave a gap in your National Insurance (NI) record. You normally need at least 10 qualifying years to receive any new State Pension, while those whose NI record started after April 2016 normally need 35 qualifying years for the full amount. Check your State Pension forecast before you go. Missing years can sometimes be filled through NI credits or voluntary contributions. </div>

<div> </div>

<div><strong>2. Check what happens to your workplace pension</strong></div>

<div>If you take unpaid leave or a sabbatical, your own and your employer&rsquo;s pension contributions may stop, depending on your employer and scheme rules. That means the cost of a year away could include not just lost salary, but lost pension contributions and potential investment growth too. Check your employer&rsquo;s policy before you go.</div>

<div> </div>

<div><strong>3. Keep your pension ticking over</strong></div>

<div>Even with little or no relevant UK earnings, you can generally receive tax relief on pension contributions of up to &pound;3,600 gross a year, provided you're eligible. In a relief-at-source pension, that would typically mean paying &pound;2,880 yourself, with &pound;720 in basic-rate tax relief added. Even small contributions can help keep your retirement savings on track.</div>

<div> </div>

<div><strong>4. Think carefully before dipping into your pension</strong></div>

<div>If you&rsquo;re 55 or over, you may be tempted to use your pension to fund the adventure. But flexibly taking taxable income from a defined contribution pension can trigger the Money Purchase Annual Allowance (MPAA). Once triggered, the MPAA limits future contributions to &pound;10,000 a year before an annual allowance tax charge may apply. The standard annual allowance is currently &pound;60,000, although it can already be lower for some higher earners. This matters particularly if you plan to return to work and resume pension saving.</div>

<div> </div>

<div><strong>5. Budget for coming home too</strong></div>

<div>Don&rsquo;t spend everything on the adventure. Keep an emergency fund separate from your travel budget, allow for ongoing costs such as your mortgage/ rent and insurance, and leave enough to cover the period after you return, particularly if you don&rsquo;t have a job waiting for you.</div>

<p><strong>Currie concludes:</strong> &ldquo;A golden gap year is really about buying yourself something incredibly valuable: time. But you don't want the trip of a lifetime to leave a lasting hole in your retirement.</p>

<p>&ldquo;Think of it as planning for two journeys at once. There&rsquo;s the adventure you want to have now, and the much longer retirement still ahead of you. Check your State Pension, understand what happens to your workplace pension and think very carefully before dipping into retirement savings. With some planning, taking time out now doesn't have to mean sacrificing financial security later.&rdquo;</p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/rise-of-the--golden-gap-year--27108.htm</link>
<pubDate>Tue, 25 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Jackson Hole Could Reveal Warsh s Vision For The Feds Future</title>
		<description><![CDATA[<div>While markets will naturally be focused on interest rates, the bigger story this year is Kevin Warsh's first appearance at Jackson Hole as Federal Reserve Chair and what it may reveal about his vision for the future of the Fed.</div>

<div> </div>

<div>&ldquo;Investors will be keen to assess whether Warsh's previous references to a &quot;regime change&quot; at the Federal Reserve signal a meaningful departure from the communication style and policy framework of recent years. Since taking over as Chair, Warsh has shown a clear preference for reducing reliance on detailed forward guidance, instead encouraging markets to focus on economic outcomes rather than attempting to interpret every signal from policymakers.</div>

<div> </div>

<div>&ldquo;As a result, it would be surprising if his speech were used to provide explicit guidance on the next interest rate decision or the near-term path of monetary policy. Instead, Jackson Hole presents an opportunity for Warsh to outline a broader philosophy for how the Federal Reserve should operate in an increasingly complex economic environment. The focus is likely to be on the role of the central bank, the effectiveness of policy communication and the need to maintain credibility in delivering price stability over the long term.</div>

<div> </div>

<div>&ldquo;One of the most notable shifts under Warsh's leadership has been his apparent desire to reduce the market's dependence on Federal Reserve forecasts and policy projections. Jackson Hole could reinforce this approach, with a message that policymakers should retain flexibility and avoid becoming constrained by overly prescriptive guidance. That would represent a continued move away from a framework where market expectations are heavily shaped by central bank forecasts and towards one where incoming economic data plays a greater role in determining policy outcomes.</div>

<div> </div>

<div>&ldquo;For investors hoping for a clear roadmap on rates, the message may therefore prove somewhat frustrating. Rather than focusing on the next policy meeting, Warsh is likely to emphasise the challenges facing central banks in a world characterised by structural economic change, geopolitical uncertainty, rapid technological innovation and evolving financial markets. Ultimately, the significance of this year's symposium may not be what Warsh says about the next few months, but what he signals about how the Federal Reserve intends to operate over the next decade.&rdquo;</div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/jackson-hole-could-reveal-warsh-s-vision-for-the-feds-future-27109.htm</link>
<pubDate>Tue, 25 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Canada Life Appoint New Managing Director Of Bpa</title>
		<description><![CDATA[<div>Dominic will lead Canada Life&rsquo;s end-to-end BPA proposition, setting its strategic direction, accelerating growth and strengthening its position as a provider of innovative pension de-risking solutions that deliver long-term security for schemes and their members. He will report to Canada Life&rsquo;s Chief Executive, Emma Watkins, and will sit on Canada Life&rsquo;s Executive Committee. </div>

<div> </div>

<div>Dominic brings over 20 years of experience in the pensions and insurance industry, including 12 years in the UK BPA market. He joins Canada Life from Legal & General where, most recently as Head of Origination and Execution, he led its commercial team and was accountable for the development of its BPA proposition, management of external relationships, delivery of BPA transactions and their efficient transition to buyout.</div>

<div> </div>

<div><strong>Emma Watkins, Chief Executive, Canada Life UK, comments: </strong>&ldquo;Canada Life&rsquo;s BPA business has strong momentum, achieving important milestones in the last year, including taking our first schemes with deferred members to buyout and delivering an industry-first buyout member experience through our Your Life Hub, with WeCare at its heart. Dom brings exceptional leadership and deep market experience, positioning us to accelerate our BPA strategy and scale for the future. His appointment marks a real step change in Canada Life&rsquo;s ambition in the BPA market and reinforces our commitment to being a long-term partner of choice for pension schemes and their members.&rdquo; </div>

<div> </div>

<div><strong>Dominic Moret, Managing Director, Bulk Purchase Annuities, Canada Life, comments: </strong>&ldquo;I was attracted to Canada Life by the combination of a strong and established platform, talented people and a real ambition to grow in the BPA market with the backing of global parent Great-West LifeCo. I&rsquo;m excited about the opportunity to build on the progress already made and take the business to its next phase.</div>

<div> </div>

<div>&ldquo;For me as Managing Director, that means combining commercial ambition with a relentless focus on the experience we deliver to pension scheme members and trustees, and building on solid foundations to further develop our capabilities and build stronger, long-term relationships with pension schemes and their advisers.&rdquo;</div>

<p> </p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/canada-life-appoint-new-managing-director-of-bpa-27097.htm</link>
<pubDate>Mon, 24 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Why Salary Sacrifice Remains A Powerful Tool In Dc Pensions</title>
		<description><![CDATA[<p><strong>By Ken Anderson, Director, DC MOT Leader, Mercer</strong></p>

<p>Changes to pensions can cause a lot of uncertainty and that&rsquo;s why it&rsquo;s vital for companies to assess what has actually happened. In the 2025 Budget, the chancellor Rachel Reeves outlined forthcoming alterations to the salary sacrifice regime, which prompted widespread concern.</p>

<p>While some might argue the proposals - to cap the pension contributions that can be made free of National Insurance via salary sacrifice at &pound;2,000 per employee per year - discourage long-term savings, the benefits of the policy have not been entirely eradicated.</p>

<p>That&rsquo;s because even once the rule is enacted in three years&rsquo; time, salary sacrifice will still be available for firms to offer to their employees. And workers will still be able to sacrifice &pound;2,000 of their salaries in this way without any tax implications.</p>

<p>Over and above that level, National Insurance contributions (NIC) will apply to both employers and their people, albeit even with the change implemented, pensions will still be fundamentally tax efficient.</p>

<p>Not only will income tax relief still apply, but salary sacrifice will still be available on the first &pound;2,000 without National Insurance being liable. That makes salary sacrifice more tax-efficient than standard pension contributions, which trigger both employer and employee NIC in respect of the employee&rsquo;s contributions.</p>

<div><strong>The importance of education</strong></div>

<div>Our <a href="https://www.mercer.com/en-gb/insights/pensions/defined-contribution-schemes/optimising-workplace-pensions-for-2026/">DC (Defined Contributions) MOT report</a> reveals that only 75% of employers use salary sacrifice in full, which means there is a significant minority of employers that are not taking full advantage of the tax incentives offered by salary sacrifice.</div>

<p>There is a possibility that the public discussion that followed the announcement about the forthcoming salary sacrifice cap created confusion and disproportionate concern about the overall value of pensions. However, it is important for employers to ensure they fully comprehend what any changes actually mean, and then educate their workers about any potential impacts. It is encouraging that 55% of employers engage with their staff about their pensions at least annually, according to our DC MOT data.</p>

<p>In relation to salary sacrifice, it could be prudent for employers to provide guidance to their people here, particularly for more highly paid employees who could be the most exposed to the incoming cap on salary sacrifice NIC savings.</p>

<p><a href="https://www.mercer.com/en-gb/insights/pensions/defined-contribution-schemes/optimising-workplace-pensions-for-2026/#download">Download the full DC MOT Report 2026 here</a></p>

<div><strong>Navigating change</strong></div>

<div>Movements in national pension policy do require attention from employers because they can add new complexities and limits. However,  that does not mean the benefits of pensions are completely removed, and DC schemes still offer one of the most tax-efficient routes for retirement savings in the UK.</div>

<p>With regards to the forthcoming salary sacrifice changes, there are a few legitimate structural and design considerations that can help mitigate the impact of the new cap. These will vary depending on a scheme&rsquo;s profile, and we will be working closely with our clients to explore what approaches may suit their circumstances.</p>

<p>These will vary depending on scheme profile, and we will be working closely with our clients to explore what approaches suit their circumstances.</p>

<div><strong>Actions to consider:</strong></div>

<div><em>Employees may now wish to review how contributions are made into their DC schemes. If they are not currently made via salary sacrifice, this could be introduced now before the cap is applied. If salary sacrifice is in place, then it could be prudent to check that its use is wholly optimised.</em></div>

<div> </div>

<div><em>It could also be sensible to review the support available to members to help them understand complex tax matters when saving for their future.</em></div>

<div> </div>

<div><em>Leadership teams may also wish to introduce effective support to assist employees to make better decisions at retirement.</em></div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/why-salary-sacrifice-remains-a-powerful-tool-in-dc-pensions-27102.htm</link>
<pubDate>Mon, 24 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Legal And General Appoint Head Of Origination And Execution</title>
		<description><![CDATA[<div>Her appointment reflects L&G's continued focus on helping pension schemes secure their members' benefits for the long term, while providing trustees, sponsors and advisers with the expertise, support and certainty they value. As schemes increasingly look beyond pricing alone, greater emphasis is being placed on execution certainty, transition support and member experience when selecting an insurer. Throughout her career at L&G, Rachel has built a reputation for understanding clients' objectives, solving complex challenges and helping schemes achieve positive outcomes for their members. In her new role, she will lead the team responsible for supporting schemes through the transaction process, working across origination, execution and the wider business to help deliver a joined-up journey for trustees, sponsors, advisers and members.</div>

<div> </div>

<div><strong>John Towner, Managing Director, PRT, Institutional Retirement, L&G, said:</strong> &ldquo;Rachel's appointment reflects the strength of talent within our business and the strong reputation she has built across the market over many years. She combines deep technical expertise with strong commercial judgement and is highly regarded for her ability to build trusted relationships, understand clients' objectives and help them navigate complex challenges. Rachel has played a key role in a number of our most important transactions and consistently demonstrated a client-focused, solutions-oriented approach. Her leadership will help ensure we continue to deliver the high standards of service, responsiveness and support that clients value from L&G, while maintaining our focus on positive outcomes for members.&quot;</div>

<div> </div>

<div><strong>Rachel Cutts, Head of Origination and Execution, Institutional Retirement, L&G, commented:</strong> &quot;As the PRT market continues to grow and becomes increasingly sophisticated, clients are looking for a partner that can deliver expertise, certainty and a seamless experience throughout the initial buy-in transaction, the journey to buyout and beyond. Over my nine years at L&G, I've seen first-hand the strength of our team and the value of combining market-leading execution with long-term support for clients and pension scheme members. I'm looking forward to leading the Origination and Execution team and building on that strong foundation.&quot;</div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/legal-and-general-appoint-head-of-origination-and-execution-27098.htm</link>
<pubDate>Mon, 24 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Trade Tensions  Iran Sanctions And Shien Ipo Under Pressure</title>
		<description><![CDATA[<p><strong>Susannah Streeter, Chief Investment Strategist, Wealth Club: </strong>&lsquo;&rsquo;London&rsquo;s Footsie is treading water in early trade as investors assess fresh fractures on the trade landscape and the threat of hard-line sanctions against Iran. Wall Street is set for a weak start as worries about the US debt pile continue to build and long-term debt remains highly expensive to finance amid the Trump administration&rsquo;s highly capricious policymaking. The US is changing tactics in its battle against Iran, and its fight to get oil flowing more freely from the region. Sanctions are the latest weapon of choice and the arsenal is set to be unveiled at a press conference later.</p>

<p>Using the invective the administration has become infamous for, Treasury Secretary Scott Bessent stated in an interview that &ldquo;economic D-Day is coming for Iran.&rdquo; The emphasis is expected to be on isolating Iran economically and targeting its trading partners, with oil exports and the financial channels supporting Tehran likely to be central to the measures. But quite how effective this will be, given China is Iran&rsquo;s biggest customer for oil, is far from clear. The reaction on oil markets has been muted, with Brent crude dropping slightly but still trading around $93 a barrel. There may be some relief that the threats have moved from military strikes to some form of super sanctions, but there is little confidence that a route to a peace deal will open up any time soon, with Iranian Supreme National Security Council secretary Mohsen Rezaei vowing to halt oil exports from the Gulf if the economic war continues. However, there are some hints that there may be splits opening up within Iran&rsquo;s leadership about strategy and increased willingness among some to get back to the negotiating table.</p>

<p>Having stirred up a hornets&rsquo; nest in the Middle East, there may have been some expectation that the US administration would seek to bolster relationships elsewhere, but instead the opposite has happened. Relations between the USA and Canada have taken another fractious turn after trade talks collapsed, leading to 50% tariffs on some Canadian goods being imposed over the weekend. The new duties will affect around 5% of Canada&rsquo;s exports to the US, covering a range of products including food, furniture, clothing, cosmetics and cement, and they come on top of existing tariffs on steel, aluminium, cars and timber. Canadian exporters will be bracing for a drop in sales if US importers try and find alternative supplies rather than paying the tariffs. But it&rsquo;s likely many costs will be passed on through wholesalers and retailers and it will be American consumers who&rsquo;ll end up paying more, with tariffs acting like a tax on imports. While the impact on inflation through this latest hike should be relatively contained, the cumulative effect of tariffs across multiple trading partners is an increasing worry, especially combined with higher energy prices induced by conflict in the Middle East.</p>

<p>The collapse in US-Canada trade talks could add another upward nudge to Treasury yields, with the trade row deepening concerns about US economic policy, mounting debt and inflationary pressures. The Trump administration has tried to sell tariffs as a way of bringing in huge amounts of government revenue and helping tackle America&rsquo;s debt mountain. But the chaotic tariff regime has been beset with legal challenges and has led to mass refunds, so far from making a dent, the US deficit is heading towards $2.1 trillion this year and the national debt has just breached $40 trillion. Also, tariffs and wars are not just costly, they risk acting as a drag on growth while simultaneously pushing up prices, creating a toxic combination. Slower growth can also mean weaker tax revenues, making it harder for the US to grow its way out of its debt mountain. These are all concerns that will be playing on central bankers&rsquo; minds, ahead of the key Jackson Hole summit later this week, and investors will be looking for insights from Fed Chair Kevin Warsh about where interest rates could head given the highly tricky economic and monetary environment.</p>

<p>Also today, Shein is strutting towards its Hong Kong stock market debut, but after a stumble in its latest results, investors will be asking whether the fast-fashion giant can still command the fast-fashion catwalk. Shein is targeting a valuation of almost $27bn when it lists on 1 September, but it&rsquo;s a far cry from the $100bn valuation it enjoyed back in 2022.</p>

<p>The IPO follows failed attempts to list in the US and London, amid regulatory scrutiny, and comes as the ultra-cheap fashion model faces a tougher runway. The pressure is already showing. Shein swung to a $99m loss in the first quarter, compared with a $395m profit a year earlier, as sales slowed and costs rose. Although the loss was also heavily affected by a $328m fair-value accounting charge on convertible preferred shares, the underlying picture is looking less flattering, with sales growth slowing and the US, its biggest market, taking a particular hit. The removal of the US de minimis tariff exemption, which allowed low-value parcels to enter the country without import duties, has hit Shein and rival Temu particularly hard. The change threatens one of the core advantages of their fast fashion model which is focused on sending huge volumes of cheap individual parcels directly to shoppers.</p>

<p>And the US isn&rsquo;t alone in tightening the rules. The EU is also introducing new charges on low-value parcels, while the UK is further down the road but still planning to tighten its small-parcel customs regime, including removing the current &pound;135 customs duty relief. That could gradually narrow the price gap between Shein and high-street rivals such as Primark and H&M, taking some of the sparkle out of its ultra-cheap offering.</p>

<p>At the same time, fast fashion is far less popular than it was a decade ago, with the rise of resale websites proving tough competition, given that shoppers can get their hands on higher-end brands, at a fraction of the price, to refresh wardrobes. Shein may still be one of the biggest names on the fast-fashion catwalk, but the IPO is going to be a harder sell, with plenty of investors questioning whether its low-cost formula still has the star power to deliver the growth they&rsquo;re looking for.&rsquo;&rsquo;</p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/trade-tensions--iran-sanctions-and-shien-ipo-under-pressure-27093.htm</link>
<pubDate>Mon, 24 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>The Summer Of 2026  Heatwaves  Wildfires And Droughts</title>
		<description><![CDATA[<p>Globally, droughts are becoming more frequent and severe, with research on the economic effects of extreme weather and natural disasters suggesting that droughts are increasingly damaging. The credit rating implications of climate hazards for most of the sovereigns that we rate remain limited, given the manageable costs at the sovereign level. Still, severe droughts affect agriculture, fluvial trade, industry, and energy generation, as the current drought in Europe is demonstrating.</p>

<p>Earlier this year, we introduced our Hazard Exposure Analytics and Trends (HEAT) dataset (Climate Risk Navigator - Physical Climate Risk Signals in Credit: Longitude, Latitude, and Exposure), showing how physical climate risk varies across locations, regions, and time horizons. In this commentary we look at the intensity of recent heatwaves and droughts, their potential economic impacts, and how the stacking of risks calls for further climate adaptation.</p>

<p><strong>KEY HIGHLIGHTS</strong></p>

<div><em>A series of climate hazards has stacked up this summer, with consecutive heatwaves and dryness leading to droughts in many parts of Europe.</em></div>

<div><em>The adverse impact of droughts on economic growth can be larger than other hazards. In Europe, the severe drought is affecting the farming sector, inland shipping, and energy generation.</em></div>

<div><em>In the long term, the economic impact of climate physical risks will largely depend on adaptation efforts and the path of climate change and weather patterns.</em></div>

<p>&quot;With climate hazards adding up and droughts becoming more frequent and costly, assessing the various economic effects, is crucial. Climate adaptation and preparedness will have to keep up with the intensity and frequency of climate hazards&quot;, <strong>said Adriana Alvarado, Senior Vice President in the Global Sovereign Ratings Group</strong>. &quot;In terms of the credit implications, for governments at various levels, we assess whether climate change and adverse weather events could potentially destroy a material portion of national wealth, weaken the financial system, or disrupt the economy&quot;.</p>

<p><a href="https://www.actuarialpost.co.uk/downloads/cat_1/Mornignstar_DBRS-The_Summer_of_2026.pdf">Morningstar DBRS Summer of 2026: Heatwaves, Wildfires and Droughts</a></p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/the-summer-of-2026--heatwaves--wildfires-and-droughts-27099.htm</link>
<pubDate>Mon, 24 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>What Could Pm Andy Burnham Mean For Markets And Your Pension</title>
		<description><![CDATA[<p>As Burnham hits the road for much of August, UK households face a far from settled economic backdrop. July inflation rose to 2.9%, retail sales fell 0.5% and government borrowing hit &pound;1.8 billion - &pound;2.3 billion above forecast. Meanwhile, geopolitical tensions and oil above $93 a barrel are adding to concerns about inflation and interest rates.</p>

<p><strong>Maike Currie, VP Personal Finance at PensionBee, comments: </strong>&ldquo;For pension savers, what happens in the economy and financial markets matters because your pension doesn&rsquo;t sit in a vault waiting for retirement - it is invested. Millions of workplace and personal pensions hold a mix of shares, bonds and other assets, so when markets move, pension values can move with them. While that can be unsettling in the short-term, volatility is part and parcel of investing. The long-term nature of pensions allows for volatility to be smoothed and your investment to grow.&rdquo; </p>

<p>With Burnham championing an economic philosophy he calls &ldquo;Manchesterism&rdquo; - described as &ldquo;business-friendly socialism&rdquo; and Chancellor John Healey&rsquo;s first Budget due on 28 October, investors are watching closely. Rising inflation, concerns about government borrowing and volatility in global bond markets have put the new Government&rsquo;s fiscal plans firmly in the spotlight.</p>

<p>So will Andy Burnham be bad for the stock market &ndash; and therefore impact for your pension savings?</p>

<p>PensionBee analysis of the FTSE 350 - representing 350 of the UK's largest listed companies - looked at its performance from Tony Blair's election in May 1997 to July 2026, shortly before Burnham entered Downing Street.</p>

<p>During that period Britain had eight Prime Ministers: three Labour and five Conservative. Despite changing political parties at the helm, political crises, recessions, wars, a global financial crisis and a pandemic, the overriding direction of the UK stock market over the period was upwards.</p>

<p>There were, of course, dramatic falls. Gordon Brown&rsquo;s premiership coincided with the global financial crisis. Boris Johnson was in Downing Street when Covid-19 sent global markets plunging. Tony Blair&rsquo;s time in office encompassed both the dot-com bubble and subsequent crash.</p>

<p>Those episodes demonstrate the danger of attributing stock market performance simply to the politician occupying No 10.</p>

<p>Even Liz Truss&rsquo;s disastrous 2022 Mini-Budget, which sent the pound tumbling and triggered turmoil in UK government bond markets, had a much less dramatic long-term impact on the UK stock market.</p>

<p><img alt="" src="https://www.actuarialpost.co.uk/images/pic_PensionBeeFTSE12408261.png" style="height:507px; width:600px" /></p>

<p><strong>Maike Currie, VP Personal Finance at PensionBee, comments:</strong> &ldquo;Prime Ministers come and go, but your pension will be invested for decades. It&rsquo;s important to remember that pensions are generally invested globally and across multiple asset classes, so returns can be influenced by everything from US interest rates and technology stocks to oil prices, wars and the wider global political and economic landscape.</p>

<p>&ldquo;Politics can move markets in the short term, but for pension savers, the bigger risk can be letting short-term political noise derail a long-term investment plan.&rdquo;</p>

<p>PensionBee&rsquo;s analysis of the S&P 500 over a similar period covers Democratic and Republican presidents including Bill Clinton, George W. Bush, Barack Obama, Donald Trump and Joe Biden.</p>

<p>Again, there were substantial crashes and periods of volatility, but the long-term direction was upwards - regardless of which party occupied the White House.</p>

<p><img alt="" src="https://www.actuarialpost.co.uk/images/pic_PensionBeeFTSE22408261.png.jpg" style="height:444px; width:570px" /></p>

<p><strong>Maike Currie, VP Personal Finance at PensionBee, comments:</strong> &ldquo;From AI bubble fears and conflict in the Middle East to higher oil prices, inflation and mounting government debt, there is plenty for investors to worry about. Markets can and do fall, but the bigger danger is turning short-term volatility into a long-term mistake.</p>

<p>&ldquo;Your pension may navigate several Prime Ministers, Budgets, recessions and market crashes before you come to retire. The lesson from nearly 30 years of market history is simple: your pension is likely to outlast the politicians making the headlines.&rdquo;</p>

<p>Five things pension savers can do when markets wobble</p>

<p><strong>1. Stay diversified</strong><br />
Spread your pension across different geographies, sectors and asset classes so you&rsquo;re not overly reliant on one market, economy or group of companies.</p>

<p><strong>2. Keep calm and keep contributing</strong><br />
If retirement is still years away, avoid knee-jerk decisions when markets fall. Continuing regular contributions means you will also buy more investments when prices are lower, potentially benefiting when markets recover. Pension tax relief can give contributions an additional boost even before investment returns are considered.</p>

<p><strong>3. Check your risk as retirement approaches</strong><br />
The closer you are to retirement, the less time you may have to recover from a market fall. Review how much investment risk you&rsquo;re taking and whether it still suits when and how you plan to access your pension.</p>

<p><strong>4. Give yourself a retirement buffer</strong><br />
If you&rsquo;re already drawing an income, avoid selling investments at depressed prices where possible. Holding an appropriate cash or lower-risk buffer, or drawing from other available income or assets instead, can give your investments time to recover.</p>

<p><strong>5. Remember that downturns don&rsquo;t last forever</strong><br />
Historically, rising markets have tended to last longer than falling ones, although there are no guarantees. Staying invested means you remain positioned to benefit from a recovery.</p>

<p><a href="https://www.pensionbee.com/uk/blog/bonus-episode-how-does-market-volatility-shape-your-pension-pot">More on how market volatility can shape your pension pot in this bonus episode of PensionBee&rsquo;s PensionConfident Podcast</a><br />
 </p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/what-could-pm-andy-burnham-mean-for-markets-and-your-pension-27095.htm</link>
<pubDate>Mon, 24 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Preparing For Unprecedented El Ni o This Autumn And Winter</title>
		<description><![CDATA[<div>Previous research conducted for the trade association by Opinium found that 1 in 4 (25%) UK adults don&rsquo;t know if their home is at risk of flooding and storm damage, and nearly half (45%) who had experienced flooding wish they&rsquo;d taken more steps to prevent or mitigate the damage.</div>

<div> </div>

<div>Last year, insurers paid out &pound;1.2 billion for damage to people&rsquo;s homes and businesses caused by extreme weather, with 46% of this paid in the second half of the year. </div>

<div> </div>

<div><strong>Regular maintenance can help people prevent damage and make their homes more resilient long term. If it is safe to do so, taking simple steps now can make a difference should a storm hit later in the year, such as:</strong></div>

<div><em>Unblocking gutters and drains</em></div>

<div><em>Checking roof tiles</em></div>

<div><em>Removing overhanging or loose branches of nearby trees</em></div>

<div><em>Identifying leaks by checking for puddles of water, discolouration or a change of texture in walls or ceilings, musty smells or signs of mould or mildew, and fix these early</em></div>

<div><em>Servicing your boiler annually and <a href="https://www.abi.org.uk/media-hub/news-post/dont-get-caught-out-in-the-cold-insurance-advice-from-the-abi">taking steps</a> to reduce the risk of frozen pipes  </em></div>

<div> </div>

<div><strong>With wet weather expected later this year, the ABI has also encouraged people to:</strong></div>

<div><em>Check the <a href="https://www.gov.uk/check-long-term-flood-risk">flood risk</a> in their local area</em></div>

<div><em>Sign up to <a href="https://www.gov.uk/get-flood-warnings">flood alerts</a></em></div>

<div> </div>

<div>To keep properties resilient to flooding, there are also a number of more substantial steps people can take if their property is at risk. For example, moving plug sockets higher up on walls, opting for tiles or waterproof flooring over carpet, and installing flood gates can all help to limit the damage from flooding and speed up the recovery process.</div>

<div> </div>

<div><strong>Chris Bose, Director of General Insurance and International Policy:</strong> While storms and flooding may be the last thing on people's minds after the heatwaves, the Met Office's warning of a wet and stormy season ahead is another reminder of how unpredictable and powerful our weather can be. Insurers are on hand to help people recover after extreme weather, but taking simple steps now can help reduce the risk of damage to homes and businesses.</div>

<div> </div>

<div>This upcoming Bank Holiday weekend is the perfect opportunity to get ahead of the bad weather and make sure your property is prepared. We also call on government to ensure stronger climate resilience measures are built into all new homes, helping to reduce the risk of damage and better protect communities in the long term.</div>

<div> </div>

<div> </div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/preparing-for-unprecedented-el-ni-o-this-autumn-and-winter-27101.htm</link>
<pubDate>Mon, 24 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Young Adults Increasingly Turning To Ai As A Sounding Board</title>
		<description><![CDATA[<div>AI is playing an increasingly influential role in the decisions young adults make, with new research revealing that almost half of Gen Z have changed their mind about a decision after consulting the technology.</div>

<div> </div>

<div>Almost half (48%) of Gen Z say AI has changed their mind about a decision, compared with just 5% of people from the Silent Generation (81+). The findings suggest AI is becoming an increasingly influential tool for younger adults as they explore options, weigh trade-offs and think through significant decisions.</div>

<div> </div>

<div>The research also highlights striking generational differences in attitudes towards the technology. More than half (55%) of Gen Z (18&ndash;29-year-olds) say they trust AI completely or somewhat and use it, compared with 18% of Boomers (62-80) and just 11% of people from the Silent Generation (aged 81+).</div>

<div> </div>

<div>People aged 18 to 29 are also significantly more likely to use AI when discussing personal concerns. Almost a quarter (24%) say they would feel comfortable discussing financial worries with AI, compared with just 5% of Boomers.</div>

<div> </div>

<div>The research was commissioned by pension provider Aegon as part of its Money:Mindshift campaign, which examines how people make decisions and navigate financial trade-offs in an increasingly complex world, particularly when planning for longer lives.</div>

<div> </div>

<div>The findings are consistent with recent research from Hopelab and the Center for Digital Thriving at Harvard Graduate School of Education, which found that some young people are increasingly turning to AI chatbots for advice, emotional support and guidance when weighing up decisions.</div>

<div> </div>

<div><strong>Dr Tom Mathar, head of Money:Mindshift at Aegon, said: </strong>&quot;The real story isn't whether people are using AI, it's how they're using it. What's particularly striking is that almost half of Gen Z say AI has changed their mind about a decision. For many younger adults, AI is becoming more than a source of information. It's increasingly a tool for exploring options, testing assumptions and thinking through important choices. One of the most valuable things AI can do is help us look at familiar decisions from a different perspective. That can be powerful, particularly when we're weighing complex financial trade-offs.</div>

<div> </div>

<div>&quot;Money decisions are rarely simple calculations. They involve trade-offs between competing priorities, both now and in the future. Our research suggests people are increasingly treating AI as a partner for thinking those trade-offs through. AI is excellent at surfacing information and challenging our assumptions, but it can only work with the information we give it. Many of life's biggest decisions are shaped by experiences, relationships and personal priorities that are difficult to capture in a prompt. AI only knows what you tell it, and a personal logic hardly transpires in a chat window.&quot;</div>

<div> </div>

<div>The subject is discussed further in the latest episode of <a href="https://www.aegon.co.uk/money-mindshift">Aegon's Money:Mindshift podcast</a>, How to think about AI, which explores these issues.</div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/young-adults-increasingly-turning-to-ai-as-a-sounding-board-27094.htm</link>
<pubDate>Mon, 24 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Two thirds Of Typical Pension Pot Is From Investment Growth</title>
		<description><![CDATA[<div>Nearly two-thirds of the value of a typical pension pot comes from investment growth, but three quarters (75%) of people don&rsquo;t realise it, according to new research from the retirement specialist Standard Life.</div>

<div> </div>

<div>Standard Life analysis of government figures highlights that, while contributions from individuals and employers form the vital foundation of pension saving, investment growth can play an even greater role over the long term. For a typical defined contribution pension pot of &pound;100,000, around two thirds of the total value (65% / &pound;65,000) comes from compound investment growth. Individual contributions account for &pound;18,000, employer contributions make up &pound;13,000, and tax relief adds &pound;4,000.</div>

<div> </div>

<div>Despite investment growth playing such a valuable role in terms of pension pot growth, many people are unaware of its significance in dictating the final pot. Only one in four (25%) people believe investment growth is the main driver of the final value of their pension pot. Instead, two fifths (39%) believe their individual contributions make the biggest difference, while a quarter (27%) point to employer contributions, and almost one in ten (8%) identify tax relief as the main driver.</div>

<div> </div>

<div><img alt="" src="https://www.actuarialpost.co.uk/images/pic_StandardLifeOverall12408261.png" style="height:149px; width:600px" /></div>

<div><span style="font-size:11px"><em>A pension is a long-term investment. Its value can go up as well as down and could be worth less than was paid in.</em></span></div>

<div> </div>

<div><strong>Time could be your pension&rsquo;s biggest advantage</strong></div>

<div>This misunderstanding comes as many people are delaying retirement planning altogether. Just 15% say they actively prioritise saving into their pension, while one in five (21%) admit they see retirement planning as something to worry about later. This rises to more than a third (35%) among Gen Z, despite younger savers potentially having the most to gain from giving their pension longer to grow.</div>

<div> </div>

<div>Someone who starts working on a salary of &pound;25,000 and pays minimum monthly auto-enrolment contributions (5% employee, 3% employer) from age 22 could build a total retirement fund of &pound;210,000 by age 68, adjusted for inflation3. Waiting just five years until age 27 to start contributing could result in a total pot of &pound;170,000, &pound;40,000 less, with the money having less time to realise compound investment growth.</div>

<div> </div>

<div><img alt="" src="https://www.actuarialpost.co.uk/images/pic_StandardLifeOverall22408261.png" style="height:195px; width:600px" /></div>

<div><span style="font-size:11px"><em>*assuming 3.50% salary growth per year, and 5% a year investment growth. Figures account for 2% inflation. Annual Management cost of 0.75%.</em></span></div>

<div> </div>

<div><strong>Jenny Holt, Customer Savings & Investment Director at Standard Life said: </strong>&ldquo;Compound investment growth can be one of the most powerful forces in pension saving, but our research suggests many people underestimate the role it plays. Contributions are important, but the real benefit often comes from giving those contributions time to grow and generate returns over decades.</div>

<div> </div>

<div>&ldquo;This is why starting early can make such a difference. Even modest contributions made earlier in your working life have longer to benefit from potential compound investment growth, while delaying saving can mean missing out on the years when your money could have been working harder for you.</div>

<div> </div>

<div>&ldquo;Of course, people need to balance pension saving with day-to-day costs and shorter-term goals, especially in the current high cost of living environment, but where finances allow, engaging with your pension early, checking what is going in, and making the most of any employer contributions available can help give investment growth the best chance to boost your retirement savings over time.&rdquo;</div>

<p> </p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/two-thirds-of-typical-pension-pot-is-from-investment-growth-27096.htm</link>
<pubDate>Mon, 24 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Actions Speak Louder Than Words</title>
		<description><![CDATA[<p>Although the case for a September hike remains strong, sequentially softer inflation data lessens the likelihood of it being delivered. For that reason, we have increased our scenario probability of &lsquo;Just right&rsquo; to 60%, which now becomes our base case, and have reduced the probability of our most hawkish &lsquo;Too hot&rsquo; scenario.</p>

<p><img alt="" src="https://www.actuarialpost.co.uk/images/pic_SchrodersAction2408261.jpg" style="height:238px; width:600px" /></p>

<p><span style="font-size:11px"><em>Source: Schroders Global Fixed Income team 14 August 2026 &ndash; Scenarios are framed around US Fed funds rates: Too Hot: +3 hikes, Warming up: +1-2 hikes, Just right: unchanged, Too cold: +1cut</em></span></p>

<p>Given our shift in probabilities, and with market pricing continuing to have a more hawkish skew than we do, we maintain our overweight score to global duration and upgrade the US to positive as we see less scope for underperformance here.</p>

<p>Events in the Middle East and the global energy outlook will remain key drivers, but valuations, in terms of outright global yields, are attractive.</p>

<p>Criticism of the last Fed meeting focussed on reduced forward guidance from new Fed chair Kevin Warsh. We disagree - we have no problem with reduced forward guidance. In fact, we endorse it. The quest for transparency often gives rise to information overload and false precision about inherently uncertain outcomes.</p>

<p>But we do believe that objectives must be explicit, even when reducing the level of guidance provided as to the tactics to achieve them. The last Federal Open Market Committee (FOMC) confused rather than clarified these objectives. Which measure of inflation is most important to judge underlying inflation? Over what time-horizon should inflation return to target? What level is acceptable &ndash; 2% exactly, or 2%-ish? Either answer is fine, ambiguity is not.</p>

<p>Greater clarity from the Fed chair would be welcome, sooner rather than later. Until then, however, we are taking a neutral view on the yield curve. A more proactive Fed with stronger inflation-fighting credibility is a necessary component for a curve-flattening view, and that has become more questionable for the time being.</p>

<div><strong>Who does &ndash; and doesn&rsquo;t &ndash; need hikes?</strong></div>

<div>Within our positive overall score for global duration, we have shifted our geographical preferences, with Canadian bonds joining their US neighbours in being upgraded.</div>

<p>While the Canadian labour market has stabilised, with unemployment no longer rising, and growth being fine, the core inflation outlook is inconsistent with any policy change by the Bank of Canada (BoC). Yet, the market prices the BoC to tighten policy further than almost any major central bank in the next 12 months, which we believe is unlikely to be realised, creating a compelling opportunity in shorter-dated bonds.</p>

<p>In the UK, although core inflation dynamics have recently been very favourable, our concern is that inflation is likely to increase towards year-end. This means we are less positive on UK gilts but continue to believe the Bank of England is unlikely to deliver the hikes priced by the market.</p>

<p>We downgrade Japanese bonds on our view that the Bank of Japan will need to more aggressively tighten policy, given the inflation outlook and failure of currency intervention to turn the tide for the yen. Until it grasps the nettle, we believe Japanese government bonds remain vulnerable.</p>

<div><strong>And finally &hellip;</strong></div>

<div>On asset allocation, the major change is an upgrade to Eastern European sovereigns, which remain our top pick. Despite the excellent performance by Hungarian bonds year-to-date, we see further upside given the totemic shift in political outlook since Peter Magyar&rsquo;s election victory. We believe the next catalyst for performance will be the new administration setting a path towards adoption of the euro currency. The criteria required for euro entry will require pragmatic economic and fiscal policy supportive of Hungarian bonds &ndash; both in hard (euro) and local currency.</div>

<p>Elsewhere, we observe rising political risks in both France and Italy ahead of elections in 2027, but believe current valuation levels compensate better for these risks in French rather than Italian government bonds, given that Italy now trades with lower yields than its neighbour. Quite the turnaround given Italy commanded nearly a 2% yield pick-up over France as recently as 2022.</p>

<p>Finally, across the board, we remain neutral on corporate credit. The story here is little changed: the macro backdrop is good; valuations are not.</p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/actions-speak-louder-than-words-27100.htm</link>
<pubDate>Mon, 24 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>A Path To Stronger Cyber Resilience</title>
		<description><![CDATA[<div>Cyberattacks are posing an ever-increasing challenge to organisations and the wider economy. A survey from the Department for Science, Innovation & Technology found that 43% of UK businesses experienced a cyber breach or attack in the previous 12 months. Separate research suggests nearly a third of CEOs now feel their organisations are highly exposed to major cyber-related financial loss in the year ahead.  Against this backdrop, the ABI has published <a href="https://www.actuarialpost.co.uk/downloads/cat_1/ABI-good-practice-guidance-cyber-resilience-july2026.pdf"><strong>From Prevention to Resilience: Good Practice Guidance on Cyber Resilience</strong></a>, developed with leading cyber insurers and government partners. The guidance is designed to help organisations of all sizes improve their cyber resilience. </div>

<div> </div>

<div>Drawing on insurers' experience and claims data, it identifies practical measures that can help organisations prevent attacks, reduce harm and recover more quickly when incidents occur. These include: </div>

<div> </div>

<div><em><strong>Regular staff training</strong> to help employees recognise and avoid common threats </em></div>

<div><em><strong>Reliable offline backups</strong> to ensure critical data can be restored as quickly as possible </em></div>

<div><em><strong>Clear incident response</strong> plans to enable faster, more coordinated action during an attack </em></div>

<div><em><strong>Multi-factor authentication</strong> to guard against unauthorised access to systems </em></div>

<div><em><strong>Good logging and monitoring</strong> to spot suspicious activity early </em></div>

<div><em><strong>Strong encryption</strong> to protect sensitive data </em></div>

<div><em><strong>Supplier and third-party checks</strong> to reduce the risk of attacks via external systems </em></div>

<div> </div>

<div>The guidance also highlights the role cyber insurance can play in strengthening resilience. Alongside financial protection, insurers increasingly provide services such as threat monitoring, incident response support and system recovery, complementing initiatives such as Cyber Essentials and the Cyber Resilience Pledge. </div>

<div> </div>

<div>Reflecting on this growing role, a <a href="https://www.actuarialpost.co.uk/downloads/cat_1/ABI-PwC-cyber-insurance-market-assessment-july2026.pdf"><strong>joint report from the ABI and PwC UK</strong></a>, published alongside the guidance, explores how cyber insurance has developed into a key tool for managing cyber risk. </div>

<div> </div>

<div>From novel ways to mitigate risk to advancing product design, the report highlights the cyber insurance market's ability to adapt and innovate to this evolving threat and meet growing demand. It also identifies opportunities to further strengthen its contribution to UK resilience.  </div>

<div> </div>

<div>Its recommendations include improving understanding of cyber insurance through clearer policy language and stronger distribution, aligning more closely with wider cyber resilience initiatives and regulation, enhancing data sharing to support better risk management, and encouraging organisations to invest in higher levels of cyber preparedness. </div>

<div> </div>

<div>Together, these findings reinforce the case for a more proactive approach to cyber resilience, helping organisations better withstand and recover from attacks. </div>

<div> </div>

<div><strong>Chris Bose, Director of General Insurance at the ABI:</strong> &quot;Cyber resilience is a shared challenge that cannot be solved by any one sector alone. Our report with PwC UK highlights the significant opportunity for cyber insurance to play an even greater role in supporting resilience across the UK, while our new guidance highlights practical actions businesses can take to better protect themselves. Realising that potential will require continued collaboration between insurers, businesses and government to strengthen preparedness and resilience.&quot; </div>

<div> </div>

<div><strong>Martin Murphy, Corporate Insurance Strategy Lead at PwC UK:</strong> &quot;As our report shows, cyber insurance is increasingly doing much more than paying claims. Insurers are helping organisations strengthen their defences, respond more effectively when incidents occur and recover more quickly afterwards. With cyber threats continuing to evolve, there is an opportunity for the market to play an even greater role in supporting resilience across the UK economy.&quot; </div>

<div> </div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/a-path-to-stronger-cyber-resilience-27091.htm</link>
<pubDate>Fri, 21 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>New Investment Paradigm  Navigating A World In Transition</title>
		<description><![CDATA[<p><strong>By Chris Redmond, Global Head of Manager Research, Martin Jecks, Senior Director and Multi-Asset Strategist and Chris Mansi, Chief Investment Officer, Europe and International, WTW</strong></p>

<p>Understanding what that shift means for capital markets, portfolio construction and the clients we serve is the defining investment challenge of our time. The transition to &ldquo;The New Paradigm&rdquo; presents challenges, but also opportunities.</p>

<div><strong>From neoliberalism to mercantilism: A structural rupture </strong></div>

<div>The neoliberal order gained prominence in the late 1970s and was built on globalization, liberalized capital flows and expanding trade, supported through the integration of emerging markets, fiscal discipline and the widespread introduction of independent central banks focused on price stability. Success of this model was underpinned by the exceptional performance of the U.S. economy and its singular role as the world's geopolitical hegemon, effectively creating &ldquo;a peace dividend&rdquo; that has supported global growth.</div>

<p>Over several decades, we have observed a growing number of challenges to the neoliberal paradigm &ndash; the return of China as a true global superpower and transition to a multipolar world, the displacement of parts of the labor force through globalization, waning trust in established institutions &ndash; although these slow-moving changes can get lost in the noise. But much like the fault line between tectonic plates, the surface may appear calm for extended periods belying the maelstrom of pressure building beneath. But after a while that tension becomes too great and we experience a rupture, an earthquake. We are now dealing with that earthquake as we transition to The New Paradigm.</p>

<p>In a world where the U.S. is no longer willing to underwrite the &ldquo;global order&rdquo; as it once did, and geopolitical risk remains structurally elevated, the role of the state is changing. We increasingly see countries seeking to provide greater support and investment to local energy infrastructure, strategic minerals, domestic supply chains and resource security. This reflects a motivation to align economic activity explicitly to national power and resilience.</p>

<div><strong>How this changes investment approach and portfolio construction</strong></div>

<div>The investment implications of this transition do not all point in the same direction. That complexity is, itself, the challenge.  Things are pulling us in different directions. We need to prepare for different scenarios, but we also need to be careful not to interpret elevated geopolitical risk, or elevated risk more generally as a signal to become defensive too early. The instinct to reduce equity exposure when there is bad news aplenty and valuations look stretched on conventional metrics can be costly if applied too simplistically. We believe there are several implications for portfolio strategy and approach, as reflected in the &ldquo;three Rs&rdquo;</div>

<p><strong>Reactivity: </strong>What we are experiencing is not episodic volatility but higher systemic risk. These episodes are linked, and their frequency is likely to increase over time. More scenario testing, greater use of pre-mortems and a clear-eyed view of mission failure for each client are required. Portfolios and governance structures must be capable of responding quickly to new information, through high-quality data flows, clear decision-making processes and sufficient liquidity to act when circumstances change.</p>

<p><strong>Resilience:</strong> In a world where equity-bond correlations may remain positive for longer, the traditional equity-and-bond portfolio loses a core structural advantage. Downside protection needs to be rebuilt on different foundations. Longer-horizon investors also need greater openness to high-volatility, high-skew strategies that can deliver the sustained returns required to meet long-run missions.</p>

<p><strong>Renewed belief in active management and alternatives:</strong> The new environment also renews the case for active management. Alpha generated through manager skill is likely to become a more valuable component of portfolios than it has been in recent years, when all you needed to do was put money in equity markets. Infrastructure, hard assets and private markets carry renewed importance, both as sources of structural return and as assets harder to erode through inflation or geopolitical disruption. We also see a number specific portfolio-relevant implications, including:</p>

<p><strong>Two-sided risk for inflation and interest rates</strong><br />
Large trade shifts are here to stay, but their inflationary impact is uncertain. China's continued success in growing high-value exports, now accounting for around 40% of global electric vehicle exports, for example, illustrates that deglobalization does not automatically mean higher prices everywhere. We see similar phenomena to the downside, as prior disinflationary forces appear to be weakening, all of which support our view that we need to prepare for more two-sided outcomes for inflation and interest rates going forward, rather than the largely one-way path lower over the last 40 years.</p>

<p><strong>There are strong tailwinds for real assets and some commodities</strong><br />
There is an almost existential need for greater investment in defense, energy and resources by many countries &ndash; a structural, multi-decade opportunity. Whether some nations go further by restricting or redirecting foreign capital remains uncertain, but it's got to be higher risk than it was.</p>

<div><strong>Technology and artificial intelligence (AI): Opportunity, uncertainty and recalibrated risk </strong></div>

<div>The other structural transition in the world comes from technology, where AI is reshaping the productive potential of the global economy at a pace and scale that demands serious attention. Based on McKinsey estimates, we consider it plausible that between $5 trillion and $8 trillion of AI-related capital expenditure is deployed over the coming years, equivalent to between 15% and 25% of U.S. GDP</div>

<p>The implications for capital markets and investment strategy remain complex, however in our mind there are clear conclusions and opportunities:</p>

<p>Technology sector equity valuations are elevated, reflecting a combination of strong growth and future expectations. We do not believe this is currently in &ldquo;bubble&rdquo; territory, however as strong earnings expectations stretch far into the future, this effectively increases sensitivity to interest rate changes compared with recent decades.The significant capex spend is reflective of race towards recursively self-learning artificial intelligence, growing market share and significant revenue growth. The result is winner-takes-all dynamics and an urgency of investment that have few historical precedents, but nonetheless an environment where active management is likely to be well rewarded.Our view is that AI will ultimately be deeply disinflationary and that productivity gains will be significant and lasting. But the path there is uncertain, the near-term capex surge may prove inflationary before that dividend is realized. Combined with geopolitical forces, this reinforces a central conclusion: inflation and interest rate risks are now genuinely two-sided. </p>

<div><strong>The opportunity in uncertainty </strong></div>

<div>The newsreel can make it easy to reach a negative conclusion. Most articles in the financial press are about the next bubble, the next crisis. But that's not our central view. </div>

<p>The structural transition underway creates genuine opportunities, in infrastructure, active management, private markets and the new choices available to clients.</p>

<p>Navigating them requires portfolios built for resilience, informed by clear analysis of what is knowable and what is not, and grounded in an honest reckoning with what risk really means for each investor. </p>

<p>The paradigm has shifted. The task now is to thrive in it.</p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/new-investment-paradigm--navigating-a-world-in-transition-27092.htm</link>
<pubDate>Fri, 21 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Iht And Cgt Both Remain Elevated</title>
		<description><![CDATA[<p><strong>Simon Martin, Head of UK Technical Services at Utmost, commented: </strong>&quot;Albeit down on last month, Inheritance Tax revenues remain well above historical levels, reflecting the continued impact of frozen thresholds alongside rising asset values, which are bringing more families within scope of the tax. The scope of Inheritance Tax continues to widen, with the threshold freeze extended until 2031, reforms to Business Property Relief taking effect in April this year, and unused pension pots due to come within the scope of IHT from April 2027. While these changes may increase tax revenues in the short-term, it raises wider questions about the UK&rsquo;s attractiveness to entrepreneurs and wealth creators who are more internationally mobile than ever, particularly when other jurisdictions offer significantly more competitive tax regimes.&rdquo;</p>

<p>&quot;CGT receipts remain elevated following a record year for the Treasury, with higher rates introduced at the Autumn Budget 2024 and the fiscal drag drawing ever more individuals into the CGT net. While the OBR forecasts CGT tax receipts to make even larger contributions for the Treasury in the coming years, the increasing tax burden on gains from investments, property and business assets risks making the UK less attractive to internationally mobile investors, entrepreneurs and business owners, particularly when other jurisdictions are offering more favourable tax regimes.&rdquo;</p>

<p> </p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/iht-and-cgt-both-remain-elevated-27089.htm</link>
<pubDate>Fri, 21 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Bond Turmoil  Debt Worries And The Squeezed Retail Consumer</title>
		<description><![CDATA[<p><strong>Susannah Streeter, Chief Investment Strategist, Wealth Club: </strong>&lsquo;&rsquo;Investors are wary at the end of the week, amid a fresh surge in government borrowing costs, as efforts to intervene in bond markets by the Trump administration failed to have their desired effect. The FTSE 100 is set for a flat start as a wait and see mood percolates and the latest retail sales figures are assessed. It&rsquo;s clear that consumers are less confident, reining in purchases as higher bills land. The latest snapshot of retail sales showed, as expected, a drop in July, as the jump in the energy price cap pushed up household costs and shoppers grew weary under the intense heat. Trips to high streets as temperatures rocketed were a turn off, and there was even less browsing online amid the hot weather bomb as people sought to cool off in the shade. It also seems that promotions in June, sucked in sales, leading to a vacuum in July, with discretionary items like furniture and footwear particularly hard to shift. Nice to have but not essential expenditure falls by the wayside when consumers are facing an uphill climb to stick to budgets. The feel good factor around the World Cup did help give some lift to food sales, but the picture painted in this snapshot is of a less resilient consumer, particularly given the 1% uplift in sales in June, being revised down to 0.7%.</p>

<p>Higher energy costs are keeping up the inflationary pressures with Brent crude staying above $93 a barrel, up more than 5% this week. The US-Iran conflict shows no sign of abating, with the standoff over the Strait of Hormuz keeping a hefty risk premium baked into oil prices, while disruption to Russian energy infrastructure is adding another layer of uncertainty. With energy prices feeding through into transport, heating and the cost of goods, a sustained rise in crude could make the inflation battle even more difficult.</p>

<p>The turmoil in the debt markets continues despite efforts to calm feverish borrowing costs. US Treasury Secretary Scott Bessent tried to throw cold water onto hot government bond yields by doubling the size of planned Treasury buybacks, but it&rsquo;s not touching the sides of the deep-seated problem. Investors remain concerned about inflationary risks and the growing mountain of government borrowing, while at the same time, debt being issued by tech giants building out the AI revolution is offering stiff competition. Given the high ratings on the corporate bonds being pumped out by the hyperscalers, more capital has another attractive destination beyond Treasury markets, adding to the pressure on government debt. Higher yields are also giving equities a run for their money, with investors seeking out more stable returns compared to the risks inherent in equity markets, given the mega valuations out there.</p>

<p>The yields on long-dated Treasuries are back above 5.3%, having dipped on Thursday. Thirty-year gilt yields have been hovering around 5.8%, as concerns continue to swirl about the UK&rsquo;s fragile fiscal position. The latest snapshot of UK government borrowing won&rsquo;t do much to assuage fears that Britain is living beyond its means. Borrowing came in at &pound;1.8 billion in July 2026, which was &pound;0.7 billion more than in July 2025, and &pound;2.3 billion above the Office for Budget Responsibility&rsquo;s forecast. Even though the amount the Exchequer is pulling in through higher taxes grew, helped by a strong influx of self-assessed income tax revenue payments, it&rsquo;s being outpaced by spending on public services, benefits and debt payments. Although debt interest costs were lower than in recent months, they are stubbornly higher than a year ago, which is keeping the new Prime Minister in a highly tricky position. It comes at a time when Andy Burnham is under pressure to deliver more meaningful support to households facing a cost-of-living squeeze, but he&rsquo;s still operating under the highly watchful eye of the bond market. This is the latest borrowing data to arrive under new Chancellor John Healey&rsquo;s watch and it is likely to lead to difficult decisions at the Treasury. Signs of greater profligacy with taxpayers&rsquo; money could set off another spiral higher in borrowing costs, limiting available funds even further, given the eye-watering cost of servicing the debt.&rsquo;&rsquo;</p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/bond-turmoil--debt-worries-and-the-squeezed-retail-consumer-27090.htm</link>
<pubDate>Fri, 21 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Airport Anxiety Searches Up 250  What To Check Before Flying</title>
		<description><![CDATA[<p>Around two-fifths (41%) of Brits who changed their holiday plans this year did so by shifting their travel dates. Among key factors for these changes were worries over airport disruption and international crises.</p>

<p><strong>Rhys Jones, travel insurance expert at Go.Compare, said:</strong> &quot;Travel anxiety is genuinely reshaping how Brits holiday in 2026. Gatwick alone expects 900 or more flights on its peak August days this summer. And the most practical antidote to travel stress isn't avoiding disruption - it's knowing exactly what you're entitled to claim when it happens. A few minutes spent checking your policy before you leave could save you hundreds if things go wrong.&quot;</p>

<p>One million more passengers flew through UK airports in Q1 2026 compared to the same period last year, putting more pressure on already stretched infrastructure.</p>

<p>Gatwick is the UK's most stressful summer airport, with an average departure delay of over 31 minutes, and the likelihood of experiencing a flight delay on any given journey is as high as 37%.</p>

<p><strong>Rhys has shared his top tips on how to reduce travel anxiety before you fly:</strong></p>

<div><strong>1. Know your airport - and build in extra time</strong></div>

<div>Not all airports carry the same disruption risk. With one million more passengers flying through UK airports this year than last, congestion is only increasing. Knowing your airport's track record before you travel changes how much buffer time to build in, and whether your travel insurance is adequate for the journey ahead.</div>

<div> </div>

<div><strong>2. Check what your travel insurance covers before you leave - not after</strong></div>

<div>Standard travel insurance typically pays out for reasonable expenses including food and drink after a two-hour delay, but most travellers only discover this after they've already spent money at the airport without keeping receipts. Documentation matters: without written confirmation of a delay from the airline and receipts for any expenses, a valid claim can be difficult to process. Check your policy before you go and keep your insurer's contact details saved on your phone.</div>

<div> </div>

<div><strong>3. Check the FCDO advice for your destination</strong></div>

<div>Checking Foreign, Commonwealth and Development Office travel advice before departure is one of the most skipped pre-travel steps. Yet travelling against official FCDO advice voids travel insurance entirely, not just for issues related to the warning but for every aspect of the trip. With bank holiday destinations potentially affected by ongoing travel advisories, this is worth making a pre-departure habit.</div>

<div> </div>

<div><strong>4. Don't assume cancellation cover only applies if you cancel</strong></div>

<div>Some travellers assume cancellation cover only kicks in if they cancel - not if the airline does. Travel insurance often covers additional costs when an airline significantly changes or cancels a flight, including overnight accommodation if a passenger is stranded. With 27% of Brits already having changed their plans this year due to disruption concerns, checking whether a policy includes airline cancellation cover is more important than ever.</div>

<div> </div>

<div><strong>Rhys added: </strong>&quot;Before you head to the airport this bank holiday, check whether your policy covers delays and what the threshold is, whether you'd be covered for overnight accommodation if your flight was cancelled, and whether the FCDO has issued any advice for your destination. If you haven't compared your travel insurance recently, now is the time to do it.&quot;</div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/airport-anxiety-searches-up-250--what-to-check-before-flying-27087.htm</link>
<pubDate>Thu, 20 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Draft Framework For Unlocking Db Scheme Surplus Welcomed</title>
		<description><![CDATA[<div>The SPP supports the use of a low dependency funding basis as the minimum funding test and believes decisions on the level of surplus released should remain with trustees, taking account of scheme-specific circumstances and covenant strength. However, the SPP is calling for changes to make the regime more practical, particularly for schemes intending to remain on a long-term run-on basis. It believes the proposed process is geared towards one-off payments and could make regular or phased distributions unnecessarily burdensome.</div>

<div> </div>

<div>The SPP is also seeking greater flexibility around the payment process, including allowing trustees to release less than the provisional amount without restarting the process, and extending the proposed five-working-day period between actuarial certification and payment.</div>

<div> </div>

<div>The SPP believes the proposed three-year forward-looking actuarial test should also be refined to reduce uncertainty and avoid disproportionate costs. It is recommending wording more closely aligned with existing actuarial certification requirements.</div>

<div> </div>

<div>The SPP also highlights the need to align pensions and tax legislation for segregated schemes, where current uncertainty could delay legitimate surplus returns.</div>

<div> </div>

<div><strong>Jon Forsyth, Chair of the SPP&rsquo;s DB Committee, said: </strong>&ldquo;The SPP welcomes the Government&rsquo;s proposals, which at a high level provide a sound framework for well-funded DB schemes to make productive use of surplus while protecting members. However, the regime needs to work effectively in practice. Greater flexibility around regular and phased payments, the actuarial tests and payment timetable would help ensure the new framework delivers its intended benefits without creating unnecessary governance burdens or other unintended consequences.&rdquo;</div>

<div> </div>

<div><a href="https://the-spp.co.uk/document/the-spp-response-to-the-dwp-consultation-surplus-flexibilities-for-defined-benefit-pension-schemes-unlocking-value-for-employers-and-scheme-members/">The SPP&rsquo;s consultation response is available here:</a></div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/draft-framework-for-unlocking-db-scheme-surplus-welcomed-27088.htm</link>
<pubDate>Thu, 20 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Tinkering With Treasuries Calms Bond And Equity Markets</title>
		<description><![CDATA[<p><strong>Susannah Streeter, Chief Investment Strategist, Wealth Club: </strong>&ldquo;Trump&rsquo;s tinkering with Treasuries has calmed bond and equity markets, for now, but fundamental pressures remain, with the US national debt reaching record levels and inflationary pressures still bubbling. Indices in Asia have clawed back some losses, but London&rsquo;s FTSE 100 is flat as investors adopt a wait-and-see mode to assess how successfully this operation can calm nerves.</p>

<p>The major Treasury buyback intervention was launched after a feverish jump in long-dated debt yields, which was making the US debt mountain even more expensive to maintain. It was also threatening to push up the price of borrowing for companies, given how loans are linked to bond market movements. America&rsquo;s national debt has more than doubled in a decade to reach $40 trillion dollars, just as the war with Iran has pushed up energy costs and threatens to spill over into knock-on price rises for goods and services. Brent crude, the benchmark, is still hovering around $91 a barrel as the Middle East situation remains at a stalemate.</p>

<p>So, the Treasury Department will at least double the size of its liquidity-support buyback operations for longer-dated debt from $2 billion to $4 billion per operation, between September 9 and November 4. The move has helped settle nerves, with the 30-year Treasury yield easing back to around 5.18%, after hitting a 19-year high of 5.34% earlier this week, while the 10-year yield has also pulled back.</p>

<p>But this could prove to be a sticking plaster which could be rapidly ripped off, given that bond vigilantes are on such high alert. The Treasury says the move is designed to provide greater liquidity support to the longer end of the market, and that can help dampen volatility and bring borrowing costs down in the short term. But it does not change the fundamental picture of rising government debt, persistent deficits and inflationary pressures.</p>

<p>And the latest minutes from the Fed show increasing wariness about those inflation risks. Several policymakers indicated they were prepared to raise rates if inflation fails to move down towards the 2% target, with many saying higher borrowing costs could ultimately be needed to prevent price pressures becoming entrenched. They are particularly concerned about energy prices and developments in the Middle East, while there are also worries that the huge investment boom in AI could keep inflation elevated through higher demand for chips, electricity and other infrastructure. But the same Fed minutes showed risks to employment and growth are viewed as being skewed to the downside. And the latest jobs figures will reinforce this concern, which is why policymakers may resist slamming on the brakes and opting for immediate rate hikes, given the weakening US labour market, with payrolls falling unexpectedly by 23,000 in July. So the Fed is caught between a rock and a hard place, with inflation risks picking up just as the labour market is weakening. The spectre of stagflation is hovering, with weaker growth, a softer jobs market, high government borrowing and renewed inflationary pressures.</p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/tinkering-with-treasuries-calms-bond-and-equity-markets-27084.htm</link>
<pubDate>Thu, 20 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Beware Of Risky Mini bonds And Loan Notes</title>
		<description><![CDATA[<p>The recent failure of Woodville Consultants Ltd, a litigation funder that raised capital from retail investors through unregulated loan notes, shows the potential risk to investors. </p>

<p>A loan note or mini-bond usually involves lending money to a company for a set period in return for interest. If that company fails, consumers could lose every penny. </p>

<p>The FCA permanently <a href="https://www.fca.org.uk/publications/policy-statements/ps20-15-high-risk-investments-marketing-speculative-illiquid-securities-speculative-mini-bonds-retail-investors">banned the marketing of speculative illiquid securities</a>, including mini-bonds and loan notes, to retail investors from 1 January 2021.  </p>

<p>But consumers may still come across adverts for loan notes and mini-bonds in everyday places, including social media, online adverts or websites promoting high fixed returns. </p>

<p>The adverts can look simple and safe, but <a href="https://www.fca.org.uk/news/statements/unregulated-loan-notes-mini-bonds-dont-risk-savings-promises-high-returns">warning signs</a> include pressure to act quickly, unclear explanations of how money could be lost, or claims that an investment is &ldquo;asset-backed&rdquo; without clear evidence of what stands behind it.  </p>

<p><strong>Examples of the practices the FCA sees include: </strong></p>

<div><em>Unregulated introducer firms passing consumers on to unregulated companies offering high-risk investments often taking a large fee, or commission, so reducing their initial investment </em></div>

<div><em>Consumers encouraged to certify themselves as experienced or wealthy investors to enable investments to be promoted to them </em></div>

<div><em>Firms promoting high-risk investments without the permission they need </em></div>

<div><em>Unclear fees or hidden conflicts, where those selling the investment may benefit from consumers investing </em></div>

<div><em>Scammers seeking to add &lsquo;halo&rsquo; associations to infer legitimacy; whether that be listing on overseas exchanges, or highlighting an FCA regulated firm being involved in the wider administration </em></div>

<div><em>Using trust structures or other arrangements to try to stay outside FCA rules </em></div>

<p><strong>Lucy Castledine, director of consumer investments at the FCA, said: &quot;</strong>Big, fixed returns are a warning sign, not a guarantee. Loan notes, mini-bonds and other speculative illiquid securities are high-risk investments and are not suitable for most people. Ordinary retail investors should only invest through regulated firms because if they invest through an unauthorised firm, they may have little or no protection if things go wrong. We are working hard to prevent harm, but consumers should still stop and check before investing.&rdquo; </p>

<p>The FCA encourages anyone involved in distributing or funding high-risk investments to report anything suspicious. This includes regulated firms, banks, payment firms, lawyers, accountants and auditors who may be involved in getting these investments to consumers. </p>

<p>The FCA has issued more than 1,200 warnings so far this year, told firms to stop unlawful promotions and referred cases to other law enforcement agencies where further action may be needed. </p>

<p>But scams can be complex, fast-moving and hard to stop, especially when run from overseas or designed to avoid regulation.  </p>

<p>To address the harm, regulated firms like banks and payment providers, regulators, government and law enforcement need to continue to work together. </p>

<p>Consumers need to be alert to the risk of harm and protect themselves using the tools available, like the <a href="https://www.fca.org.uk/consumers/fca-firm-checker?gclsrc=aw.ds&gad_source=1&gad_campaignid=23496358516&gbraid=0AAAAADSFwvxuw0n8BcwWzhhMixzAtEk2M&gclid=Cj0KCQjw-frTBhCvARIsADv4XY5vV1nhR9zVGe9aDJLf0p-M-4JeHuzarwkNTvomiOi_hrR8RdpxCOkaAhcrEALw_wcB">FCA&rsquo;s Firm Checker. </a></p>

<p>Consumers can help too by reporting any concerns to the FCA if they see a suspicious investment or think they&rsquo;ve been contacted by a fraudster or unauthorised firm. </p>

<p>Notes to Editors </p>

<div><em>In its <a href="https://www.fca.org.uk/publications/corporate-documents/fca-perimeter-report">Perimeter Report</a>, the FCA has called on the government to review the legislative exemptions that can mean certain high risk investments can be promoted outside FCA regulation.</em></div>

<div><em>Investors in mini-bonds or loan notes are unlikely to be able to refer their complaints to the Financial Ombudsman Service or claim for losses through the Financial Services Compensation Scheme if things go wrong, unless they dealt with an authorised person and the complaint relates to a regulated activity.</em></div>

<div><em>Since January 2026, a new regime regulating offers of securities to the public came into force. Read <a href="https://www.fca.org.uk/news/news-stories/new-regime-securities-consumers">more information</a> about what this regime means for consumers and what they should look out for.</em></div>

<div><em>Robert Goodhew and Andrew Stoneman of Kroll Advisory were appointed as joint administrators of Woodville Consultants Limited on 16 July 2026. Enquiries should be made via woodville@kroll.com. </em></div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/beware-of-risky-mini-bonds-and-loan-notes-27085.htm</link>
<pubDate>Thu, 20 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>M g Complete  85m Bpa Plus Transaction For The Altro Pension</title>
		<description><![CDATA[<p>This deal was completed through M&G&rsquo;s innovative &lsquo;BPA Plus&rsquo;1 proposition in April 2026. &lsquo;BPA Plus&rsquo; combines the security and certainty that a traditional BPA can provide with the opportunity for members to benefit from potential future investment outperformance. By combining the two with the scale of M&G&rsquo;s &pound;132bn With-Profits Fund, it enables schemes to secure members&rsquo; core benefits while also sharing in the potential for discretionary bonuses over time. </p>

<p>The Trustees selected M&G following a competitive process, citing its financial strength, proven track record and the flexibility of its BPA Plus proposition. The deal also marks the first use of Aon and Eversheds Sutherland&rsquo;s Pathway platform with M&G, helping to create a more streamlined approach for future business. Aon provided broking, investment and actuarial advice, while Pinsent Masons and Eversheds acted as legal advisers to the Trustees.</p>

<p>M&G is a founding member of the BPA market with over 25 years of experience implementing and administering bulk annuity transactions, backed by a robust balance sheet and a firm commitment to meeting our customers&rsquo; needs. Building on the launch of BPA Plus, a key differentiator for M&G in the market, the business expects to achieve &pound;3&ndash;&pound;4 billion of annual BPA sales by 2027.</p>

<p>This transaction was executed by the Prudential Assurance Company Limited (&ldquo;Prudential&rdquo;), M&G&rsquo;s wholly owned subsidiary providing life and pensions solutions.</p>

<p><strong>Rosie Fantom, Head of Bulk Annuity Origination & Execution at M&G, said:</strong> &ldquo;We&rsquo;re pleased to support Altro and the Trustees in securing the long-term future of their 740 members. This transaction highlights the value of &lsquo;BPA Plus&rsquo;, combining the security of a bulk annuity with the potential to offer greater outcomes over time. It&rsquo;s a strong example of how we can work with trustees and their advisers to deliver practical, member-focused outcomes, and we look forward to continuing to support the scheme in the years ahead.&rdquo;</p>

<p><strong>Andrew Elliott, Chair of the Trustees, and representing ZEDRA said:</strong> &ldquo;Protecting our members&rsquo; benefits has always been the key objective for both the Trustees and Company, and we&rsquo;re proud of the way that we have worked together to achieve long-term security for our members through the transaction with M&G &ndash; made possible by strong collaboration between all of our advisers. The potential for additional benefit to our members in future on top of the insurance regulatory framework, through M&G&rsquo;s innovative &lsquo;BPA Plus&rsquo; offering, is further upside.&rdquo;</p>

<p><strong>Joanna Davies, Senior Consultant and Risk Transfer Adviser at Aon, said:</strong> &ldquo;This transaction was efficient throughout but made even more so by the use of our &lsquo;Pathway&rsquo; approach, agreed with M&G for the first time. This will also pave the way for more schemes to benefit from our streamlined process. In this case, it enabled us to move swiftly for the Trustees and complete a quick execution, securing a favourable outcome to the benefit of the members.&rdquo;</p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/m-g-complete--85m-bpa-plus-transaction-for-the-altro-pension-27086.htm</link>
<pubDate>Thu, 20 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Broadstone Appoint Head Of Insurance Advisory   Remediation</title>
		<description><![CDATA[<div>A senior industry figure, Matthew brings deep practitioner expertise delivering client-centric solutions across the insurance market and is a key hire to support Broadstone&rsquo;s ambitious growth plans during a period of ongoing investment.</div>

<div> </div>

<div>Matthew&rsquo;s appointment enables Broadstone to expand its offering, especially across the pension risk transfer market, building on the acquisition of ExactVAL in 2025, and broaden its footprint in insurance technology as well as in the Lloyd&rsquo;s and London markets.</div>

<div> </div>

<div><strong>Matthew Ford, Head of Insurance Advisory & Remediation at Broadstone, commented:</strong> &ldquo;Broadstone already has a strong reputation in the insurance industry but there is a significant opportunity to spearhead further growth as the business continues to invest in its differentiated proposition. I am delighted to be joining at this time and will use my experience working at both consultancies and insurance firms, to bring a strong market focus and deliver bespoke, client-relevant solutions as we expand our insurance sector business.&rdquo;</div>

<div> </div>

<div><strong>Tony Gusmao, CEO of Broadstone, added:</strong> &ldquo;Matthew&rsquo;s appointment to lead our growing Insurance Advisory & Remediation division reflects our continued investment in the strategically important insurance market. He has a great pedigree with significant practitioner experience in insurance which will be critical as we continue to scale Broadstone&rsquo;s footprint in this market.&rdquo;</div>

<div> </div>

<div>Matthew&rsquo;s appointment follows the strategic growth investment made in Broadstone by Lovell Minnick Partners (announced on 7 January 2025) to accelerate the expansion of its capabilities &ndash; particularly in its Insurance Advisory & Remediation unit.</div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/broadstone-appoint-head-of-insurance-advisory---remediation-27077.htm</link>
<pubDate>Wed, 19 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Stars Of The Future 2026   Nominate Now </title>
		<description><![CDATA[<p style="text-align:center"><a href="https://apawards.co.uk/stars-of-the-future/"><img alt="" src="https://www.actuarialpost.co.uk/images/pic_SOTF2026Nominations.jpg" style="height:250px; width:250px" /></a></p>

<p>After 13 years this award has grown in popularity and enjoyment. A wonderful opportunity to pause and recognise all the hard work and talent within the actuarial market. The winner will grace the cover of our winner&rsquo;s magazine and two runners-up will also receive an award and all finalists are celebrated. Who do you think has worked exceptionally hard this year or achieved something great? Who do you think will be making an impact on the market in five years&rsquo; time.</p>

<p><strong>Antony Buxton FIA, Managing Director, Star Actuarial Futures Limited:</strong> Star Actuarial is again delighted to support and champion the Stars of the Future award. The world (of actuaries) continues to be transformed by (amongst other things) AI, demographic change, climate risk, digital-first customers, data-driven personalisation and regulation.</p>

<p>Against this backdrop, there is significant opportunity for actuaries to make the world a better place. This award is a chance to celebrate the early-career actuaries who are already making a real difference, and indeed any actuary about to set the world alight in a pioneering area of actuarial work.</p>

<p>We can&rsquo;t wait to hear about the contributions of all of the nominated candidates. Good luck to everybody!</p>

<p><a href="https://apawards.co.uk/stars-of-the-future/"><strong>You can now nominate someone for Stars of the Future 2026 here</strong></a></p>

<p><strong>Paul Ring, Stars of the Future 2025 winner: </strong>Honestly, I couldn&rsquo;t believe that I was nominated for this award, and winning it is an even bigger surprise. I&rsquo;ve never been nominated for an award like this before, so it genuinely caught me off guard in the best possible way. I&rsquo;m incredibly thankful to those who put my name forward for this award and to everyone who voted for me.</p>

<p style="text-align:center"><a href="https://library.myebook.com/ActuarialPost/actuarial-post-november-2025-sotf/6355/#page/1"><img alt="" src="https://www.actuarialpost.co.uk/images/pic_APMagazineSOTFNOVEMBER2025.jpg" style="height:281px; width:199px" /></a><br />
 </p>

<p style="text-align:center"> </p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/stars-of-the-future-2026---nominate-now--27083.htm</link>
<pubDate>Wed, 19 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>7 In 10 Insurance Flood Claims Linked To Flash Flooding</title>
		<description><![CDATA[<p>Using LexisNexis&reg; Precision Claims, the market&rsquo;s first cross-market insurance claims contributory database, the analysis reveals key insurance claims trends pertaining to surface water flooding and river flooding:</p>

<div><em>70% of U.K. home insurance flood claims relate to surface water flooding caused by intense rainfall and flash flooding.</em></div>

<div><em>90% of U.K. surface water claims are valued at less than &pound;5,000. </em></div>

<div><em>Fewer than 5% of U.K. surface water claims exceed &pound;25,000.</em></div>

<div><em>Approximately 31% of flood claims occur during the summer months (July-August), broadly in line with winter (32%) and autumn (30%).</em></div>

<div><em>Storm Babet was excluded from the analysis due to its exceptional impact on October 2023 claims volumes.</em></div>

<div><em>More than 90% of summer flood claims result from surface water flooding, compared with approximately 55% in winter and 75% in autumn.</em></div>

<p>In contrast, river flooding is much less frequent but much more severe when it does occur, equating to double the severity of surface water flooding. In addition, 30% of flood claims are from rivers breaking their banks, and 12% of these claims are over &pound;25k in value.</p>

<p>By contrast, river, or fluvial, flooding accounts for 30% of flood claims, making it far less common than surface water flooding. However, when river flooding does occur, it is twice as severe, with 12% of claims exceeding &pound;25,000.</p>

<p>The analysis, using LexisNexis&reg; Precision Claims, offers new insight into the insurance sector&rsquo;s experience with surface water flooding claims vs. river flooding claims. Distinguishing surface water risk from river, or fluvial, flood risk at the individual property level is becoming increasingly critical for insurance premium pricing, underwriting decisions and property flood risk assessment.</p>

<p>According to the U.K.&rsquo;s National Housing Federation using Environment Agency data, eight in ten homes now classified as high-risk of flooding are in England's towns and cities &mdash; equivalent to 839,000 homes. Separately, the organisation found that the number of properties at risk from surface water flooding has tripled since 2018.</p>

<p>Long periods of heat can leave soil dry and less able to absorb sudden heavy rainfall, increasing the likelihood of surface water flooding. Following June heatwave conditions that saw record temperatures[iii], the country experienced severe thunderstorm activity, and flash flooding disrupted the capital's transport network, including a section of the Elizabeth Line. In London and cities such as Brighton, basements represent one of the biggest risks to insurance providers from flash flooding.</p>

<p><strong>Caroline Elliott-Grey, senior product manager, U.K. and Ireland insurance, LexisNexis Risk Solutions, says:</strong> &ldquo;While these statistics are from home claims, they may shed some light onto commercial property risk as well, especially as we head into a softer market. A property exposed primarily to surface water risk presents a very different claims profile to one exposed to river flood risk. Treating these as a single undifferentiated &quot;flood risk&quot; category can create opportunities for mispricing and poor portfolio management at exactly the moment climate volatility is accelerating.</p>

<p>&ldquo;With a more comprehensive view of the market&rsquo;s claims experience through LexisNexis&reg; Precision Claims, insurance providers can look at flood scoring and explicitly factor in flood risk type when assessing risk, along with additional factors such as the presence of a basement or the elevation of the property. These insights can help insurance providers make more informed underwriting decisions; price risk more precisely and better manage potential loss severity.&rdquo;</p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/7-in-10-insurance-flood-claims-linked-to-flash-flooding-27078.htm</link>
<pubDate>Wed, 19 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Rising Inflation  Bond Yields And Middle East Tensions</title>
		<description><![CDATA[<p><strong>Susannah Streeter, Chief Investment Strategist, Wealth Club: </strong>&ldquo;A febrile environment is developing on equity markets as an increasingly entrenched Middle East crisis stokes fears of inflation reigniting, sending downbeat sentiment rippling across global markets. We&rsquo;ve seen sharp sell-offs in Asia, with the Nikkei down 3% and South Korea&rsquo;s Kospi falling 5.8%, as tech stocks are hit hard by concerns about interest rate hikes. The tech-lite nature of the FTSE is keeping it more insulated from turbulence, with the index flat at the open, but the global nature of the index means it isn&rsquo;t completely immune when optimism evaporates, especially with inflationary concerns moving front and centre in the UK.</p>

<p>The jagged line of price increases has taken another painful twist upwards, with households facing a fresh squeeze as higher energy bills push inflation further away from the Bank of England&rsquo;s target.</p>

<p>Consumer Prices Index inflation climbed, unhelpfully, to 2.9% in July from 2.6% in June, as the 13% increase in Ofgem&rsquo;s energy price cap fed through into household bills. The average annual dual-fuel bill has risen by &pound;221 to &pound;1,862, with gas prices particularly responsible for the upward pressure.</p>

<p>For households, this is a particularly unwelcome page turn in the inflation story. And the financial pain may be sharper because private-sector regular pay growth has slowed to 2.8%, so wages are now rising more slowly than prices overall. Workers are therefore having to stretch their pay packets further simply to stand still, with less left over after covering essential bills.</p>

<p>There are, however, some welcome signs of easing elsewhere in the inflation basket. Petrol prices fell by 3.1 pence a litre in July, while diesel dropped by 8.8 pence, helping to pull annual motor fuel inflation down to 15.5% from 21.3%.</p>

<p>There was also some relief for holidaymakers, with European air fares helping to push transport inflation lower. It appears the flash of uncertainty caused by the war with Iran and concerns about jet fuel shortages prompted more holidaymakers to book later, intensifying competition between airlines and pulling down the price of some tickets.</p>

<p>Price rises for food and non-alcoholic beverages also appear to have been going in the right direction, with inflation easing to 1.3% from 1.7%, its lowest rate since September 2021. But it could be the lull before the storm, given worries are intensifying that prolonged heat and drought across the UK and Europe are threatening crop yields, with concerns over supplies of cereals, fruit and vegetables. If shortages build, higher agricultural costs could eventually feed through to supermarket shelves, putting renewed pressure on food prices later this year and into 2027.</p>

<p>So the headline rate may be concerning, and there are niggles of worry about what could be ahead, but if you strip out volatile food and fuel prices, then the core rate of inflation has held steady at 2.6%. This will be more reassuring for the Bank of England, especially with services inflation easing from 3.6% to 3.4%. Policymakers will also have an eye on the cooling labour market, with vacancies falling and public-sector pay increases easing. Right now, two interest rate hikes are still priced in by financial markets, but forecasts have changed wildly, and much will depend on the data in the months to come.</p>

<p>But the Iran crisis remains a huge wildcard, and right now the heat is still being felt in energy markets, with Brent crude hovering close to $92 a barrel with hostilities continuing and negotiations for a long-term solution remaining elusive. If tensions keep oil and gas prices elevated for months rather than weeks, higher energy and transport costs could start to feed through into the wider economy, potentially triggering renewed wage demands.</p>

<p>At the same time, a pressure cooker is building in bond markets, with yields becoming increasingly steamy amid concerns about persistent inflation, heavy government borrowing and the sheer scale of debt being issued. Global long-term bond yields have climbed to multi-year highs, adding to the sense that investors are demanding more compensation for taking on the risk of holding government debt.</p>

<p>That is creating turbulence for equities because higher yields make bonds more attractive relative to shares, while also raising borrowing costs and reducing the present value of future corporate profits. The effect is particularly uncomfortable for highly valued technology stocks, where valuations are highly reliant on expectations for future earnings. That&rsquo;s why turbulence continues to hit the tech sector, with South Korea&rsquo;s chip stars particularly affected as optimism seeps away, with SK Hynix and Samsung again seeing sharp falls.&rdquo;</p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/rising-inflation--bond-yields-and-middle-east-tensions-27076.htm</link>
<pubDate>Wed, 19 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Ai Overtakes Traditional Concerns As The Biggest Pi Risk</title>
		<description><![CDATA[<div>A survey by insurance experts Everywhen asked businesses and professionals to identify the biggest PI risk facing organisations today, with 41% selecting AI mistakes, ahead of cyber risks at 35%. Compliance failures were identified by 23% of respondents, while just 1% selected vendor failures.</div>

<div> </div>

<div>The findings point towards a significant shift in the risks surrounding professional services. While PI insurance has traditionally been associated with human errors such as incorrect advice, missed deadlines, negligence and contractual disputes, businesses must increasingly consider what happens when technology plays a role in the decisions, advice, and services they provide.</div>

<div> </div>

<div>The rise of generative AI has allowed businesses to automate and accelerate everything from research and analysis to customer communications, document preparation, and professional advice. But greater use also raises an increasingly important question: who is responsible when AI gets it wrong?</div>

<div> </div>

<div>An AI-generated document containing inaccurate information, an automated recommendation based on flawed data or unchecked AI output incorporated into professional advice can potentially create financial and reputational consequences for both businesses and their clients.</div>

<div> </div>

<div>The survey suggests this is no longer regarded as a future or theoretical concern. AI mistakes are already perceived as a greater PI threat than compliance failures and other established areas of professional risk.</div>

<div> </div>

<div><strong>Neil D&rsquo;Mello, Client Director at Everywhen, said: </strong>&ldquo;Professional Indemnity, and traditional risks have long been centred around human judgement, the advice somebody gives, the deadline somebody misses or the error somebody makes. Technology is beginning to complicate that picture. &ldquo;AI can be an incredibly useful tool for businesses, but using technology doesn't necessarily remove responsibility for the outcome. If AI-generated information forms part of the advice, work or service provided to a client, businesses need to understand how that information has been produced and ensure appropriate checks remain in place.</div>

<div> </div>

<div>&ldquo;What is particularly interesting about these results is that AI and cyber together account for 76% of responses. It suggests businesses increasingly see their greatest professional risks as being connected to technology. The challenge now is making sure risk management, and insurance arrangements evolve at the same pace as the technology businesses are adopting.&rdquo;</div>

<div> </div>

<div>&ldquo;AI has the potential to enhance client service and streamline decision-making, but brokers should understand how AI-generated information is being used within their advice processes. Appropriate oversight can help ensure clients receive high-quality advice and reduce the potential for Professional Indemnity exposures. Ultimately, clients will continue to look to their broker for trusted professional advice.&rdquo;</div>

<div> </div>

<div><strong>Digital risk moves to the heart of professional liability</strong></div>

<div>Cyber risks being selected by more than a third (35%) of respondents reinforces the extent to which professional and digital exposures are becoming intertwined. Businesses increasingly hold sensitive client information, communicate and deliver services digitally and depend on cloud platforms and interconnected systems. A cyber incident can therefore extend beyond disruption or data loss and potentially affect a company's ability to fulfil its professional obligations to clients.</div>

<div> </div>

<div>At the same time, regulatory expectations are developing as businesses navigate new technologies, data requirements and increasingly complex compliance environments. Everywhen says the findings underline the importance of businesses looking beyond the traditional definition of professional error when considering their exposure. Rather than asking only what happens if an employee makes a mistake, organisations may increasingly need to consider what happens if the technology they rely upon makes one too, and where responsibility ultimately lies.</div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/ai-overtakes-traditional-concerns-as-the-biggest-pi-risk-27079.htm</link>
<pubDate>Wed, 19 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Brace For Continued Inflationary Fallout</title>
		<description><![CDATA[<p><strong>Kevin Brown, savings expert at financial mutual Scottish Friendly, says: </strong>&ldquo;Inflation is on the rise again. July&rsquo;s 13 per cent increase in the energy price cap means more of the impact of the conflict in the Middle East is now landing directly on UK household bills, with another increase expected in October. Yet energy may only be exerting part of the pinch this autumn. Expensive fuel and fertiliser are adding pressure to food production and supply chains, while an exceptionally hot summer raises another threat to harvests. As a result, families may continue to feel the inflationary fallout from this at the till as well as through their utility bills. The Bank of England is expected to hold rates in September, although it will have August&rsquo;s inflation reading to consider before then. But with the majority of forecasts pointing to inflation remaining above its 2 per cent target into next year, policymakers face the perpetual balancing act of getting ahead of rising prices without choking off economic momentum. For households, that makes getting the most from every penny ever more important. Competitive savings rates can help cash work harder, while those with a greater appetite for risk and a longer-term horizon may want to consider investing for the potential to achieve returns that outpace inflation over time.&rdquo;</p>

<p><strong>Jenny Holt, Customer Savings & Investment Director at Standard Life said:</strong> &ldquo;Inflation heading back up is an unwelcome reminder that the cost-of-living squeeze hasn&rsquo;t gone away. The 13% increase in Ofgem&rsquo;s energy price cap from July is feeding higher bills into household budgets, with the increase equivalent to around &pound;18 a month for a typical household. With inflation at 2.9%, everyday costs are still rising faster than the Bank of England&rsquo;s 2% target. Andy Burnham&rsquo;s planned temporary removal of VAT from household electricity from October should provide some welcome relief, but it is likely to offset only part of the recent increase in energy costs. Prolonged hot and dry weather could also put further pressure on some food prices later in the year, meaning households may continue to feel the squeeze across several areas of everyday spending. When more of the monthly budget is absorbed by essentials such as energy and food, it can also become harder for people to put money aside, whether that's building emergency savings to cover unexpected costs or contributing towards longer-term goals like saving for retirement. Renewed inflationary pressure could also make the Bank of England more cautious on interest rates. While cooling wage growth may ease some of the pressure, a more persistent rise in prices could keep borrowing costs higher for longer. For savers, it is also an important reminder that the headline interest rate on savings only tells part of the story - what ultimately matters is the return they are earning after inflation. For people approaching or already in retirement, even relatively modest inflation can make a meaningful difference over time. Rising prices steadily reduce what a fixed level of income can buy, making it harder to balance today&rsquo;s household costs with longer-term plans. Regularly reviewing retirement plans and considering how changing costs could affect the income needed in later life can help people understand whether their savings remain on track.&rdquo;</p>

<p> </p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/brace-for-continued-inflationary-fallout-27080.htm</link>
<pubDate>Wed, 19 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>1 In 7 Drivers Uninsured Due To Out Of Date Addresses</title>
		<description><![CDATA[<div>New research from Aviva reveals one in seven (15%) drivers may have incorrect addresses on their motor insurance. This is particularly high amongst young motorists aged 18-24-years-old, with more than one in three (37%) not knowing they need to tell their insurer about a change of address. </div>

<div> </div>

<div>As a result, drivers may not be able to make a claim should the worst happen, potentially leaving them to cover repair costs, replacement cars, damage to other vehicles or property, or legal expenses.</div>

<div> </div>

<div>Other misconceptions around car insurance include needing to declare a change of job (61%), changes in estimated annual mileage (39%), changes in where the car is kept overnight (26%) and declaring who the correct main driver is (16%). The research comes as more than seven in ten (71%) drivers are unclear about the changes they need to declare to their insurer.</div>

<div> </div>

<div><img alt="" src="https://www.actuarialpost.co.uk/images/pic_AvivaChanges1908261.jpg" style="height:179px; width:600px" /></div>

<div><em>Please note this is not an exhaustive/exclusive list</em></div>

<div> </div>

<div><strong>James Driscoll, Motor Claims Manager at Aviva, said: </strong>&quot;Car insurance is based on the information drivers provide, so it's important that insurers are made aware of any changes as soon as they happen. This includes things like a change of address, which 15% of people surveyed were unaware needed to be declared to their insurer. While some changes may seem minor, failing to keep your details up to date could affect your cover and, in some cases, lead to difficulties when making a claim. If in doubt, it&rsquo;s worth contacting your insurer directly to make sure they have the correct information on file. &quot;</div>

<div> </div>

<div><strong>Aviva&rsquo;s dos and don&rsquo;ts on what changes should be shared with your insurer include:</strong></div>

<div> </div>

<div><strong>1. DO let your insurer know if your job changes.</strong></div>

<div>Aviva's research found that fewer than two in five drivers (39%) correctly identified that this type of change should be reported to their insurer, making it one of the least well-understood policy updates among those surveyed.</div>

<div>In some cases, drivers may need a specific type of insurance. For example, drivers who start using their car for deliveries, courier work, transporting passengers, or regular business travel will need additional cover beyond standard social, domestic and commuting use.</div>

<div> </div>

<div><strong>2. DO update your insurer if your annual mileage changes.</strong></div>

<div>Annual mileage is another factor insurers will consider when assessing risk, as the more time the car spends on the road, the greater the likelihood of being involved in an incident. Despite this, just over three in five drivers (61%) correctly identified that changes in annual mileage must be reported to their insurer.</div>

<div> </div>

<div><strong>3. DO tell your insurer if you change your car. </strong></div>

<div>Changing your car is one of the most important updates to share with your insurer, as details such as the car&rsquo;s make, model, value, performance and repair costs can all affect the level of risk associated with it. Despite this, almost one in five drivers (18%) don&rsquo;t think they need to tell their insurer when changing cars. A new car can have very different characteristics from the one previously insured, and failing to update your insurer could lead to unnecessary complications if you need to make a claim.</div>

<div> </div>

<div><strong>4. DO tell your insurer if you change where you usually keep your car overnight.</strong></div>

<div>Where the car is normally kept overnight is another detail drivers may overlook, as more than a quarter of drivers (26%) think they don&rsquo;t need to tell their insurer if this information changes. Yet the location where the car is parked &ndash; whether on a driveway, in a garage, on the street or in a secure car park &ndash; can affect the likelihood of theft, vandalism or accidental damage. If you move home or start keeping your car in a different location, it's important to update your insurer.</div>

<div> </div>

<div><strong>5. Don't let your MOT expire. </strong></div>

<div>Almost a quarter of drivers (24%) are unaware that driving without a valid MOT could invalidate their insurance or affect their ability to make a claim. As well as being a legal requirement for most vehicles over three years old, an MOT provides evidence that a vehicle meets minimum roadworthiness standards. If a vehicle is involved in an incident without a valid MOT, insurers may investigate the circumstances and whether the vehicle's condition contributed to the accident. Failing to keep an MOT up to date could result in a claim being reduced or declined, leaving drivers facing unexpected costs.</div>

<div> </div>

<div><strong>6. DO update your insurer about car modifications, even if they don&rsquo;t affect the performance of the car. </strong></div>

<div>Aviva's research found that just over two in five drivers (41%) believe modifications only matter if they affect the performance of the car. Although this can impact your insurance, it might not necessarily increase your premium. Before making any changes to your car, it's smart to understand how they might affect your insurance and discuss them with your insurance provider to ensure you have the right cover.</div>

<div> </div>

<div><strong>7. Do tell your insurer if the main driver of the car changes. </strong></div>

<div>Insurers need to know who uses the car most often, as this information forms an important part of their risk assessment. However, 16% of drivers do not believe they need to tell their insurer if the main driver of the car changes. This could happen when a child starts regularly using the family car, a partner becomes its primary user, or ownership of driving responsibilities shifts over time. Providing incorrect information about who drives the car most frequently is sometimes referred to as &quot;fronting&quot; when a lower-risk driver is named as the main driver despite another person using the car most often. Whether intentional or unintentional, this is a form of insurance fraud through misrepresentation of the risk. It is important to declare all details accurately and honestly as providing misleading information could invalidate your policy.</div>

<div> </div>

<div><strong>8. DO tell your insurer about incidents, even if you don't make a claim.</strong></div>

<div>Even minor incidents can be relevant to your insurer, regardless of whether a claim is made. However, over half of drivers (58%) correctly recognised that they should inform their insurer about a minor collision or an event which results in little or no damage, even if they do not make a claim. If you're involved in an incident, it&rsquo;s essential that you notify your insurer, even if you intend to cover any costs yourself &ndash; which is a condition on most insurance policies.</div>

<div> </div>

<div><strong>9. DO check your details at renewal.</strong></div>

<div>Drivers are responsible for ensuring their details, and those of anyone else driving the car, are accurate and that nothing has changed at renewal. Despite this, over half of drivers (57%) surveyed thought insurers will spot any missing or outdated information at renewal and more than four in five (81%) believed no action is needed if nothing has changed. Failing to do so could mean outdated or incorrect details remain on a policy, potentially affecting cover and causing difficulties if a claim needs to be made.</div>

<div> </div>

<div><strong>10. DON&rsquo;T assume insurance issues can't affect future policies.</strong></div>

<div>Nearly half of drivers (46%) believed that having invalid insurance would only affect their current policy and would not impact their ability to take out a new policy with another insurer in future. However, insurance history is an important factor when arranging cover, and past issues - such as having a policy cancelled by your current provider - may be considered by insurers when assessing future applications.</div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/1-in-7-drivers-uninsured-due-to-out-of-date-addresses-27082.htm</link>
<pubDate>Wed, 19 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Pic Agrees  58m Buyin With Icaew Staff Pension Fund</title>
		<description><![CDATA[<div>The Institute of Chartered Accountants in England and Wales (ICAEW) is a professional membership organisation that promotes, develops and supports chartered accountants and students around the world.</div>

<div> </div>

<div><strong>Edward Levy, Director of The Law Debenture Trust Corporation plc and Chair of the Fund, said:</strong> &ldquo;The Fund has been on a long-term derisking journey and we are delighted to have concluded this latest stage with PIC. The team were flexible and constructive in helping us achieve our aims.&rdquo; </div>

<div> </div>

<div><strong>Joshua Lenz, Origination Actuary at Pension Insurance Corporation, said:</strong> &ldquo;We are pleased to have completed this transaction with the Trustee, helping increase overall security for the members. Our expertise across the whole of the market means we can support schemes of all sizes in achieving their objectives.&rdquo;</div>

<div> </div>

<div>Hymans Robertson acted as lead transaction advisor. Legal advice for PIC was provided by Addleshaw Goddard with the Trustee supported by Eversheds Sutherland. </div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/pic-agrees--58m-buyin-with-icaew-staff-pension-fund-27081.htm</link>
<pubDate>Wed, 19 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Ai Drives 36  Surge In Disclosed Vulnerabilities</title>
		<description><![CDATA[<p>Beazley Security today releases its <a href="https://beazley.security/insights/quarterly-threat-report-second-quarter-2026">Quarterly Threat Report for Q2 2026</a>, finding that the widespread adoption of agentic AI in vulnerability research drove a 36% quarter-over-quarter increase in newly disclosed vulnerabilities while the methods attackers used to breach organizations remained almost entirely unchanged.</p>

<p>Vulnerabilities confirmed as actively exploited and added to the Cybersecurity and Infrastructure Security Agency's (CISA) Known Exploited Vulnerabilities catalog rose only 10% over the same period, a gap that further amplifies an already difficult prioritization challenge facing security teams. Read the full report at: Quarterly Threat Report: Second Quarter, 2026</p>

<div><strong>AI reshapes vulnerability research faster than exploitation</strong></div>

<div>Disclosure volume has historically moved within a 10% band from quarter to quarter. That pattern broke in 2026, rising 18.5% in Q1 and another 36% in Q2.  Beazley Security Labs (BSL) attributes the surge to the rapid operationalization of agentic AI across research programs. The strain of the higher volumes is visible industry-wide: NIST no longer enriches every new CVE; HackerOne's Internet Bug Bounty paused submissions citing AI-assisted research; Pwn2Own issued applicant rejections for the first time; and Cisco restructured its disclosure model outright.</div>

<div> </div>

<div><strong>Attackers experiment with AI, but still succeed with credentials</strong></div>

<div>Threat group TeamPCP compromised the TanStack developer package suite in an incident that produced more than 500 million downloads of infected packages within hours, then published its worm's vibe coded source code on a criminal forum alongside a cash-prize competition for the most damaging supply chain compromise. Sysdig separately documented JADEPUFFER, assessed as the first ransomware campaign driven end to end by a large language model.</div>

<p>While dramatic, these headlines did not change how most intrusions actually started. Compromised credentials used against internet-facing VPN and remote desktop services accounted for 67% of ransomware intrusions investigated by Beazley Security. This is down from 74% in Q1 but is still dominant by a wide margin.</p>

<p>Law enforcement efforts to disrupt infostealer families have had success but are proving to be short-lived. Within four days of an Operation ENDGAME takedown, StealC malware authors shipped a new version of the malware and offered the previous source code for $60,000. Public ransomware leak-site postings fell slightly to 2,268 but remained nearly 60% above Q2 2025.</p>

<div><strong>Identity attacks evolve past multifactor authentication</strong></div>

<div>Business email compromise (BEC) remained among the most common incident types, with attackers increasingly abusing Microsoft's device code authentication flow to capture session tokens. Because the victim completes a legitimate sign-in and satisfies any organizational MFA requirement, the attacker never needs to intercept a code.</div>

<p><strong>Alton Kizziah, CEO of Beazley Security, said: </strong>&ldquo;The headline this quarter is that AI made the security industry's job noisier without making the attacker's job fundamentally different. But AI assisted attacks are gaining in both frequency and effectiveness, and we seem to be watching the attackers learn in real time. As AI adoption in the enterprise increases, and as attackers continue to evolve tactics, clients need to remain vigilant and attend to cybersecurity basics. We also recommend organizations consider AI assessments to monitor what AI capabilities are in use across the organization, how these tools are being used, and what is needed to improve management and control frameworks.&rdquo;</p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/ai-drives-36--surge-in-disclosed-vulnerabilities-27073.htm</link>
<pubDate>Tue, 18 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Smaller Pensions Must Prepare For Wide Usage Of Dashboards</title>
		<description><![CDATA[<div>Smaller pension schemes, some of which are still to connect to the pensions dashboards ecosystem, should now be looking beyond connection in their dashboards preparations, Lumera, a leading insurtech company, has warned.</div>

<div> </div>

<div>This is because these schemes can face disproportionate pressures compared with their larger counterparts &ndash; often lacking dedicated project teams, specialist data functions and administration capacity despite needing to meet the same requirements once connected.</div>

<div> </div>

<div>For example, some in-house administered schemes rely on only one or two individuals responsible for all day-to-day administration.</div>

<div> </div>

<div>The increased challenge for smaller schemes is reflected in The Pensions Regulator's latest Pensions Dashboards Readiness Survey, which reported that 65% of schemes surveyed, which were schemes with between 600 and 999 relevant members, had completed all five key preparation activities around 11 months before their &lsquo;connect by&rsquo; date, compared with 79% of schemes with more than 20,000 members.</div>

<div> </div>

<div>The key preparation activities that schemes were asked about were regularly tracking progress at board meetings, discussing preparations with administrators, choosing a route to connection, having digital personal data, and having confidence in the accuracy of this data.</div>

<div> </div>

<div>Lack of confidence in data can make it much more difficult for schemes to support dashboards after connection. For smaller defined benefit schemes in particular, deferred pension values are not always recalculated annually, meaning new calculation processes or automated technology may be needed to produce dashboard-ready values if schemes do not want to rely on carrying out calculations &lsquo;on demand&rsquo;.</div>

<div> </div>

<div>Once dashboards are used more widely, then the associated support activities will need to scale up. These include the need to investigate possible matches, provide pension values within statutory timescales, maintain member records, respond to increased enquiries and monitor ongoing performance and compliance.</div>

<div> </div>

<div>For smaller administration teams, even modest volumes of dashboard-initiated requests could disrupt day-to-day operations.</div>

<div> </div>

<div>Poorly designed matching criteria can add further pressure, either preventing genuine members from finding their pensions or generating unnecessary manual investigations through false matches. Likewise, relying on manual &lsquo;on demand&rsquo; pension-value calculations risks creating operational bottlenecks and delaying responses.</div>

<div> </div>

<div>With live testing of the MoneyHelper Pensions Dashboard starting to ramp up, and its public launch date currently expected in the next financial year, smaller schemes should be joining their larger counterparts in completing end-to-end testing of their dashboard processes, validating member data and matching criteria, and ensuring pension values can be produced accurately within statutory timescales. Schemes that postpone this work risk creating avoidable operational backlogs and a poorer member experience.</div>

<div> </div>

<div><strong>Maurice Titley, Commercial Director, Data & Dashboards at Lumera, commented:</strong> &ldquo;Small schemes face a double challenge - getting connected with limited resources and then managing the operational demands when pensions dashboards are used at scale by the public, which is expected to start with the launch of the MoneyHelper Pensions Dashboard (MHPD) in the next financial year.&rdquo;</div>

<div> </div>

<div>&quot;While the priority, understandably, has been to connect to the pensions dashboards ecosystem ahead of the 31 October legal deadline, the focus now needs to shift to addressing data weaknesses ahead of public availability. The schemes that adapt most successfully to the post-dashboards world will not necessarily be those with the &lsquo;best and biggest&rsquo; resources, but those that have taken the time to understand their data, test their processes and put proportionate controls in place before their members begin using the service.&rdquo;</div>

<div> </div>

<div>&quot;Although dashboards introduce new obligations, tackling data issues now will help schemes avoid operational bottlenecks when the MHPD goes live, and create stronger foundations for longer-term priorities, including consolidation, buyout and other strategic options.&quot;</div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/smaller-pensions-must-prepare-for-wide-usage-of-dashboards-27070.htm</link>
<pubDate>Tue, 18 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Middle East Fracture Sends Crude And Borrowing Costs Higher</title>
		<description><![CDATA[<div>UK jobs market is in stasis, as employers stay wary amid economic uncertainty and higher payroll costs. Unemployment rate stays at 4.9%, but early estimate for payrolled employees in July shows an annual decline of 94,000. The number of vacancies has also slipped to 707,000, the lowest level outside the pandemic period since late 2014. Regular wage growth edges up to 3.5%, remaining above inflation and the Bank of England&rsquo;s 2% target, keeping policymakers wary about underlying price pressures.</div>

<p><strong>Susannah Streeter, Chief Investment Strategist, Wealth Club: </strong>&ldquo;With economic uncertainty so high, and payroll taxes increasingly onerous, it&rsquo;s not surprising many UK employers are staying cautious, and unwilling to take the risk of hiring new staff. The trend is showing up once again in the latest labour market snapshot from the ONS.</p>

<p>Payrolled employees fell by 78,000 over the year to June, while the early estimate for July shows a further annual decline of 94,000. The number of vacancies has also slipped to 707,000, the lowest level outside the pandemic period since late 2014, with the ONS reporting feedback that some smaller firms are holding back on recruitment because of higher labour costs and other operating expenses.</p>

<p>Regular pay growth edged up to 3.5% in the year to June, from 3.4% previously, which may spark fresh niggles of concern among Bank of England policymakers. However this is being largely driven by higher pay deals in the public sector. Even so private sector companies may come under pressure to keep up with demands for better deals from their staff. Policymakers will watch closely for signs that this could lead to higher payroll costs being passed on as higher prices for goods and services. Right now markets are currently pricing in two interest rate hikes over the next year, given the potential rise in inflationary pressures.</p>

<p>This snapshot shows that businesses are hunkering down and trying to deal with a storm of higher costs, rather than taking a punt on expansion, which doesn&rsquo;t bode well for UK growth prospects. It&rsquo;s not just taxes and payroll costs which are weighing heavily, higher energy bills are also causing havoc with budgets, with fears of secondary price increases rising amid fresh fractures in geopolitics.</p>

<p>Brent crude has climbed above $91 a barrel as tensions have frayed again in the Middle East, raising fears of yet more supply disruption. Trump&rsquo;s inflammatory language towards Oman, threatening to bomb the US ally, has sparked this latest rally. There&rsquo;s disappointment that the temporary ceasefire with Iran has expired without a deal, and the US president for now claims he&rsquo;s not interested in reaching one. He&rsquo;s clearly irked that Oman and Iran are in negotiations without the US to reopen the crucial Strait of Hormuz, and unable to control the situation, is reverting to threats of fresh military action instead.</p>

<p>Higher energy prices risk feeding through into transport, manufacturing and household bills, making the battle to bring down inflation harder to win. That is forcing markets to reassess how long interest rates will stay elevated.</p>

<p>Bond markets are flashing amber across the globe, with investors demanding ever-higher returns to lend to governments as fears grow that inflation may prove much harder to shift. The yield on the US 30-year Treasury has pushed above 5.32%, its highest level in almost two decades, while UK gilt yields have also surged back towards levels not seen since the aftermath of the financial crisis. France is also feeling the heat, with 30-year borrowing costs having climbed to their highest level since 2008. Investors are increasingly demanding a bigger premium to hold long-dated government debt as higher oil prices threaten to keep inflation elevated and concerns mount about the sheer scale of government borrowing.</p>

<p>The yen is caught in the crossfire of these concerns. Japan has also seen its own bond yields leap to multi-decade highs as investors anticipate further rate rises from the Bank of Japan. Normally that would be enough to give the yen a lift. Instead, the currency remains stubbornly weak because Japanese interest rates are still well below those available in the US and other countries, so the risk is that the yen stays caught in this doom loop, with investors chasing higher returns elsewhere. We may have seen a remarkable bout of currency intervention, with Japan selling dollars and buying the yen, and the US Treasury also stepping in to support the currency. But the effect has proved short-lived, with powerful currents in global bond markets continuing to overwhelm those efforts.&rdquo;</p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/middle-east-fracture-sends-crude-and-borrowing-costs-higher-27072.htm</link>
<pubDate>Tue, 18 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>The Power Of Compound Growth </title>
		<description><![CDATA[<p><strong>By JP Crowley,Principal, Marsh</strong></p>

<p>Add it up and it should come out roughly equal. It doesn&rsquo;t. The UK Pension Commission&rsquo;s own modelling shows that someone who starts saving at 40 needs to contribute around 13% of their pay to hit a target replacement rate. Start at 22? You need just 7%. The same retirement outcome. Nearly double the contribution rate required because of the delay getting started. This is a key reason why financial education and pension communication can be so challenging. The numbers that matter most &ndash; what happens in the third or fourth decade of saving &ndash; feel abstract and unreal to a younger saver, while the near-term cost of contributions feels concrete. Our brains weight the linear present over the exponential future.</p>

<p>I modelled a saver from age 25 to 65 on a starting &pound;27,000 salary, contributing 9% annually with reasonable investment return and salary growth levels assumed throughout their working career.</p>

<p>Final pot: &pound;510,000. Total contributions: &pound;194,000. The remaining &pound;316,000 &mdash; 62% of the entire pot &mdash; came from investment returns compounding quietly over four decades.</p>

<p>Using the same assumptions, the chart below illustrates this nicely by looking at how the contributions made within each five year age cohort compound over a 40 year working career. Time is a valuable commodity for anyone saving for their retirement and this is highlighted when we consider the contributions in the earliest age cohort (25-29) grow more than 7x by age 65 whereas contributions made in the 55-59 age cohort only have the opportunity to grow by 1.4x by age 65. The total pot accumulates to &pound;510,000 but almost half of this was generated from contributions made in the first 15 years (when the base salary was lower!).</p>

<p><img alt="" src="https://www.actuarialpost.co.uk/images/pic_MercerCompound1808261.jpg" style="height:583px; width:600px" /></p>

<p>The central tenet that beginning your savings journey early is one of the key ingredients to a successful retirement outcome holds true. This decision can ultimately swamp the impact from a host of other factors that are designed to incrementally improve outcomes for pension scheme members. The UK&rsquo;s Pension Schemes Act 2026 is largely about driving those incremental improvements (e.g. greater scale facilitating lower charges and enabling access to potentially higher-return investment opportunities). However, rather than seeing these targeted improvements as peripheral to the key decision around when and how much a person saves into their pension, they should be viewed as another crucial part of an individual&rsquo;s compounding journey.</p>

<p>Take our modelled example above, a 1% improvement in annual returns (due to lower fees and/or better investment returns) results in the final pot at age 65 being &pound;130,000 higher. And that extra &pound;130,000 has the potential to further compound in retirement to meaningfully improve the annual income a person can sustainably withdraw throughout their retirement years.</p>

<p><strong>Ralph Waldo Emerson said:</strong> &ldquo;The years teach us much, which the days never knew&rdquo;.  In a retirement savings context, this quote could reasonably be edited to replace &lsquo;years&rsquo; with &lsquo;decades&rsquo; and &lsquo;days&rsquo; with &lsquo;years&rsquo;. Small differences in net returns, charges, or time invested can look modest year to year but persistence and patience over decades allows the exponential power of compounding to shine.   </p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/the-power-of-compound-growth--27074.htm</link>
<pubDate>Tue, 18 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>New Fiscal Order  Can The Past Predict Burnhams First Budget</title>
		<description><![CDATA[<p>The Office for Budget Responsibility's forecast, published alongside the Budget, will ultimately dictate how much room any of them actually have to make their policy dreams a reality.</p>

<p>With income tax, VAT and employee National Insurance rate rises all but ruled out by the Labour government&rsquo;s manifesto pledge, wealth, property and capital taxes look the most likely route to raising revenue. This is also where the current government&rsquo;s voting records are most consistent.</p>

<p>But as with investing where past performance is not a guarantee of future returns, past voting records are no guarantee of future tax policy. Backbench votes cost little and don't always survive when coming into contact with the government.</p>

<p><strong>Andy Burnham</strong> has almost always voted against welfare cuts and for higher taxes on top earners and capital gains. This record points away from benefit cuts as a way to close the gap.</p>

<p><strong>John Healey</strong> has voted consistently for a mansion tax and further capital gains tax rises, and against VAT increases, suggesting a wealth-focused Budget.</p>

<p><strong>Emma Reynolds</strong>, who runs the spending review as Chief Secretary to the Treasury, has almost always voted for capital gains tax rises and stamp duty increases.</p>

<p><strong>Pat McFadden</strong>, who owns the welfare budget, has almost always voted against benefit spending cuts, suggesting any DWP savings are more likely to come from benefits reform rather than headline cuts.</p>

<p><strong>Torsten Bell</strong>, who was brought into government as Pensions Minister, naturally has the most pension-specific record: consistent support for capital gains tax and stamp duty rises, and as Minister, defended the already-legislated &pound;2,000 salary-sacrifice pension cap (from Budget 2025) against a Lords attempt to raise it.</p>

<p><strong>Becky O&rsquo;Connor, Head of Pensions at PensionBee, said:</strong> &ldquo;The past is history, tomorrow is a mystery&rsquo; is an inspirational quote that can certainly be applied to second guessing Budget decisions. Although it&rsquo;s hard to ignore the voting records of key ministers that point towards tax rises and away from welfare cuts, history shows that voting records and government policy don't always match up. </p>

<p>&ldquo;The same caution applies here: a decade of backbench votes tells us about instinct and ideology, rather than intent. Just as &lsquo;feelings aren&rsquo;t facts&rsquo;, fevered speculation is not policy announcement. </p>

<p>&ldquo;When it comes to wealth or income tax increases, the way measures affect pension savers, in particular those already retired, is a minefield when it comes to actually achieving any wealth redistribution goals. This is because taxation geared towards pension wealth - as with more income tax for higher earners - does not always have the intended effect of making the wealthiest pay more, but can instead end up penalising those who have worked hard, saved diligently and made net economic contributions but are not necessarily wealthy. </p>

<p>&ldquo;Savers should avoid making key decisions that may have long-term consequences for their own financial future based on rumours, historical voting records or assumptions. </p>

<p>&ldquo;The sensible approach is to wait for the actual details set out on 28 October, and speak to a financial adviser if needed, before acting. Damage has recently been done through pension savers moving on speculation, particularly in relation to pension taxation. It&rsquo;s best to wait until the facts are known and the impact </p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/new-fiscal-order--can-the-past-predict-burnhams-first-budget-27075.htm</link>
<pubDate>Tue, 18 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Wage Data Likely To Be Key Factor In Triple Lock Uplift</title>
		<description><![CDATA[<p>The ONS has published the latest UK Labour Market data: <a href="https://www.ons.gov.uk/employmentandlabourmarket/peopleinwork/employmentandemployeetypes/bulletins/uklabourmarket/latest">Labour market overview, UK - Office for National Statistics</a></p>

<p><strong>Helen Morrissey, head of retirement analysis, Hargreaves Lansdown: </strong>&ldquo;Average wage growth plus bonuses stood at 4.1% between April-June. This could prove to be an interesting figure for state pensioners as next month&rsquo;s data is a key part of the formula for the state pension triple lock.</p>

<p>The triple lock aims to increase the state pension by whichever is highest of average wages (May-July), September&rsquo;s CPI inflation or 2.5%. With inflation standing at 2.6%, this suggests, barring a shock inflation spike over the next couple of months or collapse in average wage growth, that wages will be the element used.</p>

<p>Should next month&rsquo;s figure remain the same as today&rsquo;s, this would put someone on a full new state pension on around &pound;251.20 per week, up from &pound;241.30 per week. Someone on a full basic state pension would see their weekly amount rise from &pound;184.90 per week to around &pound;192.50 from next April.</p>

<p>While an inflation-busting increase will be good news for pensioners, the fact remains that the state pension on its own does little more than cover the essentials. If you want more from your retirement, then you need to make the most of your workplace and personal pensions.</p>

<p>Auto-enrolment has done a great job in recent years in getting more people saving into a pension. However, for many, saving at auto-enrolment minimums will not enable them to maintain their lifestyle in retirement. To prevent a nasty shock, it pays to consider what you want your retirement to look like and then you can calculate how much it might cost. A nice retirement means different things for different people &ndash; some may want to travel the world; others may want to stick closer to home but spend more time with family and friends. </p>

<p>Make use of online tools from your pension provider, such as online calculators. These can tell you how much you are on track to receive. If you aren&rsquo;t quite where you want to be, you can also model the impact of increasing your contributions over time. Taking small steps, such as increasing your contributions every time you receive a pay rise, can make a huge difference. You can also make the most of employer contributions. Many businesses contribute at auto-enrolment minimum levels, but others contribute more if you do &ndash; the so-called &lsquo;employer match&rsquo;. If you&rsquo;ve got the extra cash, then the extra boost from your employer can make all the difference to your lifestyle in retirement.&rdquo;</p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/wage-data-likely-to-be-key-factor-in-triple-lock-uplift-27071.htm</link>
<pubDate>Tue, 18 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Wildfires Pressurize Insurers As Climate Risks Intensify</title>
		<description><![CDATA[<p>GlobalData&rsquo;s Global Insurance Database shows that natural fire and hazard premiums totaled $2.4 billion in France in 2024 with claims at $2.2 billion; a difference of just $218 million. This highlights how thin the margins can be in this high-risk line and illustrates how difficult 2026 will be for insurers.</p>

<p>The wildfires are still ongoing in France and could get considerably worse if they get even closer to cities such as Bordeaux, where they have already caused a great deal of disruption.</p>

<p><strong>Ben Carey-Evans, Senior Insurance Analyst at GlobalData, explains:</strong> &ldquo;It is yet more evidence that insurers around the world should be extremely concerned by climate change and the impact of severe weather events. A GlobalData poll on Verdict Media sites in May 2024 found that 25.0% of respondents believed severe weather events to be the greatest risk to the insurance industry, which placed it second behind cyber threat. While this is a couple of years old, severe weather events is only more of an issue now and it highlights how it has been a key concern for insurers over a long period of time.&rdquo;</p>

<p>Reportedly, wildfires in France are not covered by its state-backed compensation scheme (which only covers floods and droughts). Therefore, all the burden will fall on insurers.</p>

<p><strong>Carey-Evans concludes: </strong>&ldquo;The long-term risk here is that insurers pull away from personal and commercial policies in high-risk areas and large areas of land and population become uninsurable.</p>

<p>&ldquo;This is one of the most-pressing issues in insurance, with more serious events becoming increasingly likely every year. Insurers and governments will need to work out how they can continue to insure increasingly large areas, with many communities and businesses at risk.&rdquo;</p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/wildfires-pressurize-insurers-as-climate-risks-intensify-27066.htm</link>
<pubDate>Mon, 17 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Ftse 100 Ticks Higher And Asian Shares Enjoy Strong Start</title>
		<description><![CDATA[<p>&ldquo;That improved sentiment may be tested as the interim ceasefire agreement between Washington and Tehran expires. The longer we go without any sort of resolution, the more likely we are to see Brent crude oil test the $100 per barrel mark seen in recent months.</p>

<p>&ldquo;It could mean any relief on inflation is temporary. As markets seek to divine the likely trajectory of both rates and prices, UK inflation figures and minutes from the latest Federal Reserve meeting &ndash; both set for the middle of this week &ndash; could be instructive.</p>

<p>&ldquo;In London, miners clawed back some of the ground they lost last week, helped by strong precious metals prices, with weakness seen in consumer-facing stocks.</p>

<p>&ldquo;A notable rise for Johnson Matthey followed a share consolidation taking effect as it paid out a bumper special dividend from the sale of its Catalyst Technologies arm.</p>

<p>&ldquo;Budget retail chain The Works continues to face pressure from activist investor Kelso &ndash; which is now questioning the work-from-home approach taken by the company&rsquo;s New Zealand based chair Stephen Bellamy. This is unlikely to be the last word in the t&ecirc;te-&agrave;-t&ecirc;te between management and Kelso ahead of a crunch shareholder meeting next month.&rdquo;</p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/ftse-100-ticks-higher-and-asian-shares-enjoy-strong-start-27069.htm</link>
<pubDate>Mon, 17 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>It s The I Of The Rr</title>
		<description><![CDATA[<p><u><strong>By Alex White FIA C.Act, Global Head of Quantitative Modelling at Gallagher</strong></u></p>

<p>This is probably provable in closed-form by a better mathematician than me, but I can show it with simulations. Suppose we have a portfolio of 10 stocks, each 50% correlated with each other, and each with a geometric 8% return and 30% (ln) volatility. We run it for 10 years, with no rebalancing.</p>

<p>If we never sell a stock, and just take the final value, the IRR and returns are, by definition, identical (at 10.4%) &ndash; so far so good. But what happens if we start selling part way through?<br />
<br />
Suppose the manager sells any individual stock that outperforms an N x return each year. For example, if a stock in year 4 is worth more than 4 times its original value, then it gets sold.</p>

<p><img alt="" src="https://www.actuarialpost.co.uk/images/pic_AlexWhiteSell1708261.jpg" style="height:205px; width:298px" /></p>

<p>This is a sensible thing to do, at least within the assumptions of this simulation, as it limits concentration, and therefore reduces volatility, and so increases both diversification and geometric returns. In this example though, while hard to quantify precisely, we can cap the effect. The maximum benefits of rebalancing would be attained by full annual rebalancing, and we can estimate this by comparing the theoretical volatility of a fully rebalanced portfolio (22%) with the simulated, non-rebalanced portfolio (25%), and using exp(Vol^2/2) we know this effect is less than 0.8%. In all likelihood it&rsquo;s materially less, as the residual portfolio after any sales would also be quite far from equal weighted.  So, we might expect a boost of about half, or 40bps.<br />
<br />
The IRRs, meanwhile, shoot up to 12.4%, meaning the IRRs are about 2 percentage points higher than the underlying returns, or 1.5% even allowing for some rebalancing advantage. And by construction, this isn&rsquo;t from any skill in selection, this is just from the maths of IRRs. By getting paid early, the IRR looks higher, even though there was no way to keep that reinvestment rate.<br />
<br />
Of course, it&rsquo;s hard to know what the underlying volatility of a private asset really is, in any unsmoothed, economic sense. What&rsquo;s easier is checking the sensitivity of this &ldquo;IRR pickup&rdquo; over returns. Fundamentally, the impact of volatility here is really how likely any stock is to breach a sale point. If we raise it to 40%, the returns are 12.3%[1] and the average IRR is 16.3%. At 50% volatility, these jump to 14.6% and 22.3%, a whopping 8% pickup in expected IRR over expected returns.<br />
<br />
This isn&rsquo;t an attack on private assets, which can and often do deliver outsized returns. This isn&rsquo;t an attack on managers either. Many of the assumptions, such as the sale points, are arbitrary, and the results are not intuitive to interpret- the values we&rsquo;re considering are the expected values of IRRs given the expected returns on the underlying assets. However, it highlights a mathematical quirk, which gives another reason to give pause when assessing an investment, and to not give too much weight to any spectacular historic IRRs.</p>

<p><em>[1] The reason a higher vol assumption drives a higher return is we assume the 8% is geometric, so it makes the arithmetic return per stock higher, and gives a larger pickup from diversification</em></p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/it-s-the-i-of-the-rr-27068.htm</link>
<pubDate>Mon, 17 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Call For Fairness And Transparency In General Levy  039 s Reforms</title>
		<description><![CDATA[<div>While supporting the fundamental objective of putting the General Levy on a sustainable footing and ensuring regulatory bodies are properly resourced, the SPP has raised concerns over proposed steep increases for master trusts and personal pension providers. The representative body is calling on the Government to provide clear, evidence-based justification for these &ldquo;disproportionate&rdquo; rises.</div>

<div> </div>

<div><strong>Key highlights of the SPP&rsquo;s consultation response include:</strong></div>

<div> </div>

<div><strong>A lack of evidence for differential rises</strong></div>

<div>The SPP questions the rationale for placing the largest levy increases on master trusts and personal pension providers without clear evidence that they generate a higher regulatory burden.</div>

<div> </div>

<div><strong>Cumulative regulatory pressure</strong></div>

<div>The SPP states that additional levy costs arrive alongside an unprecedented wave of government-led reforms including Pensions Dashboards, Value for Money (VfM) assessments, small pots consolidation, decumulation, and market consolidation, which compounds financial pressures on the sector.</div>

<div> </div>

<div><strong>Call for consolidated transparency</strong></div>

<div>To build industry confidence, the SPP recommends unified, consolidated reporting across all levy-funded bodies (The Pensions Regulator, The Pensions Ombudsman, and the Money and Pensions Service) to clearly demonstrate cost drivers, efficiency, and value for money.</div>

<div> </div>

<div><strong>Future-proofing beyond 2030</strong></div>

<div>The SPP advocates for a future framework built on fairness, stability, and proportionality. It suggests exploring a split-charging structure (e.g., retaining per-member fees for guidance/ombudsman services while aligning regulatory costs with Assets Under Management) as the market continues to consolidate.</div>

<div> </div>

<div><strong>Madalena Cain, Deputy Chair of the SPP&rsquo;s DC Committee, said: </strong>&quot;The SPP fully supports steps to ensure our regulatory bodies are adequately funded in order to protect savers. However,  any changes to the General Levy must be fair, proportionate, and transparent. Given the huge cumulative cost of ongoing government reforms, the government must ensure levies are carefully balanced with industry affordability. Moving forward, our recommendation to introduce consolidated reporting across all levy-funded bodies would greatly help to provide the transparency and accountability pension schemes - and ultimately savers &ndash; rightly deserve.&quot;</div>

<div> </div>

<div><a href="https://the-spp.co.uk/document/spp-response-to-the-dwps-consultation-on-the-occupational-and-personal-pension-schemes-general-levy-regulations-review-2026/">The SPP&rsquo;s consultation response is available in full, here</a>:</div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/call-for-fairness-and-transparency-in-general-levy--039-s-reforms-27064.htm</link>
<pubDate>Mon, 17 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Finance Sector Must Improve Support For Mental Health</title>
		<description><![CDATA[<p>The report is based on a consumer survey, conducted in collaboration with YouGov, of more than 2,000 UK adults. It considers consumer perceptions and lived experiences when dealing with financial services providers, while experiencing, or having previously experienced, a mental health condition. While the overall survey looks at the finance sector as a whole, some of the questions focus in on insurance, given the high level of actuarial practise in this sector.</p>

<p>The <a href="https://actuaries.org.uk/news-and-media-releases/news-articles/2026/aug/17-aug-26-the-anxiety-of-access-bridging-the-gap-between-mental-health-and-financial-services/">anxiety of access: bridging the gap between mental health and financial services</a> identifies three widespread issues:</p>

<p><strong>1. People do not feel safe being transparent:</strong> 79% of customers believe that sharing mental health information with insurers will lead to higher costs and 65% fear declined cover. This creates a lack of trust and leads to non-disclosure of mental health conditions. </p>

<p><strong>2. Support falls short at the most important moments:</strong> While the majority of respondents felt supported when claiming, they identified multiple opportunities to improve the claims experience, suggesting that current processes do not yet fully meet the needs of vulnerable customers.</p>

<p><strong>3. Everyday interactions are harder than they should be:</strong> 66% find routine interactions stressful, with a strong preference for digital, flexible channels over phone-based communication. </p>

<p>Looking specifically at insurers, the industry has an opportunity to redefine the trust contract with consumers by: building transparency into underwriting to reduce fear and encourage disclosure of conditions; prioritising dignity and reasonable adjustments over speed of response in claims; closing the accessibility gap through multi-channel, flexible communication, and protocols that mean customers do not need to keep repeating details of mental health conditions.</p>

<p><strong>Emma Hickey of the IFoA Mental Health Working Party, said: </strong>&ldquo;When we began exploring mental health in the context of disability insurance, we wanted to understand how people experience interacting with financial services while managing a mental health condition.</p>

<p>This report highlights that non-disclosure is largely a rational, defensive behaviour. As an industry, we need to give customers confidence that disclosure will not automatically result in higher premiums or declined cover.</p>

<p>The same principles apply in claims. Taking the time to communicate in the ways people need, can transform often stressful interactions into supportive experiences.</p>

<p>If we design systems around trust, empathy and accessibility, we will better serve vulnerable customers and strengthen the perception of the industry as a whole.&quot;</p>

<p><strong>Paul Sweeting FIA C.Act, IFoA President, said: </strong>&ldquo;Being able to access financial services is a vital part of our day to day lives, but when people feel excluded by the way the system is set-up, this leads to imbalances across society. I encourage actuaries and those working in the financial services industry to act on the measures outlined in this report, to protect, empower and reassure customers.&rdquo; </p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/finance-sector-must-improve-support-for-mental-health-27067.htm</link>
<pubDate>Mon, 17 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>3 Life Events That Could Knock Your Retirement Off Course</title>
		<description><![CDATA[<p>Drawing on the report&rsquo;s findings, PensionBee highlights three increasingly common life events that can derail retirement adequacy: supporting adult children through the &lsquo;Bank of Mum and Dad&rsquo;, divorce and caring responsibilities. While very different, each can interrupt earnings, reduce pension contributions or delay long-term saving entirely, making it harder for people to build the retirement savings they need.</p>

<div><strong>Life event 1: The Bank of Mum and Dad </strong></div>

<div>For many parents, financial support doesn&rsquo;t end when their children leave school or university. Soaring housing costs and a difficult labour market mean 3.6 million adults aged 20 to 34 now live with their parents, while many more rely on ongoing financial help with rent, deposits or everyday living costs.</div>

<p>For some households, an adult child earning and contributing to bills can strengthen the family&rsquo;s finances. But for many others, the flow of support runs in the opposite direction. Parents who might otherwise be increasing pension contributions or preserving retirement savings are instead using their income and capital to support the next generation.</p>

<p>This creates a blind spot in how retirement adequacy is often measured. A household may appear financially secure on paper, yet that security depends on one generation continuing to support another. Equally, a parent with an apparently healthy pension may be quietly compromising their own retirement by reducing contributions or drawing on savings to help an adult child.</p>

<p><strong>Maike Currie, VP Personal Finance, PensionBee comments: </strong>&ldquo;Retirement adequacy isn&rsquo;t simply about how much money sits in a pension pot. It&rsquo;s also about the financial commitments that continue throughout our working lives. Supporting children is often one of the biggest of those commitments, and it's becoming an increasingly important part of the retirement picture.&rdquo;</p>

<div><strong>Life event 2: Divorce: a clean break versus a fair break</strong></div>

<div>While the family home tends to dominate divorce negotiations, pensions, often the second most valuable asset a couple owns, can be overlooked. Research cited in the Pensions Adequacy report highlights that more than a third of divorcees did not know the value of their own pension when they separated, while only 11% of those with an undrawn pension made arrangements to share it.</div>

<p>According to the report, while divorced men appear to retain larger pension pots after separation, divorced women consistently hold less pension wealth than their married counterparts. The gap widens in the years before retirement, reflecting the cumulative impact of lower earnings, career breaks and caring responsibilities, with many women appearing to draw on their pensions early simply to make ends meet. </p>

<p><strong>Maike Currie comments: </strong>&ldquo;Divorce is one of the biggest emotional and financial events in a person&rsquo;s life with pensions often treated as an afterthought. People naturally focus on the family home because it&rsquo;s tangible, but retirement can last 20 or 30 years. Giving up pension wealth without understanding its long-term value can have consequences that last a lifetime.&rdquo;</p>

<div><strong>Life event 3: Caring responsibilities</strong></div>

<div>Retirement adequacy is shaped not only by what people earn, but also by who they care for. Whether it&rsquo;s raising children, supporting an aging parent or juggling both at the same time, caring responsibilities can interrupt careers, reduce earnings and weaken long-term pension saving. The result is that periods of unpaid care have become one of the biggest drivers of the gender pension gap as caring responsibilities are more frequently borne by women.</div>

<p>The Pensions Adequacy report argues that better support for carers could help reduce these inequalities. Options include state-funded pension contributions during periods of unpaid care, pension top-ups linked to recognised caring responsibilities, or measures to help maintain pension saving during extended leave. While each would involve costs and practical challenges, the report concludes they could help protect retirement outcomes for people undertaking socially valuable but unpaid work.</p>

<p><strong>Maike Currie comments:</strong> &ldquo;The hardest conversation many of us will ever have with our parents isn&rsquo;t about inheritance, but care. Yet too often that conversation only happens after a crisis, when choices are already limited. Women are particularly exposed. Many experience the motherhood penalty in their thirties, only to encounter the good daughter penalty in their forties and fifties as they become the default carer for ageing parents. The timing is brutal, arriving just as careers and pension saving should be accelerating.</p>

<p>&ldquo;Caring is one of the biggest hidden risks to retirement adequacy. If we value unpaid care, and we should, we also need to think about how we protect the long-term financial security of the people providing it.&rdquo;</p>

<p> </p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/3-life-events-that-could-knock-your-retirement-off-course-27065.htm</link>
<pubDate>Mon, 17 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Renting Rooms This Summer May Invalidate Your Home Insurance</title>
		<description><![CDATA[<p>Uswitch home insurance experts highlight the potential insurance risks of renting out a room or full home , and the importance of having the right cover.</p>

<p>As demand for short-term lets peaks over the summer months, more homeowners living in tourist hotspots are cashing in by renting out their spare rooms (or entire home). But Uswitch home insurance experts are warning homeowners about the overlooked risk of renting a room out: without the right home insurance policy in place, you could invalidate your cover if something goes wrong. </p>

<p>In 2025, the UK saw nearly 101 million guest nights spent in short-term lets, 14% (14,143,560) of which took place in August alone. Those offering home rentals may not realise that standard home insurance is designed for owner-occupiers, not paid guests, and hosting without informing your insurer, or not having a specialist short-term rental policy in place, could leave you both out of pocket and uninsured.</p>

<p>If you rent out a room or your whole home to guests - even for a single weekend - your insurer may not cover you for accidental damage, theft or injury caused by a guest. In some cases, it could even cancel your policy altogether if you didn't declare that you were hosting.</p>

<p>While rental platforms like Airbnb offer their own protection, Uswitch experts say this isn&rsquo;t a substitute for home insurance, and it&rsquo;s important to ensure you have appropriate cover. Airbnb's AirCover for Hosts offers up to &pound;2,234,250 in host damage protection and &pound;744,750 in host liability cover, but it won't cover events such as lost booking income or high-value items. </p>

<div><strong>Top tips for homeowners renting out rooms or properties this summer:</strong></div>

<div><em>Always inform your insurer. This is essential to keep your policy valid.</em></div>

<div><em>If you have a mortgage, review it to make sure you are allowed to conduct short-term lets. </em></div>

<div><em>Don't rely on a rental platform&rsquo;s cover alone. While protection like Airbnb&rsquo;s AirCover is a helpful safety net, it has limitations and gaps that you need to watch out for.</em></div>

<div><em>Consider specialist insurance. If your standard home insurance doesn&rsquo;t cover renting out your home but you still want to do so, dedicated policies,such as holiday let insurance, are available. These can fill the gaps left by your existing insurance.</em></div>

<p><strong>Uswitch insurance expert, Leoni Moninska, comments: </strong>&ldquo;Renting out a spare room or your home, even if it&rsquo;s just a short-term rental, could invalidate your home insurance. Most standard policies don&rsquo;t cover short-term rentals, as they are designed for people living in their own home full-time and the risks associated are different. </p>

<p>&ldquo;If you&rsquo;re looking to make additional income through renting out a room or your whole property, you should contact your home insurance provider and inform them, but also look into holiday or short-term let home insurance policies.</p>

<p>&ldquo;Platforms like Airbnb do offer some protection, but there are limits. Their cover won't replace lost income if a booking falls through, and it may not stretch to your most valuable belongings. Having the right insurance in place helps avoid invalidating your policy and ensures you&rsquo;re protected if something goes wrong, so you can enjoy the extra income from hosting without the worry.&quot;</p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/renting-rooms-this-summer-may-invalidate-your-home-insurance-27061.htm</link>
<pubDate>Fri, 14 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Your Organization Is Investing In Ai  Where s The Value </title>
		<description><![CDATA[<p><strong>By Asumi Ishibashi, Managing Director, John Rothera, Senior Director - Employee Experience and Anke Stone, Director - Employee Experience, WTW</strong></p>

<p>Yet expectation and impact are often misaligned. The real problem is that AI is transforming work faster than organizations can redesign it and true employee AI adoption is lagging.</p>

<p>AI is reshaping how work gets done and how decisions are made. The challenge is no longer getting AI into people's hands. It's understanding whether the conditions exist to make that adoption stick at scale. So the questions have shifted. Which behaviors matter most? How do we know whether adoption is creating value? And how do we demonstrate ROI and business impact beyond usage metrics?</p>

<p>AI changes what&rsquo;s possible but people and behavior determine what&rsquo;s realized. The gap between the two is where organizations struggle. Deployment isn&rsquo;t adoption, and adoption isn&rsquo;t value. That&rsquo;s a distinction many AI strategies gloss over, at real cost.</p>

<div><strong>Why the gap persists</strong></div>

<div>The adoption gap grows because AI is often approached like any other transformation. In most transformations, the focus is on what is changing: a new tool, a new process or a new system. AI goes deeper. It changes how work is structured, how teams work, how decisions get made, and what should remain human-led. That&rsquo;s why the same playbook that worked for previous transformations starts to break down.</div>

<p>Many organizations are still missing the foundational elements that make AI transformation credible at scale: clear transformation objectives, a compelling workforce vision, visibility into how work is changing, an intentional focus on accelerating behavior change from the outset and a refined employee value proposition. When those pieces are missing, AI shows up as a scattered set of tools and random ad-hoc experimentation, rather than a coordinated shift.</p>

<p>This disconnect becomes visible quickly. Leadership direction feels unclear. Trust and confidence start to wane. Skills and support do not match the pace of change. AI still feels bolted on rather than built into the workflow.</p>

<p>Organizations that treat these signals as noise and respond with another round of generic training and enterprise-wide communications often struggle to move value beyond the pilot stage.</p>

<p>This is where the gap between AI activity and business value tends to widen. Most organizations are good at putting tools into people&rsquo;s hands. Far fewer are systematic about turning that activity into sustained performance.</p>

<div><strong>What you see when you look closely at adoption</strong></div>

<div>Employees don&rsquo;t adopt AI in a uniform way. The change is personal. They cluster into distinct behavioral profiles:</div>

<div> </div>

<div><em><strong>High impact:</strong> using AI broadly, with clear gains in speed, quality or outcomes</em></div>

<div><em><strong>Fragile experimenting:</strong> using it often, but struggling to translate that into value</em></div>

<div><em><strong>Untapped value: </strong>seeing the potential, but not embedding it into real work</em></div>

<div><em><strong>Stuck:</strong> limited use, with little perceived relevance</em></div>

<p>These AI adoption profiles exist in almost every organization; each group faces different barriers and requires a different intervention. And that's not all, segments within an organization clearly differentiate on the prevalence of these behavioral profiles. Responding to all four with the same playbook is one of the fastest ways to stall progress.</p>

<div><strong>What actions can you take</strong></div>

<div>So how do you understand where adoption is creating value, where it is stalling and what is driving the difference? The answer lies beyond usage metrics. While they can show who is using AI and how often, they reveal little about whether people are working differently, making better decisions or achieving better outcomes as a result.</div>

<p>Four conditions consistently shape AI adoption:</p>

<div><em><strong>Culture: </strong>do people feel safe and motivated to use AI?</em></div>

<div><em><strong>Direction:</strong> is there clear leadership intent on how and where AI should be used and where it shouldn&rsquo;t?</em></div>

<div><em><strong>Enablement: </strong>do people have the skills, tools and practical support to apply it well and responsibly?</em></div>

<div><em><strong>Integration:</strong> does AI fit naturally into how work gets done, or sit alongside it?</em></div>

<p>The challenge is knowing whether those shifts are actually happening, and this is where a data-driven diagnostics becomes critical. Usage data can show activity, but it is critical to understand the perceived value employees see in using AI. You need intelligence related to the four conditions to fully understand how behavior is changing across the organization. Where are new ways of working taking hold? Where is adoption stalling? Which conditions are accelerating progress and which are slowing it down? Diagnostics should lead to action.</p>

<div><em>If employees are stuck, start by making AI relevant to real work.</em></div>

<div><em>If they are experimenting but not seeing value, help teams turn experimentation into repeatable practices.</em></div>

<div><em>If they see the potential but are not embedding AI, redesign the workflow so AI fits naturally into how work gets done.</em></div>

<p>If some groups are already creating value, study what they are doing differently and scale those behaviors across the organization.</p>

<p>The same logic applies to the conditions that shape adoption. For example, low culture scores call for safer experimentation and visible leadership support. Low direction scores call for clearer guidance on where AI should and should not be used. Low enablement scores call for role-based capability building, not generic training. Low integration scores call for workflow redesign, not more communications.</p>

<p>The point is not to launch more activity. It is to target the few actions most likely to shift behavior, increase perceived value and make AI part of how work gets done.</p>

<div><strong>Closing the gap between activity and value</strong></div>

<div>The most important AI question is no longer Who is using it? It's What is changing because of it? The organizations pulling ahead are looking beyond usage metrics to understand where adoption is creating value, where it is stalling and what is driving the difference. They identify the behaviors that drive performance and create the conditions for those behaviors to take hold.</div>

<p>The winners in the age of AI won't necessarily be the organizations using AI the most. They'll be the ones that understand how work is changing, where value is being created and what it takes to scale it.</p>

<p>Because while AI may reshape work, it is people who determine whether that transformation delivers results.</p>

<p> </p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/your-organization-is-investing-in-ai--where-s-the-value--27063.htm</link>
<pubDate>Fri, 14 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Ceo Banned For Falsifying Files Trying To Buy Football Club</title>
		<description><![CDATA[<p>During his time at BHAM, Mr Taylor made misleading statements and falsified information during 2 separate attempted acquisitions.</p>

<p>While attempting to acquire a UK bank, Mr Taylor falsified, or arranged to be falsified, documents claiming to be the owner of a bond portfolio worth approximately &euro;200m.</p>

<p>Ms Toni knowingly assisted Mr Taylor by making misleading statements to the bank and by helping falsify the documents. Mr Taylor knew, and Ms Toni understood that it was likely, that these statements and documents would be relied upon by the FCA and Prudential Regulation Authority (PRA) as part of their assessment for the proposed acquisition. </p>

<p>Ms Toni was interviewed as part of BHAM&rsquo;s internal investigation into the events. During the investigation, she denied providing misleading statements and the creation of false documents. </p>

<p>On a separate occasion, Mr Taylor tried to acquire Reading Football Club. Mr Taylor made misleading statements, again falsely claiming to own the &euro;200m bond portfolio to make the acquisition. </p>

<p>The FCA found that Mr Taylor and Ms Toni acted dishonestly over an extended period. Their actions were intended to mislead BHAM colleagues, counterparties and regulators. </p>

<p><strong>Therese Chambers, joint executive director of enforcement and market oversight at the FCA, said: </strong>&quot;Trust in financial services relies on those working in it to be honest. Mr Taylor and Ms Toni fell woefully short of even this minimum expectation. They lied and lied again, first for commercial gain and then to cover their backs. They have no place in our industry.&quot;</p>

<p> </p>

<div><em>Read the <a href="https://www.fca.org.uk/publication/final-notices/paul-vincent-taylor-2026.pdf">final notice for Paul Taylor.</a></em></div>

<div><em>Read the <a href="https://www.fca.org.uk/publication/final-notices/esmeralda-toni-2026.pdf">final notice for Esmeralda Toni</a>.</em></div>

<div><em>Between 14 February 2022 and 17 January 2025, Mr Taylor was a chief executive and executive director at Blue Horizon Asset Management Ltd.</em></div>

<div><em>Between 14 February 2022 and 16 December 2025, Ms Toni was an executive director at Blue Horizon Asset Management Ltd.  </em></div>

<div><em>The FCA found that Mr Taylor and Ms Toni breached Individual Conduct Rule 1, which requires individuals to act with integrity.</em></div>

<div><em>Mr Taylor agreed to resolve the matter and qualified for a 30% discount under the FCA&rsquo;s settlement procedures. Without this discount, the financial penalty would have been &pound;698,600.</em></div>

<div><em>Ms Toni agreed to resolve the matter and qualified for a 30% discount under the FCA settlement procedures. Without the discount, the financial penalty would have been &pound;173,100.</em></div>

<div><em>The FCA has banned Mr Taylor and Ms Toni from performing any function in relation to regulated activities, having concluded that they are not fit and proper persons.</em></div>

<div><em>The FCA has the power to impose financial penalties under section 66 of the Financial Services and Markets Act 2000 and to prohibit individuals under section 56 of that act.</em></div>

<div><em>The notices refer to certain parties in addition to Mr Taylor and Ms Toni. Any reference to those parties is made solely to provide relevant factual context to the findings set out in the notices and should not be taken as criticism by the FCA of their conduct.</em></div>

<div> </div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/ceo-banned-for-falsifying-files-trying-to-buy-football-club-27062.htm</link>
<pubDate>Fri, 14 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Royal London Complete Buyin With Royal Horticultural Society</title>
		<description><![CDATA[<p>This buy-in secures the benefits of 230 members and reflects Royal London&rsquo;s continued commitment to supporting trustees across a broad range of pension scheme sizes, ranging from around &pound;10 million to &pound;360 million.</p>

<p>Royal London met with the trustee board earlier in the year. This evolved into a sole insurer framework which delivered a tailored solution for the trustees at an attractive pricing level. The Trustees were advised by XPS and Stephenson Harwood.</p>

<p><strong>Beatrice Male, BPA Origination Lead at Royal London, said: </strong>&quot;This buy-in with the Royal Horticultural Society 1974 Pension Scheme brings together two organisations with a strong sense of purpose and hundreds of years of history.</p>

<p>&ldquo;That shared perspective was clear from our first engagement with the trustees and helped us deliver a bespoke solution to meet their objectives. We&rsquo;re proud to have earned their trust and look forward to delivering the high-quality service and stewardship their members deserve for many years to come.&rdquo;</p>

<p><strong>Ash Williams, Partner at XPS, said: </strong>&ldquo;We are pleased to have led the Trustees and the RHS through the transaction, which has resulted in improved security for the members of the Scheme at a competitive price. The Scheme had a number of complexities to consider but the collaborative work of the Trustees, the RHS and the advisory team has led to an excellent outcome with an insurer that puts customer service first, which was one of the key criteria for the Trustees.&rdquo;</p>

<p><strong>Ingrid Fernandes, Director of Finance for RHS and on behalf of the Trustee, said: </strong>&ldquo;We are delighted to be partnering with Royal London on this important step for the Royal Horticultural Society 1974 Pension Scheme. Royal London&rsquo;s expertise, professionalism and collaborative approach have been evident throughout the process, giving us confidence that our members&rsquo; benefits will continue to be supported by a strong and trusted insurer.</p>

<p>&ldquo;This transaction represents an important milestone for both the Scheme and the RHS. By increasing certainty around the charity&rsquo;s future pension obligations and strengthening the long-term financial sustainability, it supports our ability to focus on delivering our charitable mission. This includes continued investment in our world-renowned gardens, scientific research, educational programmes and our work to inspire more people to garden and connect with nature.</p>

<p>&ldquo;We look forward to building on our relationship with Royal London as we secure an even stronger future for the Scheme and its members, while helping to ensure the RHS can continue delivering lasting public benefit for generations to come.&rdquo;</p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/royal-london-complete-buyin-with-royal-horticultural-society-27058.htm</link>
<pubDate>Thu, 13 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Taxable Pension Withdrawals Top  75bn For Under 65s</title>
		<description><![CDATA[<div>This group of &rsquo;early accessors&rsquo; account for seven in 10 (70%) of the 3.42 million pension savers who have taken taxable payments from their pension pots.</div>

<div> </div>

<div>&pound;75.5 billion has been taken from pensions as taxable flexible payments since 2015 by individuals who were under 65 when they took a taxable payment, as savers take advantage of flexibilities in the pension system to drawdown on their later-life savings.</div>

<div> </div>

<div>The number of under 65s taking a taxable pension payment rose by 7% from 602,000 in 2024/25 to 644,000 in 2025/6, with the total value of taxable payments to that group increasing by &pound;1.1bn over the same time period &ndash; from &pound;10.3bn in 2024/25 to &pound;11.4bn in 2025/26.</div>

<div> </div>

<div>Crucially, these payments do not include the tax-free lump sum, highlighting the scale of early pension access, and prompting questions about the sustainability of drawdown levels and long-term implications for retirement income security.</div>

<div> </div>

<div>Taxable pension withdrawals can have significant consequences for people accessing their pension savings while they are still working.</div>

<div> </div>

<div>While savers can usually take up to 25% of their pension tax-free, further withdrawals are added to their other taxable income and could push them into a higher tax band. Flexibly accessing taxable pension income can also trigger the Money Purchase Annual Allowance, reducing the amount that can subsequently be paid into defined contribution pensions with tax relief from &pound;60,000 to &pound;10,000 a year.</div>

<div> </div>

<div><strong>Peter Roos, Chief Commercial Officer at Lumera, commented:</strong> &ldquo;Pension freedoms have given millions of people much greater flexibility over how and when they use their retirement savings but accessing a pension early can have important and sometimes overlooked consequences. The concern is not necessarily that people are accessing their pensions before 65 &ndash; for many, doing so will be entirely appropriate &ndash; but whether they fully understand the tax implications and the potential impact on their longer-term retirement income. Taking money out earlier also means losing the potential investment growth on those savings and leaving a smaller pot to support what could be several decades in retirement.&rdquo;</div>

<p> </p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/taxable-pension-withdrawals-top--75bn-for-under-65s-27056.htm</link>
<pubDate>Thu, 13 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Five Years On From The Start Of The Cost of living Crisis</title>
		<description><![CDATA[<p><strong>Sarah Coles, head of personal finance at AJ Bell, comments:</strong></p>

<p>&ldquo;The cost-of-living crisis has just turned five, and shows signs of being every bit as tenacious and destructive as most five-year-olds. When inflation started to kick off back in August 2021, we couldn&rsquo;t have known what was to come, with runaway price rises sparking interest rate hikes that had a dramatic impact on our finances. The immediate impact of the pandemic was supercharged by geopolitical turmoil that sent oil prices soaring, and has kept the pressure up ever since.</p>

<p>&ldquo;Most of the time we measure how things change year to year, so it can be difficult to spot how much our finances have been altered over the past five. That&rsquo;s why it&rsquo;s worth taking stock and understanding the cumulative impact, and what it means for us. For some people there has been a silver lining, thanks to the impact on savings and annuities, but for others there have just been particularly gloomy dark clouds.</p>

<div><strong>The impact on wages</strong></div>

<div>&ldquo;Over this period, average wages and prices have actually risen by a fairly similar amount &ndash; around 28%. However, this hides the horrible period early in the cost-of-living crisis, between spring 2022 and spring 2023, when inflation raced away and wages failed to keep pace, so our budgets were stretched ever-tighter.</div>

<p>&ldquo;In the public sector it was even tougher, because it took far longer for wages to start to pick up after prices soared. So, for example at the start of 2022, wages in the private sector were up 8.5% over the year and in the public sector they were up just 1.7%. It took until 2023 for public sector pay inflation to overtake the private sector and start making up the lost ground.</p>

<p><img alt="" src="https://www.actuarialpost.co.uk/images/pic_AJBellCOL1308261.jpg" style="height:313px; width:517px" /></p>

<p><span style="font-size:11px"><em>Source: ONS</em></span></p>

<div><strong>What it has meant for existing pension incomes</strong></div>

<div>&ldquo;Prices have risen almost 29% since August 2021, which will have been a bitter blow for anyone who was already relying on a level annuity, where the income is fixed rather than tracking inflation. For example, someone with a &pound;10,000 annual annuity income wouldn&rsquo;t have seen the payments change, but their money would be spread far more thinly, because &pound;10,000 had the spending power of just &pound;7,770 in August 2021. It&rsquo;s a demonstration of the devastating impact of inflation on level annuity incomes, which is particularly alarming given that around four in five annuities bought in 2025 were level.</div>

<p>&ldquo;The state pension income has risen more. In August 2021 it paid &pound;179.60 a week, whereas now it has risen to &pound;241.30 a week &ndash; up just over 34%. This is because the past three rises were based on earnings growth, which was higher than CPI inflation at the time. The biggest bump was in April 2023, when it increased by 10.1% with prices.</p>

<p>&ldquo;If the state pension, inflation-linked pensions, annuities or drawdown make up the bulk of your income, there&rsquo;s a decent chance it kept up with inflation. Meanwhile, anyone whose retirement income is dominated by income from a level annuity will have faced a painful financial squeeze. For those with flexible income from a drawdown arrangement, the value of their pension investments will have fluctuated but strong market returns over the period ought to have offered good protection against rising prices.</p>

<div>Silver lining for new annuities</div>

<div>&ldquo;For those in the market for a new annuity, this has been a particularly strong period. They tend to follow gilt yields, which usually rise with interest rates &ndash; so these shot up as rates climbed, and they have remained high ever since. They were in the doldrums back in 2021, where a healthy 65-year-old buying a level single-life annuity with a &pound;100,000 pot might get up to around &pound;4,900 in income a year. This climbed quickly until in 2023 you could get up to around &pound;7,200 a year, and has risen with inflation concerns more recently to hit as much as around &pound;7,800 in August. That&rsquo;s around 60% higher than in 2021.</div>

<p>&ldquo;However, although the number of people buying annuities when they first access their pot has risen, it&rsquo;s still only used by about 10% of people at this stage. Drawdown continues to be the most popular retirement income solution, partly because retirees value the flexibility and the fact you can leave a portion of the money invested, offering a chance to keep pace with inflation. It&rsquo;s why so many people consider drawdown, or a combination of drawdown and annuities as they go through retirement.</p>

<div>How it has affected savings</div>

<div>&ldquo;Savers have been basking in the glow of the silver lining ever since prices rocketed and the Bank of England started stepping up rates. In August 2021 rates were at just 0.1% and after they started climbing in December, they swiftly rose from 0.25% to 5.25% by August 2023 &ndash; where they spent the following year.</div>

<p>&ldquo;Savings rates followed suit. The average new fixed rate savings account, according to the Bank of England, was offering 0.25% in August 2021, 1.78% a year later and 5.1% in August 2023. It peaked at 5.23% in October 2023. Unsurprisingly, the mini-Budget of September 2022 sparked the steepest rise in average fixed rates, but the pace was rapid across the period. The average has fallen back to 4.27%, but remains strong thanks to competition in the market.</p>

<p>&ldquo;Rates are expected to rise again in the coming months, but this isn&rsquo;t likely to be a re-run of the savings glory years. Two rises are being pencilled in by the end of next spring, so savings rates could pick up. However, an awful lot depends on uncertain global politics, so savers shouldn&rsquo;t hang on in the hopes of seeing rates surge again. If you need a fixed rate deal, there are plenty of strong rates around right now.</p>

<div><strong>How mortgages have changed</strong></div>

<div>&ldquo;Mortgage borrowers have seen costs climb alarmingly over the past five years. Bank of England figures show that the average mortgage rate on new deals rose from just 1.82% in August 2021 to a peak of 5.34% in November 2023. The most eye-watering hikes came in the aftermath of the mini-Budget in September 2022, when the mortgage market reeled from the bond yield surge, pushing swap rates through the roof.</div>

<p>&ldquo;Depending on whether they had a fixed or variable rate mortgage, when they fixed and how long they fixed for, this could have been a spectacularly painful period for borrowers. Someone with a &pound;200,000 repayment mortgage over 25 years at 1.82% could expect to pay &pound;831 a month. Meanwhile, someone with the same mortgage at 5.34% could expect to pay &pound;1,209 &ndash; that&rsquo;s almost 50% more.</p>

<p>&ldquo;Rates have fallen since the peak, trending downwards from the end of 2023 to spring this year. They&rsquo;ve climbed since, in the wake of the Iran war, to an average of 4.35%. If rates rise very slowly as expected into the spring next year, we&rsquo;re likely to see mortgage rates remain higher for longer. It&rsquo;ll take a calmer world with fewer inflation fears before falls are on the cards.</p>

<p>&ldquo;It means anyone on a variable rate deal shouldn&rsquo;t hold their breath for life to get cheaper, and anyone on a fixed rate mortgage who is coming up for a remortgage should hedge their bets. You can agree a rate up to six months before your deal expires, and if rates rise as expected you have locked in a bargain. If rates surprise on the downside, and better deals emerge, you can still shop around closer to the time.&rdquo;</p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/five-years-on-from-the-start-of-the-cost-of-living-crisis-27060.htm</link>
<pubDate>Thu, 13 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Human Rights Risks  The Implications For Long term Investors</title>
		<description><![CDATA[<p><strong>By Tashemia Glen, RI Associate Consultant, Hymans Robertson</strong></p>

<p>We also touch on how asset owners can take these risks into account, particularly when engaging with asset managers.</p>

<div><strong>How are asset owners exposed to human rights issues?</strong></div>

<div>Exposure to human rights issues can arise from investing in companies with operations or supply chains linked to conflict-affected or high-risk regions, or from investment companies without robust labour practices. </div>

<p>Human rights issues can arise across sectors, geographies and asset classes. The risks can be direct, such as workplace safety failures, or indirectly, through exposure to suppliers linked to forced labour, child labour, unsafe working conditions or community harm. Where companies fail to identify and manage human rights risks, the consequences can become financial. They may include litigation, regulatory penalties, operational disruption, remediation costs, loss of contracts, higher financing costs, weaker consumer trust and, in some cases, a lower company valuation.</p>

<p>Supply chains are often long, fragmented and data-poor, meaning investors may have exposure to labour rights risks that are not immediately apparent. MSCI research published in December 2025 found that only 3% of companies in the MSCI ACWI Index reported on modern slavery risks, while nearly 40% may have exposure to forced or child labour somewhere in their value chains.</p>

<div><strong>Regulatory change driving accountability</strong></div>

<div>This is becoming more relevant as regulation and market practice move towards greater supply chain transparency and holding companies accountable. The EU Corporate Sustainability Due Diligence Directive, for example, is designed to require in-scope companies to identify, prevent, mitigate and remediate adverse human rights and environmental impacts in their operations and chains of activities. The directive introduced financial penalties for non-compliance, highlighting the potential financial and reputational risks for investors. </div>

<p>For asset owners, this underlines the importance of asking managers how they identify, prioritise and act on social risks. A lack of perfect data should not mean inaction. It should prompt better questions about due diligence, escalation, engagement outcomes and how managers use the information that is available. The DWP's 2024 Taskforce on Social Factors guidance reinforces this by highlighting labour rights, health and safety, supply chain issues and modern slavery as social factors that may be financially material for pension schemes.</p>

<div><strong>Case study: Boohoo </strong></div>

<div>In July 2020, allegations were published about poor working conditions and low pay in parts of Boohoo's Leicester supply chain. Boohoo commissioned an independent review, which found that allegations of poor working practices were substantially true and that the monitoring of the supply chain had been inadequate. The allegations were followed by a 42% fall in Boohoo's share price.</div>

<p>The longer-term significance for investors extends beyond the initial market reaction, with damaged trust in the company's governance and oversight processes, contributing to ongoing reputational challenges and heightened stakeholder scrutiny. In 2024, a group of institutional investors brought legal proceedings alleging that Boohoo had failed to adequately disclose information relating to working conditions within its Leicester supply chain. By July 2026, the reported value of claims had risen to &pound;245m. Boohoo strongly contests the allegations and intends to defend the claim.  </p>

<div><strong>Case study: Child labour in the cocoa supply chain</strong></div>

<div>Child labour in West African cocoa supply chains is not a new issue, but recent litigation demonstrates that it remains financially relevant. In 2025 and 2026, a series of legal actions were brought against major confectionery and cocoa companies, alleging they had failed to adequately address or disclose child labour risks within their supply chains.</div>

<p>While the allegations are disputed, the cases highlight how human rights risks can translate into litigation costs, reputational damage, regulatory scrutiny and increased due diligence obligations.</p>

<div><strong>What does this mean for asset owners?</strong></div>

<div>These examples demonstrate how human rights issues are translated into financial risks in different ways. In some cases, impacts may be linked to a specific event, while in others, they arise through longstanding issues that take years to come to light. The financial consequences may not always be immediate or easy to quantify, but can emerge over time. </div>

<p>For asset owners, the challenge is how to deal with these complex and underreported issues and consider what to do, given limited time and resources. Most asset owners rely on their managers to identify, monitor and engage on human rights risks across portfolios &ndash; so it&rsquo;s incumbent on asset owners to hold their managers to account. </p>

<p>Practically, this means asking challenging questions of managers. How do they identify and prioritise human rights risks, engage with companies on issues such as labour rights, modern slavery and supply chain oversight? How do they demonstrate that these risks are being considered as part of investment decision-making and stewardship? </p>

<p>We are currently assessing how asset managers identify, manage and engage on modern slavery risks across listed equities and listed credit, with the findings designed to help asset owners ask better questions and strengthen oversight. Look out for the upcoming paper, where we&rsquo;ll share our key findings and practical considerations for engaging with managers.</p>

<div><strong>Further information</strong></div>

<div>Measuring exposure to human rights risks remains challenging, but a growing range of frameworks and benchmarks are helping to improve transparency. Resources such as the UN Guiding Principles on Business and Human Rights, the Corporate Human Rights Benchmark and the Taskforce on Inequality and Social-related Financial Disclosures (TISFD) provide valuable insights into how companies identify, manage and disclose human rights risks. For asset owners looking to deepen their understanding, these frameworks can support more informed conversations with managers about their approach to managing social risks and their stewardship activities.</div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/human-rights-risks--the-implications-for-long-term-investors-27059.htm</link>
<pubDate>Thu, 13 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Growth Focused Pension Strategy Improves July 2026 Funding</title>
		<description><![CDATA[<p>The Broadstone Sirius Index has published its July tracking for a &lsquo;growth focused&rsquo; and a more conservative &lsquo;matching focused&rsquo; investment strategy against a low dependency basis. Both schemes started 90.0% funded at the start of 2026.</p>

<p>Reporting its update for July 2026, the Broadstone Sirius Index found that the &lsquo;growth focused&rsquo; scheme performed best through the month, increasing its funding level by a full percentage point to 94.1%.</p>

<p>It continues to outperform the funding level of the &lsquo;matching focused&rsquo; scheme so far in 2026. Despite some small movements through the month, the &lsquo;matching focused&rsquo; scheme ended July on the same funding level that it ended June on &ndash; 89.9%</p>

<p>The &lsquo;growth focused&rsquo; scheme has generally outperformed the &lsquo;matching focused&rsquo; scheme since April, with its underhedged position benefiting in a rising yield environment and greater exposure to return-seeking assets which performed well over the period.</p>

<p><img alt="" src="https://www.actuarialpost.co.uk/images/pic_BroadstoneSiriusGrowth1308261.jpg" style="height:293px; width:600px" /></p>

<p><strong>Chris Rice, Head of Trustee Services at Broadstone, commented:</strong> &ldquo;July provided another positive month for our &lsquo;growth focused&rsquo; scheme, which benefitted from its underhedged position and moved 4.1 percentage points above its starting funding level for the year.</p>

<p>&ldquo;However, the contrasting performance of the two strategies should not be interpreted as evidence that taking greater investment risk will always deliver a better outcome. The recent gains achieved by the &lsquo;growth focused&rsquo; scheme could be vulnerable to a market correction, while the &lsquo;matching focused&rsquo; strategy is deliberately designed to provide greater stability and protection against changes in liability values.</p>

<p>&ldquo;The appropriate balance between growth and matching assets will depend on each scheme&rsquo;s funding position, covenant strength and liquidity requirements. Trustees should therefore avoid making decisions based on a few months of performance.</p>

<p>&ldquo;For schemes that have benefited from recent market strength, now may be an appropriate time to review their long-term objectives. Clear triggers and a well-defined journey plan can help trustees reduce risk at the right time rather than relying on market conditions remaining favourable.&rdquo;</p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/growth-focused-pension-strategy-improves-july-2026-funding-27057.htm</link>
<pubDate>Thu, 13 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>The Data Gap Driving Up Chinese Ev Insurance Premiums</title>
		<description><![CDATA[<p><strong>By Tom Clarke, Director of Motor Strategy, LexisNexis Risk Solutions</strong></p>

<p>However, UK motor insurance providers are being asked to price vehicles they have never insured, repaired or settled claims on, with limited visibility of how construction quality, safety systems and component availability will impact repair costs. Underprice and loss ratios may deteriorate as claims experience emerges. Overprice and insurance providers risk ceding a fast-growing segment to competitors willing to take a different view of the risk.</p>

<p>At the same time, ADAS (advanced driver assistance systems) specifications vary significantly across models and trim levels. Insights from the recent China Auto Show underline how rapidly Chinese manufacturers are introducing new models into global markets, with specifications that shift from one vehicle to the next and are frequently unverified at the point of quote.</p>

<div><strong>Pricing problems</strong></div>

<div>This lack of visibility has real consequences. Premiums for some Chinese EV models are running at close to triple those of equivalent European vehicles[iv], reflecting the uncertainty insurance providers face when they cannot accurately assess risk.</div>

<p>This is against a backdrop of motor claims severity inflation at 7% in 2026[v] partly driven by the growing complexity of repairing vehicles with advanced electronics and EV powertrains. Of the 36.7m cars on the road, c.12% are now hybrid or fully electric where costs to repair are significantly higher.[vi] Chinese EVs compound the claims conundrum further as parts for repairs can be difficult to source meaning higher average claim costs and greater pricing uncertainty.</p>

<div><strong>Addressing the data gap</strong></div>

<div>Two developments are beginning to address the data gap from different directions. VIN-level vehicle intelligence through LexisNexis&reg; Vehicle Build gives insurance providers insight into exactly how a specific vehicle is equipped &mdash; including the presence, specification and performance of specifications. Where fitment varies significantly across models, that level of specificity matters.</div>

<p>Thatcham Research is also working directly with Chinese OEMs to build a deeper, UK-specific evidence base around safety and repairability &mdash; most notably through its Vehicle Risk Rating (VRR) score. By making that intelligence accessible through LexisNexis Risk Solutions, a more powerful connected ecosystem is taking shape; one that combines OEM insight, independent validation and vehicle-level intelligence into a single, usable framework for insurers.</p>

<div><strong>Affordability Pressure</strong></div>

<div>Along with pricing accuracy, affordability of insurance as part of the total cost of car ownership is also a major consideration. Chinese EVs enter the market at attractive price points but for consumers, the true cost calculation factors for insurance and premiums for Chinese EV models remain significantly elevated as a direct consequence of the data gap and repairability uncertainty described above.</div>

<p>OEMs are increasingly aware of this dynamic, recognising that a competitive purchase price can be undermined by high running costs, and that insurance sits at the centre of that equation.</p>

<p>To help address these challenges, insurance providers need to understand not just what people drive but also how they drive.</p>

<div><strong>Driver scoring from connected car data</strong></div>

<div>In 2025, LexisNexis Risk Solutions announced a collaboration with Kia Europe to embed driving safety scoring insights in the Kia App &mdash; enabling drivers to better understand their behaviour, while giving participating insurers, with consumer consent, the ability to incorporate that data into pricing models. This enables more personalised insurance offerings and the potential for lower premiums to help reduce the total cost of ownership.</div>

<p>Kia has now deployed this driving safety scoring capability across all European markets. The feature is optional for drivers, yet adoption has reached approximately 35% of users, equating to around 400,000 drivers engaging with their safety score.</p>

<p>That level of voluntary engagement points to strong consumer appetite for greater visibility into driving behaviour and, by extension, greater control over what they pay for cover.</p>

<p>This also addresses affordability: helping drivers reduce their risk, improve their behaviour and ultimately lower their premiums, while contributing to safer roads overall.</p>

<p>As the UK car parc with older vehicles being driven longer and newer Chinese EVs entering the market, integrating driver intelligence alongside robust vehicle-level data will be essential &mdash; both to give insurance providers the confidence to price these vehicles competitively and to give consumers a realistic route to bringing those costs down.</p>

<div><strong>Closing the gap</strong></div>

<div>Chinese EVs are no longer a niche segment. They are becoming an increasing presence in the UK car parc, and the actuarial community requires data infrastructure that reflects that reality. The insurance providers best placed to compete in this market will be those who build that foundation earliest rather than waiting for claims experience along to provide answers for them.</div>

<div> </div>

<div><em>[i] New Automotive: <a href="https://storage.googleapis.com/public_download_assets/ecc_pdfs/20260703%20ECC%20June%202026.pdf">https://storage.googleapis.com/public_download_assets/ecc_pdfs/20260703%20ECC%20June%202026.pdf</a></em></div>

<div><span style="font-size:11px"><em>[ii] <a href="https://oxbowpartners.com/blog/shorter-cycles-lower-peaks-uk-motor-insurance/">https://oxbowpartners.com/blog/shorter-cycles-lower-peaks-uk-motor-insurance/</a></em></span></div>

<div><span style="font-size:11px"><em>[iii] <a href="https://www.smmt.co.uk/vehicle-data/car-registrations/">https://www.smmt.co.uk/vehicle-data/car-registrations/</a></em></span></div>

<div><span style="font-size:11px"><em>[iv] <a href="https://www.regit.cars/car-news/chinese-evs-cost-up-to-3x-more-to-insure-than-european-rivals-data-reveals">https://www.regit.cars/car-news/chinese-evs-cost-up-to-3x-more-to-insure-than-european-rivals-data-reveals</a></em></span></div>

<div><span style="font-size:11px"><em>[v] <a href="https://oxbowpartners.com/blog/shorter-cycles-lower-peaks-uk-motor-insurance/">https://oxbowpartners.com/blog/shorter-cycles-lower-peaks-uk-motor-insurance/</a></em></span></div>

<div><span style="font-size:11px"><em>[vi] <a href="https://oxbowpartners.com/blog/shorter-cycles-lower-peaks-uk-motor-insurance/">https://oxbowpartners.com/blog/shorter-cycles-lower-peaks-uk-motor-insurance/</a></em></span></div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/the-data-gap-driving-up-chinese-ev-insurance-premiums-27055.htm</link>
<pubDate>Wed, 12 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Retirement Adequacy Increasingly A Business Planning Risk</title>
		<description><![CDATA[<div>In its latest paper, <a href="https://www.actuarialpost.co.uk/downloads/cat_1/Hymans-retirement-adequacy-identifying-future-risks-in-your-workforce.pdf">Retirement adequacy: identifying future risks in your workforce</a>, the firm highlights how financial stress, changing retirement behaviours and an ageing workforce can affect employee productivity, absenteeism and workforce planning. The paper argues that retirement adequacy is no longer just a pensions issue, but a business challenge that employers need to understand and actively manage. Employers need to understand where adequacy risks exist within their workforce and take action now, before those challenges become harder and more costly to manage.</div>

<div> </div>

<div>Underpinned by its Guided Outcomes (GO) modelling, the leading pensions and financial services consultancy shows that significant numbers of employees may be at risk of inadequate retirement outcomes. The paper also explores how potential policy developments, including auto-enrolment reform and higher contribution requirements, could increase costs for employers while not necessarily delivering the best outcomes across an entire workforce. Understanding these risks now allows employers to take a more strategic and targeted approach before external pressures force change.</div>

<div> </div>

<div><strong>Commenting on the growing commercial impact of retirement adequacy, Mark Stansfield, Senior Actuarial Consultant, Hymans Robertson, said: </strong>&ldquo;Retirement adequacy is increasingly becoming a business issue, not just a pensions issue. Many employers are already dealing with the effects of employee financial stress and changing working and retirement patterns, all of which can impact productivity, workforce planning and long-term business performance. Employers can&rsquo;t afford to view inadequate retirement outcomes as something that sits outside their wider people strategy. To make informed decisions, they need a clear understanding of how retirement adequacy risks are affecting their own workforce.</div>

<div> </div>

<div>&ldquo;The challenge is that retirement adequacy risks are not spread evenly across an organisation. Some groups may be on track for good outcomes, while others face a much greater risk of falling short in retirement. Without understanding where those risks exist, employers can struggle to target support effectively or make the best use of their pension spend. That is why workforce-specific analysis is becoming increasingly important.</div>

<div> </div>

<div>&ldquo;There&rsquo;s also a risk of focusing solely on future policy changes. While potential future reforms such as changes to automatic enrolment and higher contribution requirements would increase employer costs, they may not solve the adequacy challenge for every workforce. Employers that understand their workforce today will be in a much stronger position to respond to future change, shape their own strategy and improve outcomes for both their business and their employees.&rdquo;</div>

<div> </div>

<div><strong>Commenting on the importance of considering adequacy alongside wider employee outcomes, Hannah English, Head of DC Corporate Consulting, Hymans Robertson, said: </strong>&ldquo;Retirement adequacy cannot be viewed as a narrow pensions issue. Employees need to balance long-term saving amongst day-to-day financial pressures. However, for many retirement saving still feels distant and many may fully start to understand the scale of any retirement shortfall once dashboards make their pension position more visible. That could change the conversation between employees and employers very quickly.</div>

<div> </div>

<div>&ldquo;Employers therefore need to think about pension design as part of a broader workforce strategy. The question is not simply whether contributions should rise, but whether current support is helping different groups achieve better retirement outcomes in a sustainable and fair way. By looking at the interaction between cost, adequacy and workforce demographics, employers can make more informed decisions about their strategies. This can avoid unintended consequences of poorly designed solutions and also aid in creating reward strategies that attract and retain talent.</div>

<div> </div>

<div>&ldquo;Spending time to understand the issue now could significantly reduce problems later. It gives employers time to adapt strategies, communicate clearly with employees and build a pension strategy that supports both the business and its workforce.&rdquo;</div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/retirement-adequacy-increasingly-a-business-planning-risk-27052.htm</link>
<pubDate>Wed, 12 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Healthcare Cash Plans Still Top In Fca s Gi Value Measures</title>
		<description><![CDATA[<div>Covered for life pet insurance saw a small increase in the regulator&rsquo;s value measures data with 62.8% of premiums paid out in claims, up from 58.6% the year prior. It marked the second highest value measure followed by motor insurance which registered a notable improvement with 59.1% of premiums paid out in claims (2024: 54.2%). Motor insurance also saw the highest claims acceptance rate with 98.7% of claims accepted in 2025.</div>

<div> </div>

<div><strong>Kathryn Moore, Senior Actuarial Director at Broadstone, commented:</strong> &ldquo;Healthcare cash plans continue to demonstrate strong value for policyholders, with more than two-thirds of premiums paid back out through claims in 2025 &ndash; the highest proportion across the general insurance products included in the FCA&rsquo;s value measures data.</div>

<div> </div>

<div>&ldquo;Motor insurance also saw a meaningful increase in the proportion premiums paid out in claim and it will be interesting to monitor this change moving forward as insurers continue to manage pressures from repair, parts and labour costs. Pet insurance has similarly moved in a positive direction, highlighting the value these policies can provide in protecting owners from potentially significant and recurring veterinary costs.</div>

<div> </div>

<div>&ldquo;Claims ratios are only one measure of value and should be considered alongside factors such as claims acceptance, coverage, exclusions and customer outcomes. However, the latest figures provide encouraging evidence that these products are delivering meaningful financial support when policyholders need to claim.&rdquo;</div>

<div> </div>

<div><strong><a href="https://www.fca.org.uk/data/general-insurance-value-measures-data-2025">FCA General Insurance Value Measures Data</a></strong></div>

<p> </p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/healthcare-cash-plans-still-top-in-fca-s-gi-value-measures-27051.htm</link>
<pubDate>Wed, 12 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Reforms Vital To Guard Pensions In Divorce And Cohabitation</title>
		<description><![CDATA[<div>Pensions often represent a household's largest or second-largest asset, yet historically they have been overlooked or undervalued compared to immediate needs like housing. The SPP recommends codifying the distinction between matrimonial and non-matrimonial property, placing pension needs on an equal statutory footing in financial remedy decisions, and extending pension sharing orders to qualifying cohabitants.</div>

<div> </div>

<div><strong>Key recommendations from the SPP&rsquo;s consultation response include:</strong></div>

<div> </div>

<div><strong>Leveraging Pensions Dashboards</strong></div>

<div>The SPP calls for verified Pension Dashboard records to become a standard part of court disclosure. In time, secure court access to dashboard data should be enabled to eliminate &quot;lost&quot; pension pots, speed up proceedings, and ensure full transparency.</div>

<div> </div>

<div><strong>Extending rights to cohabitants</strong></div>

<div>The SPP supports introducing pension sharing orders for qualifying cohabitants and extending eligibility for dependants&rsquo; pensions to cohabitants automatically, removing onerous proof-of-dependency hurdles.</div>

<div> </div>

<div><strong>Objective criteria & lead time</strong></div>

<div>To ensure smooth implementation, the SPP urges policymakers to establish clear, objective legal definitions for &quot;qualifying cohabitants&quot; especially given the upcoming 2027 Inheritance Tax changes relating to unused pensions, and to allow sufficient lead-in time for pension schemes to update processes and handle increased demand.</div>

<div> </div>

<div><strong>Oliver Topping, Chair of the SPP&rsquo;s Legislation Committee, said: </strong>&quot;Pensions are fundamentally long-term assets designed to provide security in retirement, yet they are too often overlooked during relationship breakdowns. This is frequently to the detriment of the financially weaker party who may have taken career breaks for caregiving.</div>

<div> </div>

<div>Pension needs should be given equal prominence in family law and vital protections such as pension sharing should be extended to cohabiting couples.</div>

<div> </div>

<div>Harnessing the new Pensions Dashboards programme for court disclosure would be a game-changer in ensuring full transparency.</div>

<div> </div>

<div>However, to make these reforms workable in practice, policymakers must provide clear, objective criteria for defining qualifying cohabitants and allow the pensions industry sufficient lead-in time to adapt.&quot;</div>

<div> </div>

<div><a href="https://the-spp.co.uk/document/spp-response-to-the-ministry-of-justice-consultation-a-fairer-end-to-relationships/">The SPP&rsquo;s consultation response is available in full, here:</a></div>

<div> </div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/reforms-vital-to-guard-pensions-in-divorce-and-cohabitation-27053.htm</link>
<pubDate>Wed, 12 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Two Thirds Expect To Rely On The State Pension In Retirement</title>
		<description><![CDATA[<p><strong>Helen Morrissey, head of retirement analysis, Hargreaves Lansdown: </strong>&ldquo;The state pension forms the very foundation of our retirement income - 66% of people admit they will rely on it &lsquo;to some extent&rsquo;. The level of reliance differs, with 9% saying they will be totally dependent on it while a further 19% say they will rely heavily on the benefit to meet their needs in retirement.</p>

<p>A full new state pension is currently &pound;241.30 per week. While this will be sufficient for many people to cover their essentials, for the vast majority it will be nowhere near enough to live the lifestyle they enjoyed while they were working. In addition, the age at which you receive the state pension is currently on the rise and is expected to hit 67 in 2028. It&rsquo;s then expected to start rising to age 68 between 2044-46, though the ongoing review into the state pension age could bring this forward. The reality is that if you want a retirement where you can afford more than just the essentials, or you want the flexibility to retire early, then you will need to make the most of your pension.</p>

<p>Analysis HL carried out with Oxford Economics showed 92% of people can meet their essential needs in retirement with a combination of the state pension and their pension savings. However, if you take the state pension out of the equation this falls dramatically to around 42% so the state pension continues to do most of the heavy lifting.</p>

<p>The good news is that auto-enrolment has boosted the number of people contributing to a workplace pension. This should mean that, over time, the number of people totally or largely reliant on the state pension will drop. However, if you want to fulfil all your plans for your retirement years, then it&rsquo;s worth looking at how you can boost your pension.</p>

<p>Even relatively small changes can make a big difference. A 22-year-old earning &pound;25,000 per year, contributing at auto-enrolment minimums throughout their career, could have a pension worth &pound;477,500 by the age of 68. However, if they decided to increase their contribution to 10% per year at the age of 32, they would have closer to &pound;550,000 in their pension at the age of 68. This either gives them a larger pension when they reach state pension age or the option to retire a bit earlier.&rdquo;</p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/two-thirds-expect-to-rely-on-the-state-pension-in-retirement-27054.htm</link>
<pubDate>Wed, 12 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>First Actuarial Appoints Four New Partners</title>
		<description><![CDATA[<div><strong>David Joy, Managing Partner at First Actuarial, a Gallagher Company, says:</strong> &ldquo;Our four new partners embody what makes First Actuarial special &ndash; the client-first approach that drives our growth. We&rsquo;re more than happy to recognise their efforts. We&rsquo;re dependent more than ever on exceptional professionals who bring skills, achievement and a positive mindset to our business.&rdquo;</div>

<div> </div>

<div>Marcos Abreu, Andrew Allsopp, Carl Fletcher and Scott Harrison have all progressed through associate partnership, an organisational layer created in 2024 to recognise exceptional talent and foster retention.</div>

<div> </div>

<div><strong>Andrew Allsopp</strong></div>

<div>Andrew Allsopp joined First Actuarial two years ago and has channelled his entrepreneurial strengths into establishing the firm&rsquo;s flourishing Birmingham office. He was previously an owner of Quattro, a Midlands-based pensions consultancy, which was acquired by Broadstone.</div>

<div> </div>

<div><strong>Andrew says: </strong>&ldquo;Building the Birmingham base of First Actuarial has been a rewarding challenge. We&rsquo;re attracting more and more professionals to deliver what local clients want &ndash; caring services from people who understand the setting in which they work. Our headcount is increasing steadily as we grow our West Midlands client base.&rdquo;</div>

<div> </div>

<div><strong>Marcos Abreu</strong></div>

<div>Marcos Abreu joined First Actuarial in 2019, and is central to the management and growth of the firm&rsquo;s Tonbridge office. With 12 Scheme Actuary appointments, Marcos also plays an active role in the wider business. Alongside his Scheme Actuary responsibilities and the demands of a young family, he leads the London team and contributes to a range of firm-wide and industry initiatives.</div>

<div> </div>

<div><strong>Marcos says:</strong> &ldquo;My career has thrived here because I&rsquo;ve been given the freedom to make a real difference to the company&rsquo;s success. I work closely with other people, and I set great store on giving tangible opportunities to colleagues and supporting future leaders in Tonbridge. I&rsquo;ve always felt well supported by the partners in Tonbridge. The firm trusts me to get things done, while offering a sounding board when I need it.&rdquo;</div>

<div> </div>

<div><strong>Carl Fletcher</strong></div>

<div>Carl Fletcher is an actuary with an entrepreneurial spirit and a wide range of responsibilities. Along with Scheme Actuary appointments, Carl is Head of Benefit Corrections and Data Audit Services and is also responsible for employee share scheme valuations.</div>

<div> </div>

<div><strong>Carl says: </strong>&ldquo;First Actuarial has given me the ideal environment for finding business opportunities and developing them. It&rsquo;s a great place to work and what we do is interesting. The firm has given me the freedom to develop new areas and they&rsquo;ve recognised my achievements.&rdquo;</div>

<div> </div>

<div><strong>Scott Harrison</strong></div>

<div>Scott Harrison is an actuary who has spent 17 years working for First Actuarial. Hard-working and reliable, he prides himself on getting things done, finding problems and correcting them proactively.</div>

<div> </div>

<div><strong>Scott says:</strong> &ldquo;Achieving partnership gave me a real sense of satisfaction and achievement. I've seen First Actuarial grow as a company since my summer internship in 2007 to what it is now, and I work with people I've known and respected for a long time. Associate partnership was an invaluable opportunity, giving me more influence when helping to develop colleagues in a positive way to improve the firm.&rdquo;</div>

<div> </div>

<div><strong>David Joy concludes: </strong>&ldquo;All four new partners demonstrate entrepreneurial flair, able to win new business, drive efficiency and bring their colleagues along. I&rsquo;m delighted to be in business with them. As we become an increasingly integrated part of Gallagher, we see these appointments further strengthening our leadership team and enhancing the service we provide to clients.&rdquo;</div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/first-actuarial-appoints-four-new-partners-27047.htm</link>
<pubDate>Tue, 11 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Pic Complete Buyin With Royal Society Of Chemistry Pension</title>
		<description><![CDATA[<div>The Royal Society of Chemistry works at the heart of the chemical sciences community, connecting people and ideas through partnerships, conferences, events and networks, publishing discoveries and insights from a truly global research community. It campaigns to protect our natural environment and tackle discrimination, aiming to build a truly inclusive world and helps create a future that is more open, more green and more equal.</div>

<div> </div>

<div><strong>Andy Pateman, Chair of Trustees for The Royal Society of Chemistry Pension Scheme, said:</strong> &ldquo;We are delighted to have reached this important milestone, securing our members&rsquo; benefits for the long term. Right from our first conversations with PIC, we have been impressed by their approach to customer service &ndash; they have shown they are the right partner to support our ambitions in de-risking the Scheme. I want to thank my co-Trustees (especially our</div>

<div>Professional Trustee Alison Bostock from Zedra), our many advisors and the PIC team for their focus, dedication and communication, helping us reach this stage so efficiently. It has been a pleasure working with such a professional group of people.&rdquo;</div>

<div> </div>

<div><strong>Jake Stanbridge, Origination Actuary at PIC, said: </strong>&ldquo;PIC&rsquo;s customer service capability and proven expertise in supporting schemes through complex de-risking journeys were key to securing this transaction. The Trustee was impressed by our ability to deliver first-class service from the outset, while providing the experience and certainty needed to help de-risk the Scheme.&rdquo;</div>

<div> </div>

<div><strong>Jamie Naik, Principal at LCP, said:</strong> &ldquo;This transaction demonstrates the benefits of a well-prepared scheme and a strong, collaborative relationship between the Trustees and sponsor with a real focus on member outcomes. That shared focus and alignment helped achieve a strong outcome for both parties, while further improving the security of members&rsquo; benefits.&rdquo;</div>

<div> </div>

<div>PIC were advised by CMS (Cameron McKenna Nabarro Olswang). LCP were the lead transaction advisers to the Trustees, with Addleshaw Goddard and Osborne Clarke providing legal advice, and Mercer providing actuarial and investment advice.</div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/pic-complete-buyin-with-royal-society-of-chemistry-pension-27046.htm</link>
<pubDate>Tue, 11 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Benign H1 Of 2026 Masks Rising Natural Catastrophe Risk</title>
		<description><![CDATA[<p>The first half of 2026 saw estimated insured natural catastrophe losses of USD 42 billion, 16% below the 10-year average. Insured losses from severe convective storms were also below trend, with the biggest outbreaks largely sparing the most exposed regions in the US. At the same time, June's record heat and persistent dry conditions set the stage for an active wildfire season in Europe and other parts of the world.</p>

<p><strong>Balz Grollimund, Head Catastrophe Perils at Swiss Re, said: </strong>&quot;A less costly first half of the year does not mean the risk has gone away. One major hurricane, earthquake or wildfire can quickly change the picture. Europe's recent wildfires highlight how hotter and drier conditions are making large wildfires more likely and, with more homes, businesses and infrastructure built in risk-exposed areas, also more costly.&quot;</p>

<p>As the world's fastest-warming continent, Europe now experiences 64% more hot days, defined as days when the daily maximum temperature reaches 30&deg;C or more, than in the 1950s. June's record heat in western Europe, together with persistent dry conditions, also created an environment more conducive to wildfires across western and southern Europe, where major fires affected France and Spain in July.</p>

<p>Wildfire risk has so far accounted for only a relatively small share of insured losses in Europe. Yet it is the fastest-growing weather peril globally. Insured wildfire losses in Europe have increased by an estimated 8&ndash;11% per year in real terms since 1970, Swiss Re Institute's research shows.</p>

<p>The early start to Europe's wildfire season illustrates how hazards are changing. Fire seasons are becoming longer, while conditions conducive to wildfires are becoming more frequent and affecting regions historically less exposed.</p>

<div><strong>Above-average storm activity, below-trend losses</strong></div>

<div>Although severe convective storm activity across the US remained above average, relatively few of the highest-impact events affected Texas, the Southern Plains and the Southeast, where the combination of frequent storms and high concentrations of insured assets typically generates the largest insured losses. This illustrates how insured losses depend not only on the severity of events, but also on where they strike.</div>

<p>Insurance covered around 42% of first-half economic losses, above the 30-year average of 33%, reflecting the concentration of damage in highly insured markets and across widely covered perils. By contrast, the earthquake sequence in Venezuela caused an estimated USD 20 billion in economic losses. Although no reliable insured-loss estimate is yet available, low insurance penetration suggests that only a small share of the damage is expected to be insured.</p>

<div><strong>A quieter first half does not necessarily mean a quieter year</strong></div>

<div>Historically, the second half of the year accounts for an average of 58% of global insured natural catastrophe losses, mainly driven by North Atlantic hurricanes. While El Ni&ntilde;o tends to suppress Atlantic hurricane activity, it does not eliminate landfall risk: 22% of US hurricane landfalls since 1950 occurred during El Ni&ntilde;o conditions. Atlantic hurricanes, however, are only one component of second-half catastrophe risk. El Ni&ntilde;o may influence tropical cyclone activity in the Central and East Pacific and could alter the risk of floods, wildfires, and other weather extremes elsewhere.</div>

<p>Beyond seasonal outlooks, the long-term drivers of catastrophe losses remain unchanged, including growing exposure in hazard-prone areas and rising reconstruction costs. Strengthening resilience and reducing underlying risk will therefore be increasingly important in maintaining the affordability and availability of insurance.</p>

<div><strong>Total economic and insured losses in H1 2026 and H1 2025</strong></div>

<div><span style="font-size:12px"><em>(USD billion in 2026 prices)</em></span></div>

<p><img alt="" src="https://www.actuarialpost.co.uk/images/pic_SwissReHazards1108261.jpg" style="height:163px; width:589px" /></p>

<div><span style="font-size:11px"><em>* Note: H1 10-year average refers to the average first-half losses between 2016 and 2025.</em></span></div>

<div><span style="font-size:11px"><em>Source: Swiss Re Institute</em></span></div>

<p> </p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/benign-h1-of-2026-masks-rising-natural-catastrophe-risk-27044.htm</link>
<pubDate>Tue, 11 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>2015  The Growing Challenge Of Heat In Europe  039 s Cities</title>
		<description><![CDATA[<div><strong>By Lara Schmid, Catastrophe Research Analyst and Daniel Bannister, Weather & Climate Risks Research Lead, WTW </strong></div>

<div> </div>

<div>Unlike floods or storms, extreme heat leaves little visible damage behind. There are no collapsed bridges or destroyed buildings to assess, and few physical loss indicators that align with the way catastrophe risk has traditionally been measured. This has made heat far harder to represent within conventional approaches to risk modelling, despite it being Europe&rsquo;s deadliest weather-related hazard. The heatwave highlighted how rising temperatures, dense development and growing populations were pushing cities to the centre of Europe's future climate risk, requiring new approaches to designing and financing urban resilience.</div>

<div> </div>

<div><strong>Designing cooler cities</strong></div>

<div>The years since 2015 have only reinforced the trend. Europe has repeatedly experienced record-breaking heat, including the UK's first recorded temperature above 40&deg;C in 2022, an estimated 67,873 heat-related deaths across Europe that same year, and a further estimated 50,798 deaths in 2023. This summer, another omega block again settled over Europe, bringing record June temperatures to both France and the UK.</div>

<div> </div>

<div>Recent years have also seen increasing attention given to nature-based solutions as a practical way of reducing urban temperatures. International agreements such as the Sendai Framework for Disaster Risk Reduction and the Paris Agreement gave greater prominence to ecosystem-based adaptation, while European programmes including GrowGreen and Connecting Nature demonstrated how trees, parks, green roofs and other green infrastructure could provide measurable cooling benefits.</div>

<div> </div>

<div>Today, urban cooling is becoming an increasingly common feature of resilience planning. The UK's Climate Change Committee has recommended introducing a statutory duty requiring local authorities to address overheating risks, from cooling public buildings to incorporating heat resilience into new developments. The question for insurers, property owners and city authorities is no longer whether to build for heat, but how. A recent WRN analysis, City heat -</div>

<div> </div>

<div><strong>A role for nature, presents solutions.</strong></div>

<div>The reason is straightforward: green infrastructure reduces temperatures before an extreme event occurs. Trees provide shade, vegetation cools the surrounding air through evapotranspiration and green roofs reduce heat absorbed by buildings. Reviews have shown neighbourhood-scale cooling from a range of nature-based solutions, while UK studies have found green fa&ccedil;ades can reduce neighbourhood temperatures by as much as 5.0&deg;C.</div>

<div> </div>

<div>Cooler cities carry benefits that extend well beyond temperature reduction alone. They ease pressure on healthcare systems, cut energy demand, boost workforce productivity and protect infrastructure during prolonged heatwaves. The healthcare impact alone is significant, with NHS England estimating that heat-related mortality already costs around &pound;6.8 billion annually, rising to &pound;14.7 billion per year by the 2050s. As a result, urban greening is increasingly becoming part of conversations around resilience, asset management and long-term risk.</div>

<div> </div>

<div>Through its participation in the EU-funded NATURANCE programme, the Willis Research Network explored how innovative financing could complement physical adaptation. Rather than replacing existing emergency planning, the programme examined how predefined heat thresholds could automatically release funding when dangerous conditions developed. This would allow support to reach people faster, instead of waiting on funding decisions once a heatwave is already underway. </div>

<div> </div>

<div>A worked example for Central East London showed how a parametric structure, using wet-bulb temperature data tiered to the UK's five-level heat-health alert system, could plug into the city's existing emergency protocol individuals experiencing homelessness. The protocol already had funding; what it lacked was a mechanism to release it when needed most. Trigger-based financing applied to existing funds, rather than insurance as a standalone product, emerged as the more viable path forward.</div>

<div> </div>

<div><strong>Better together</strong></div>

<div>Through its participation in the EU-funded NATURANCE programme, the Willis Research Network explored how innovative financing could complement physical adaptation. Building resilience to heat therefore requires both approaches. Designing cooler cities reduces the risk before an event develops, while financing mechanisms improve the ability to respond when thresholds are exceeded.</div>

<div> </div>

<div>More broadly, the experiences of European cities during the summer of 2026 demonstrate that heat is increasingly acting as a multiplier of risk. Across Europe, prolonged periods of extreme temperature have contributed to health impacts, strained infrastructure and created conditions for significant wildfires, demonstrating how a single hazard can cascade across interconnected systems. As Europe continues to warm faster than any other continent, the resilience of its cities will increasingly be defined not only by their ability to withstand extreme heat, but by their capacity to anticipate, manage and adapt to the wider risks it creates.</div>

<div> </div>

<div><strong>Key takeaways</strong></div>

<div><em>Heat is one of Europe's most serious and fastest-growing risks, hitting exposed, growing urban populations hardest.</em></div>

<div><em>Nature-based solutions are a proven way to reduce that exposure, and the funding for them often already exists. It just needs a clear mechanism to put it to use.</em></div>

<div><em>Parametric cover and nature-based solutions work best in pairs with one building resilience and the other providing support when resilience is stretched to its limits.</em></div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/2015--the-growing-challenge-of-heat-in-europe--039-s-cities-27050.htm</link>
<pubDate>Tue, 11 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Women Continue To Lag Behind Men In Workplace Pension Saving</title>
		<description><![CDATA[<p>Analysis of the latest DWP annual research on trends in workplace pension participation by Broadstone, reveals that women continue to lag behind men in workplace pension saving, despite some progress in narrowing the gender pension contribution gap.</p>

<p>Across all employees, the median male saver contributed &pound;4,430 to their workplace pension in 2025, &pound;310 more than the &pound;4,120 saved by the median female employee.</p>

<p>Encouragingly, this contribution gap has halved in the last six years, from &pound;680 in 2019, when the median male saver contributed &pound;4,660 and the median female saver contributed &pound;3,980. However, whilst the gap has narrowed, progress has begun to slow in recent years, with the gap standing at &pound;360 in both 2023 and 2024 &ndash; just &pound;50 more than the latest gap.</p>

<p>The impact of lower pension contributions can extend well beyond working years. A &pound;310 annual difference in pension saving would amount to &pound;12,400 in missed contributions over a 40-year career. Assuming annual investment growth of 5%, the effect of lost compound growth means this could leave someone with around &pound;37,500 less in retirement savings.</p>

<p><strong>Kelly Parsons, Head of DC Proposition at Broadstone, said:</strong> &ldquo;While it is encouraging to see the gap between male and female pension contributions gradually narrowing, women are still saving significantly less into their workplace pensions, leaving many at greater risk of poorer retirement outcomes.</p>

<p>&quot;This isn't just a question of engagement. Women are more likely to take career breaks to care for children or family members, work part time, or reduce their hours during different stages of their careers. These interruptions can have a lasting impact on pension contributions and limit the additional savings accrued by long-term investment return growth.&rdquo;</p>

<p><img alt="" src="https://www.actuarialpost.co.uk/images/pic_BroadstoneKelly1108261.jpg" style="height:143px; width:600px" /></p>

<p>The median private sector female employee contributed &pound;2,800 to their workplace pension in 2025, almost a thousand pounds less - &pound;920 - than the &pound;3,530 contributed by the median private sector male employee. In the public sector, the savings gap was significantly larger at &pound;3,060, with the average female employee contributing &pound;8,370 in 2025, compared to the &pound;11,430 saved by the average male employee.</p>

<p>Female employees remain less likely to opt out of workplace pension saving than men. In the latest quarter (Q3 2025/26), 10.3% of auto-enrolment (AE) eligible female employees opted out of their workplace pension scheme, compared with 13.3% of AE-eligible male employees. However, opt-out rates have risen for both groups over the past year, increasing from 8.6% to 10.3% for women and from 11.5% to 13.3% for men (Q3 2024/25).</p>

<p><strong>Kelly Parsons added: </strong>&quot;Employers are in a strong position to help close this gap. Clear, targeted communications around the value of pension saving, encouraging both private and public sector employees to review and increase contributions following pay rises or after returning from parental leave, and providing access to financial education can all make a meaningful difference.</p>

<p>&quot;Creating a workplace culture where pensions are discussed more openly and employees are supported to make informed decisions won't eliminate the structural challenges overnight, but it can help more women stay on track for a better retirement.&rdquo;</p>

<p> </p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/women-continue-to-lag-behind-men-in-workplace-pension-saving-27042.htm</link>
<pubDate>Tue, 11 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Expert Backed Ai Earns Pension Savers Trust</title>
		<description><![CDATA[<p>Artificial intelligence (AI) is transforming the way people access financial support, according to data from Scottish Widows&rsquo; latest Retirement Report. </p>

<p>With over 26 million UK adults* lacking confidence when managing their savings for retirement, more are now turning to AI to better understand their pension savings.</p>

<p>Over two in five (42%) people are comfortable using AI to explain pension jargon, 37% would be open to calculating how much they need for retirement with AI and more than one in four (28%) to work out how much they need to save each month.</p>

<div><strong>Growing trust in regulated AI tools </strong></div>

<div>Trust is a huge factor when using AI for money decisions. Crucially, FCA-regulated AI tools come with formal consumer protections, which provide a safety net if things don&rsquo;t go as planned. Unregulated or general-purpose AI tools don&rsquo;t offer this protection &ndash; if they give inaccurate or unsuitable advice that leads to financial loss, people may be left without any support.  </div>

<p>Almost a third (30%) of people currently trust AI tools to give them guidance about their pension. Of these, 80% say their most trusted source is either their pension provider, or firms that already provide financial guidance or advice. Meanwhile, one in five (20%) say they would trust technology firms that don&rsquo;t specialise in money more than any other provider, highlighting the need for further education on how consumer protections differ. </p>

<div><strong>The human touch still matters for big decisions</strong></div>

<div>The findings also reveal that while AI is a useful tool for demystifying financial products and helping people make decisions about their retirement options, there&rsquo;s still a strong desire to speak to a financial professional for more complex decisions when the stakes are higher.</div>

<p>For example, just one in 10 (10%) retirees would be comfortable with AI suggesting the best way to withdraw from their pension. Among those aged 50 and over, just 5% plan to rely on AI tools before taking money from their pot.</p>

<p>Almost half (48%) of people are worried that AI may give wrong or unsuitable pension advice, 43% worry about the safety of their data and two in five (38%) don&rsquo;t think it would take their personal circumstances into account. </p>

<p>But AI has a valuable role to play in helping people take their first step towards financial advice, with nearly a third (31%) saying they would take AI-generated insights to a professional financial adviser and a quarter (24%) using AI information to have more informed conversations with their pension provider.</p>

<p><strong>Maria Herrero-Bullich, Scottish Widows&rsquo; Chief Customer & Digital Officer, said:</strong> &ldquo;AI has the power to simplify complicated financial topics, personalise guidance, and make everyday decisions around pensions, savings and investments much easier to manage. As it becomes a normal part of managing our money, trust is essential. It&rsquo;s clear that for those bigger, more complex moments people still value speaking to a financial expert, so the human factor and AI can comfortably co-exist to provide people with the confidence to make more informed decisions about their future.</p>

<p>&ldquo;One thing that&rsquo;s important to understand is the difference between support from regulated firms and general-purpose AI tools, with the former carrying much greater protection for the consumer.</p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/expert-backed-ai-earns-pension-savers-trust-27043.htm</link>
<pubDate>Tue, 11 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Ppf Publish Latest Ppf7800 Index Figures For July 2026</title>
		<description><![CDATA[<p>A scheme&rsquo;s s179 liabilities represent, broadly speaking, the premium that would have to be paid to an insurance company to take on the payment of PPF levels of compensation. This compensation may be lower than full scheme benefits.  </p>

<p><strong>Highlights  </strong></p>

<p><img alt="" src="https://www.actuarialpost.co.uk/images/pic_PPF7800Aug261108261.jpg" style="height:210px; width:600px" /></p>

<p><strong>Aaron Pang, PPF Acting Chief Actuary, said: </strong>&quot;While equity markets performed positively during July, gilt yields matched global markets in rising through the month as a resumption of hostilities in the Middle East increased concerns about an inflation shock. Falling bond prices, which drove gilt yields higher, led to a reduction in both asset and liability values across the PPF eligible universe, reflecting DB schemes' significant allocation to bonds.</p>

<p> </p>

<p>Overall, across the eligible universe, funding levels improved as the 3.1% fall in liability values was greater than the 1.7% drop in assets. This resulted in a stronger aggregate surplus of &pound;271.3bn and a funding ratio of 133% - the highest recorded since July 2023.&quot;</p>

<div><strong>A note on changes to the PPF 7800 Index</strong></div>

<div>In our December 2025 update, we highlighted that the government had announced that it would legislate to allow us to pay prospective indexation starting from 2027 for service accrued pre-1997 for members of schemes who provided this as a right. As well as schemes that have already transferred to the PPF, this will also impact the s179 liabilities of schemes in the PPF universe. In April the Pension Schemes Act received Royal Assent. As we&rsquo;ve signposted, we&rsquo;ll reflect the impact from these changes in the PPF 7800 Index in due course.</div>

<p>View the August update and see the supporting data on the 7800 Index for 31 July 2026 here: <a href="https://www.ppf.co.uk/ppf-7800-index">The PPF 7800 index | Pension Protection Fund.</a></p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/ppf-publish-latest-ppf7800-index-figures-for-july-2026-27045.htm</link>
<pubDate>Tue, 11 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Industry Comments On Latest Ppf7800 Index For July 2026</title>
		<description><![CDATA[<div><strong>Sarah Elwine, Actuarial Director at Broadstone, commented:</strong>&ldquo;Pension schemes continue to enjoy historically healthy funding levels as strong equity market performance drove further improvements in funding ratios. As we head deeper into the second half of the year, trustees will be evaluating how the conflict in the Middle East continues to impact expectations over the future trajectory interest rates. While competition remains intense in the de-risking market, many schemes may look to capitalise on the strength of their funding levels to secure an insurance solution that protects members benefits. However, there is continued endgame optionality for trustees, especially in regard to how they utilise surpluses, which may encourage some schemes to run-on.&rdquo;</div>

<div> </div>

<div>
<p><strong>Vishal Makkar, Managing Director, UK Wealth Consulting at Gallagher comments: </strong>&ldquo;The UK&rsquo;s DB schemes have stood their ground and retained a strong funding position, with the aggregate surplus rising to &pound;7.3bn. These figures reflect a healthy funding environment and an increasingly competitive risk transfer market. The PPF&rsquo;s current consultation on Section 179 assumptions provides further evidence of how market conditions have evolved. Following a review which found that bulk annuity pricing has become more competitive, the PPF is proposing updates to its discount rate and longevity assumptions to bring valuations more closely into line with current buyout pricing. As schemes move into stronger funding positions, the debate is increasingly shifting towards what role DB schemes can play beyond simply securing member benefits. With the Department for Work and Pensions&rsquo; consultation on surplus rules closing on 2 September, trustees and sponsors are considering how greater flexibility around surplus could influence their long-term investment strategy. Some schemes may decide to invest into UK business projects and the wider domestic economy, particularly in instances when such investments align with their fiduciary duties and members&rsquo; interests. Although a buy-out will remain a desirable outcome for some schemes, it is not the only option. Schemes with strong governance and sponsor support may consider running on and retaining a greater flexibility on where and how they choose to invest. In any event, trustees must ensure decisions are evidence-led and focused on delivering the best outcomes for members.&rdquo;</p>

<p><a href="https://www.actuarialpost.co.uk/article/ppf-publish-latest-ppf7800-index-figures-for-july-2026-27045.htm"><strong>PPF 7800 Index Figures for July 2026</strong></a></p>
</div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/industry-comments-on-latest-ppf7800-index-for-july-2026-27048.htm</link>
<pubDate>Tue, 11 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>15 Of The Most Common Sipp Questions Answered</title>
		<description><![CDATA[<div><strong>Sarah Coles, head of personal finance at AJ Bell, comments: </strong>&ldquo;Since their launch in 1990, self-invested personal pensions have changed significantly. Nowadays they appeal to huge numbers of people looking for the flexibility they need to take control of their pension. However, there are still millions of people who have yet to get to grips with what they have to offer, so it&rsquo;s worth exploring the most common questions and answers.&rdquo;</div>

<div> </div>

<div><strong>What is a SIPP?</strong></div>

<div>&ldquo;It stands for self-invested personal pension, and is a type of personal pension. You pay into the scheme, the government adds tax relief, and then the money is invested to create a pot in retirement. However, SIPPs offer a much bigger range of investment options than other personal pensions. Providers differ, but you may be able to invest in thousands of funds, investment trusts, shares, exchange traded funds, bonds and gilts.&rdquo;</div>

<div> </div>

<div><strong>How much does a SIPP cost?</strong></div>

<div>&ldquo;There are a few charges to be aware of when opening and building up your portfolio within a SIPP. There&rsquo;s an overall platform charge, which can be a flat fee or can be based on a percentage of the value of your pension. Some providers vary the percentage fee depending on the size of your pension &ndash; so for larger portfolios, a smaller percentage is taken. There may also be a cap on these charges &ndash; depending on the assets you hold.</div>

<div> </div>

<div>&ldquo;You&rsquo;ll also pay the charges of any funds you hold inside the pension. These vary significantly, with lower charges for things like index funds and higher charges for actively managed funds. If you hold shares, investment trusts or ETFs, you&rsquo;re not charged a fund fee. On top of that, there will be trading costs whenever you buy or sell shares or funds. However, if you are investing regularly into selected investments, there may be no trading charge for that and it will differ between providers.&rdquo;</div>

<div> </div>

<div><strong>What is the SIPP allowance?</strong></div>

<div>&ldquo;The annual allowance is how much you can pay into your pension tax-efficiently and the rules are the same as any other kind of pension. For most people, your annual allowance matches your total pay for that year &ndash; including salary but also bonuses, commission and overtime. If you make over &pound;60,000, your annual allowance is capped at &pound;60,000. Everything contributed to your pension counts towards this &ndash; whether it&rsquo;s you, your employer, or someone else. &ldquo;There are some exceptions to this. If you&rsquo;re not earning at all, you&rsquo;re given a &pound;3,600 allowance each year.&rdquo;</div>

<div> </div>

<div><strong>What is carry forward on the annual allowance? </strong></div>

<div>&ldquo;Carry forward allows you to use unused allowances from the previous three years &ndash; if you didn&rsquo;t use your full allowance for that year. However, in the year you&rsquo;re using carry forward, you still can&rsquo;t pay in more than that year&rsquo;s earnings. So, for example, if you have &pound;50,000 of unused allowances from the past three years, and you earned &pound;80,000 this year, you could carry forward &pound;20,000 and pay in a total of &pound;80,000. Bear in mind that you will need to have been a member of a pension scheme during the years that you&rsquo;re carrying forward.&rdquo;</div>

<div> </div>

<div><strong>What is SIPP drawdown?</strong></div>

<div>&ldquo;This is one way to take money from your pension after the age of 55. When you move into drawdown within your SIPP, you take 25% of the money as a tax-free lump sum, and the rest of it remains invested. You can then draw an income directly from it.</div>

<div> </div>

<div>&ldquo;You can move it all into drawdown at the same time and take the full 25%. Alternatively, you can do it in chunks, and take 25% of each chunk as you go. This can be sensible if you don&rsquo;t need all the tax-free cash immediately.</div>

<div> </div>

<div>&ldquo;Drawdown has the advantage that your money stays invested, so it can continue to grow. You also have real flexibility over how much you can draw from the pot, and when, so you only take what you need and retain the flexibility to take one off lump sums. However, you need to manage how you draw this income, so it lasts as long as you need it to. You may also want to manage how much income you take to stay within certain tax thresholds.</div>

<div> </div>

<div>&ldquo;The benefits and potential risks are one reason why some people will mix and match drawdown and annuities at various stages of retirement, using different chunks of their pension pot to fund different things.&rdquo;</div>

<div> </div>

<div><strong>What are the SIPP withdrawal rules?</strong></div>

<div>&ldquo;There are a few questions people tend to ask about withdrawal rules, such as &lsquo;how much can I withdraw from a SIPP tax free?&rsquo; The answer is the same for the vast majority of all pensions &ndash; up to 25% of the total pot.</div>

<div> </div>

<div>&ldquo;They might also ask, &lsquo;can I withdraw cash from my SIPP at any time?&rsquo; The answer is that you can, as soon as you have reached the minimum pension age. This is 55 at the moment, rising to 57 in 2028. After that it will stay 10 years below the state pension age, so whenever the state pension age rises, the minimum pension age will too.</div>

<div> </div>

<div>&ldquo;More generally they may ask about how they can withdraw money from their pension. This is the same as most personal pensions. Once you&rsquo;ve taken your tax-free lump sum, you can buy an annuity or you can move into drawdown. Alternatively, you can take pension lump sums &ndash; of which 75% is taxable and 25% is tax free. (The official name for these is uncrystallised funds pension lump sums, or UFPLS.) You can take a single lump sum or a series of them, and leave the rest invested for potential growth, or you could take the whole pot &ndash; although you need to consider the tax implications.</div>

<div> </div>

<div>&ldquo;The other rule to get to grips with is that as with any other defined contribution pension, when you take drawdown income or a pension lump sum, you&rsquo;ll trigger the Money Purchase Annual Allowance (also known as the MPAA). This reduces your annual allowance for contributions to &pound;10,000 a year. The idea is to stop you from withdrawing pension money and ploughing it straight into another pension, to benefit from another round of tax relief. There are some exceptions to this rule &ndash; so it&rsquo;s worth checking before you start drawing money from any pension.&rdquo;</div>

<div> </div>

<div><strong>Can I transfer my pensions to a SIPP? </strong></div>

<div>&ldquo;Yes, you can transfer most types of pensions into a SIPP, including workplace pensions. However, before you do, you need to consider a few things.</div>

<div> </div>

<div>&ldquo;Check whether there are any valuable benefits attached to your old pension. If it&rsquo;s a defined benefit pension, it&rsquo;s usually not a good idea to transfer and if it&rsquo;s a defined contribution pension with a guaranteed annuity rate, you may also want to stay put. Check for exit charges too, especially on older pensions.</div>

<div> </div>

<div>&ldquo;Have a look at the investments held in your other pensions too, and whether they can be held by your chosen SIPP provider. You can check in with the SIPP company first. If they can&rsquo;t hold the same investments, it&rsquo;s not a deal-breaker: you can sell up and transfer as cash, but be aware you&rsquo;ll be out of the market while the transfer takes place, so won&rsquo;t benefit from any growth during that time.&rdquo;</div>

<div> </div>

<div><strong>Can I have a SIPP and a workplace pension?</strong></div>

<div>&ldquo;Yes. You can hold and pay into multiple pensions at the same time, as long as you don&rsquo;t go over your annual allowance. Before you do this, check if you can get more from your employer buy paying extra into your workplace pension. If they match additional contributions, it can be a very sensible option. Then once you&rsquo;ve exhausted all they&rsquo;re prepared to match, you can pay into your SIPP. Workplace pensions may have a very restricted range of investments, so having a separate SIPP gives you much more flexibility.&rdquo;</div>

<div> </div>

<div><strong>Can my employer contribute to my SIPP?</strong></div>

<div>&ldquo;Yes, it is just a question of whether they&rsquo;re prepared to. When you&rsquo;re automatically enrolled into a pension at work, they&rsquo;ll have chosen a pension for all payments to go into. If you just opt out and pay into a SIPP instead, you&rsquo;ll lose valuable employer contributions, so it&rsquo;s worth asking if they&rsquo;ll pay into the SIPP rather than the workplace pension pot. If they will, you&rsquo;ll still need to opt out, but this way the employer contributions will go into your SIPP. The auto-enrolment rules mean that after three years you&rsquo;ll automatically switch back into the employer&rsquo;s main scheme, so you&rsquo;ll need to go through the same process again.</div>

<div> </div>

<div>&ldquo;People also ask, &lsquo;how can I get my employer to make contributions to my SIPP?&rsquo; They can use a bank transfer or direct debit, or they can pay a lump sum or make regular contributions. For regular contributions they need to complete an employer monthly contribution form. If they&rsquo;re paying a lump sum, you can make a single payment request, the provider will do some checks on your employer, and then give you payment details to give to your employer, so they can pay in.&rdquo;</div>

<div> </div>

<div><strong>SIPP vs ISA &ndash; which is right for me?</strong></div>

<div>&ldquo;They both have advantages, so it&rsquo;s a case of getting to grips with what each has to offer as well as which account aligns with your investment goals. In many cases, paying into both accounts will be a good option.</div>

<div> </div>

<div>&ldquo;SIPPs offer income tax relief on the way in, so you get a 20% top-up from the government paid directly to your SIPP. If you&rsquo;re a higher rate or additional rate tax payer, you can claim a further 20% or 25% via your tax return. Your investments then grow free of tax, and when you withdraw, you can take 25% of the pot tax-free. The tax relief is why pensions may often be a sensible first port of call for retirement savings, especially if you&rsquo;re keen to manage your income tax bill.</div>

<div> </div>

<div>&ldquo;ISAs don&rsquo;t have tax relief on the way in, but growth is tax free and there&rsquo;s no tax to pay on withdrawals. The other big advantage of the ISA is flexibility. The Lifetime ISA has more restrictions, but with any other kind of ISA you can make withdrawals at any time, whereas in a SIPP you can&rsquo;t access the money until you&rsquo;re 55 (which is rising to 57 in 2028). It&rsquo;s why people will often hold ISAs alongside their SIPP, to give them flexibility to withdraw cash before they reach retirement age and tax-free withdrawals throughout retirement.&rdquo;</div>

<div> </div>

<div><strong>How do I open a SIPP?</strong></div>

<div>&ldquo;You can apply online with just your National Insurance number, debit card details and information about any pensions you want to transfer in. If your employer is going to pay in, you may need their details to hand too. Once you&rsquo;ve filled out the form, you can pay in a lump sum with your debit card and make regular monthly contributions. Before you do this, you should get to grips with how SIPPs work, including the terms and conditions and the charges. You can do this without help, but if you&rsquo;re unsure and need support, a financial adviser can help you understand if it&rsquo;s right for you.&rdquo;</div>

<div> </div>

<div><strong>What should I invest in within a SIPP?</strong></div>

<div>&ldquo;You&rsquo;ll usually have a huge array of investment options within a SIPP. It will depend on your provider, but you should be able to choose from thousands of funds, investment trusts, UK and overseas shares, exchange traded funds, bonds and gilts. If you&rsquo;re unsure where to start, check if your provider has an option for people in your position, such as a &lsquo;ready-made&rsquo; pension. They may have a managed fund that&rsquo;s designed to be the core of a pension portfolio. You can then build on it with investments tailored to your needs.&rdquo;</div>

<div> </div>

<div><strong>What happens to my SIPP when I die? </strong></div>

<div>&ldquo;You can leave your SIPP to anyone you choose &ndash; or a number of people, split in any way you like, by filling in a &lsquo;nomination of beneficiaries&rsquo; form. If you have nominated a spouse, civil partner or any children under the age of 23 (or anyone financially dependent on you &ndash; including older children with disabilities), they will usually be able to choose whether to take it as a lump sum or leave it in the pension.</div>

<div> </div>

<div>&ldquo;The pension provider has discretion over whether to follow the instructions on the form. It&rsquo;s very rare that they won&rsquo;t, but if, for example, you haven&rsquo;t updated the form since you divorced and remarried, they may be prepared to pay out to the new spouse.</div>

<div> </div>

<div>&ldquo;If you&rsquo;re under the age of 75 when you die, the payments are tax-free. If you are over the age of 75, they will usually pay income tax when they withdraw it. Until April 2027, all pensions are free of inheritance tax. After that, they will be brought into the IHT net &ndash; although most people will still not have a large enough estate to have to worry about inheritance tax.&rdquo;</div>

<div> </div>

<div><strong>What is a Junior SIPP and how does it work?</strong></div>

<div>&ldquo;These are pensions for children under the age of 18, which are opened and managed on behalf of the child. Like an adult SIPP, they can invest in a huge range of options, including thousands of funds, shares, trusts, ETFs, bonds and gilts. They grow free of tax, and they also get tax relief on contributions. When they turn 18 it becomes an adult SIPP, so they are in the driving seat, although they can&rsquo;t access the money until the minimum pension age (currently 55, but set to rise to 57 in 2028 and keep rising in step with the state pension age beyond that).</div>

<div> </div>

<div>&ldquo;People frequently ask &lsquo;what is the Junior SIPP allowance?&rsquo; The answer is that you can pay in up to &pound;2,880 a year. They also ask &lsquo;Does the government top up a Junior SIPP?&rsquo; The answer is yes, they top it up with tax relief at 20% &ndash; even though most children don&rsquo;t pay tax. It means up to &pound;3,600 can go into a Junior SIPP every year.&rdquo;</div>

<div> </div>

<div><strong>Who is eligible to open a Junior SIPP?</strong></div>

<div>&ldquo;A parent or legal guardian can open a Junior SIPP, although if they&rsquo;re over the age of 16, the child may need to sign a form. Anyone can pay into it, up to &pound;2,880 per year, although the person who opened it up will need to make the investment decisions.&rdquo;</div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/15-of-the-most-common-sipp-questions-answered-27049.htm</link>
<pubDate>Tue, 11 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Swiss Re Announce Two Senior Appointments In Life   Health</title>
		<description><![CDATA[<p>Swiss Re today announces the appointment of Damien Bartlett as Head of Market Unit Life & Health UK and Ireland and Middle East and Africa. The appointment will take effect 1 November 2026. Damien replaces Tamas Bown, who has taken on the role of Swiss Re's Head of Market Unit Asia Pacific ex China.</p>

<p>Swiss Re's Life & Health Re Business Unit also announces the appointment of Karen Tan as Chief Underwriting Officer for L&H Re, effective 1 October 2026. Karen will continue to be based in Singapore and will relocate to Zurich in due course.</p>

<p><strong>Damien Bartlett</strong> joins Swiss Re from SCOR, where he held a number of senior leadership roles, having started his career there in 2001. Most recently, he served as SCOR's Global Head In-Force Management, Head Strategy and COO for Life & Health. Prior to this, he was Regional CEO for EMEA & Canada and previously led SCOR's UK, Ireland, South Africa, Canada and Australia markets.</p>

<p><strong>Karen Tan</strong> is currently the Chief Risk Officer of L&H Re. Karen has served in several leadership roles at Swiss Re, including Head Life & Health Products Asia and Chief Risk Officer for Asia Pacific. She was previously Chief Actuary of Zurich Life Insurance Company in Switzerland, and led Zurich Insurance Group's Global Life Risk Analysis department. She is a Fellow of the UK Institute and Faculty of Actuaries.</p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/swiss-re-announce-two-senior-appointments-in-life---health-27041.htm</link>
<pubDate>Mon, 10 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>The Impact Of The Tech Correction On Em Allocation</title>
		<description><![CDATA[<p><strong>By Mark Martyrossian, Director at Aubrey Capital Management</strong></p>

<p>Clearly, if there is a reduction in the growth of AI capex committed, or if supply shortages of memory and all the other components of AI infrastructure are resolved sooner than expected, then a downturn in the cycle can be expected.</p>

<p>As to demand reflected by capex, the hyperscalers continue to ramp up spending with Jensen Huang, predicting that capex on AI infrastructure will be 4-5tn USD by 2030. The issue will be whether this type of investment is sustainable as financing shifts from existing cash-flow to debt funding. The Oracle downgrade is a red flag.</p>

<p>On the supply side the current consensus is that shortages will remain until at least 2H27, however, despite being denied the most advanced NVIDIA GPUs the Chinese pursuit of AI dominance could change the dynamic. The release of Moonshot&rsquo;s Kimi 3 agentic model last week may be another DeepSeek moment and casts doubt on whether paying top dollar for the most advanced chips is money well spent. Chinese chipmaking companies are also a major factor when considering the supply side. The IPOs for CXMT (+460% on its first day of trading) and YTMC are a reminder of this, however, one analyst revealed that Chinese capacity would have to quadruple in order to satisfy domestic demand alone. The impact of Chinese production must also be viewed against the dominance of Hynix and Samsung when it comes to the most sophisticated chips.</p>

<p>The conundrum remains whether the correction just experienced marks a floor after all the excitement of the last 2 years or whether there is more to come. We have trimmed our AI exposure but still retain a decent position as the US hyperscalers are more likely to increase capex in the coming quarter than reduce it (as shown by Alphabet&rsquo;s results this week). However, having a strong list of alternative options is important at this stage.</p>

<p>India, with its lack of exposure to the AI trade, has suffered from significant outflows from foreign institutional investors (FII) with 27bn USD of outflows as of middle of July and the lowest level of net FII buying since 2016. Clearly a fluctuating oil price may yet temper FII enthusiasm, however, it is reasonable to expect the rotation from India into the AI trade to reverse should AI start to show signs of fatigue. The first signs of this trend reversing have been visible with 1.8bn USD of net buying in the first fortnight of the month. Despite the lacklustre performance of the stock market of late, India is economically strong; growing GDP over 7% in each of the last two quarters and the stocks are significantly cheaper now than at the market&rsquo;s peak in Sep&rsquo;24. As you know, as stock pickers, we buy companies not markets and to this end we have added modestly to our Indian exposure albeit from low levels. Early days but on watch.</p>

<p> </p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/the-impact-of-the-tech-correction-on-em-allocation-27038.htm</link>
<pubDate>Mon, 10 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Implications For Canadian P c Insurers From Recent Wildfires</title>
		<description><![CDATA[<p><strong>Steve Liu, Assistant Vice President, Global Insurance & Pension Ratings</strong>, comments on the credit rating implications for Canadian P&C insurers from the current wildfires. &quot;The recent expansion of wildfire activity in British Columbia has increased the need for continued monitoring, given the province's history of generating some of Canada's largest insured wildfire losses. Nevertheless, we believe Canadian insurers remain well positioned to absorb wildfire-related losses under the current loss scenario, supported by strong earnings, robust capital buffers, and adequate reinsurance protection.&quot;</p>

<div><strong>Credit rating considerations include:</strong></div>

<div><em>There was one trend change to Negative from Stable for Sovereign credits with the rest being confirmations, while Sub-Sovereigns and Public Finance were all confirmations. </em></div>

<div><em>Financial Institutions credit rating actions were mostly confirmations, but one trend was changed to Negative from Stable.</em></div>

<div><em>Credit ratings for Diversified Industries; Energy, Utilities, and Natural Resources; and Asset Finance included one upgrade, one downgrade, and one trend change to Stable from Positive. Meanwhile, for private credit, adjusting to exclude upgrades from recent default cases, the ratio of downgrades to upgrades was at 2.9 times (x), down from 3.8x at YE2025.</em></div>

<p>This month's featured topics are related to Hungary's ability to deliver on its announced fiscal target, credit implications from growing opposition toward data center construction, and credit implications from the ongoing wildfires for Canadian property and casualty (P&C) insurance companies.</p>

<p><strong>Yesenn El-Radhi, Senior Vice President, Global Sovereign Ratings</strong>, comments on Hungary's ability to achieve its recently announced fiscal target. &quot;The new Hungarian government has set an ambitious fiscal target for 2030, but the announced consolidation measures are unlikely to be sufficient for reaching this goal. Durable fiscal consolidation will depend on politically challenging measures that broaden the tax base and restrain spending, with a primary balance improvement of 2.0% to 2.5% of GDP likely needed to stabilize public debt.&quot;</p>

<p><strong>Jason LaPorte, Vice President, Corporate Ratings, Asset Finance</strong>, comments on the credit implications related to growing opposition to data center construction. &quot;Impacts to data center credits have been limited so far, as rated debt in project finance has largely been late-stage construction or fully completed. However, if new construction were inhibited, this could increase the value of operating data centers and make debt refinancings easier.&quot;</p>

<p> </p>

<p>Catch up on these topics and more thought leadership from across the Fundamental Credit Ratings teams and around the globe in this month's edition.</p>

<p><a href="https://www.actuarialpost.co.uk/downloads/cat_1/Morningstar_DBRS-Consider_Credit--Fundamental_Ratings_Monthly_Briefing_August_2026.pdf"><strong>August 2026 edition of &quot;Consider Credit&mdash;Fundamental Ratings Monthly Briefing.&quot;</strong></a></p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/implications-for-canadian-p-c-insurers-from-recent-wildfires-27037.htm</link>
<pubDate>Mon, 10 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>The Pension Regulator  039 s Ai Plan   Accountability</title>
		<description><![CDATA[<p><strong>By Chris Varley, Partner and Head of LGPS Digital, Hymans Robertson</strong></p>

<p>So, we&rsquo;ll start where the plan starts. With what - in my view - is its most important and simplest point. The one thing that must not change in the age of AI. </p>

<div><strong>Accountability </strong></div>

<div>Nothing about who is accountable changes. TPR&rsquo;s plan states clearly &ldquo;Trustees and scheme managers must ensure schemes are well run and deliver good outcomes for members, regardless of which technologies are being used. They remain accountable for decisions and outcomes even when they delegate activities to providers or advisers, such as administrators.&rdquo; </div>

<p>AI does not create a new category of decisions that somebody or something else answers for. Quite to the contrary, it enables new ways of reaching decisions that funds are already accountable for. </p>

<p>This is an important nuance because AI brings with it a subtle temptation. Anyone who&rsquo;s used ChatGPT knows that AI can make it feel easier to hand decisions over to technology. If we are not careful, &ldquo;the AI model recommended we do this&rdquo; could start to become an increasingly used explanation for poor outcomes. </p>

<p>In fact, there have already been legal cases in other industries where organisations have been held accountable for errors made by their chatbots. As an example, Air Canada&rsquo;s customer assistant famously hallucinated a non-existent discount fare. </p>

<p>So far, these claims have been relatively minor, but for pensions, where the financial stakes can be very large, the consequences could be significant. </p>

<p>The Regulator&rsquo;s plan attempts to close that door before it can open. In doing so, turns what could be seen as a philosophical question, into a practical one with which to get started; &ldquo;Do you know where AI is already working on your behalf?&rdquo; </p>

<p>For many funds, that might be a more uncomfortable question than it first appears. </p>

<p>The likelihood is that many could already be using AI without a formal decision ever having been taken. AI has proliferated quickly over the last few years. As a result, it now may well sit inside an administration platform&rsquo;s fraud screening, a member portal&rsquo;s chat assistant or a supplier&rsquo;s document processing. Much of that will have arrived not by way of an explicit board decision, but through IT procurement processes. These tend to focus more on concerns such as cybersecurity and infrastructure compatibility, than accuracy and fairness. </p>

<div><strong>So where should we start with all this?  </strong></div>

<div>It&rsquo;s maybe too obvious to state that good governance begins not with a policy but with visibility. You simply cannot govern what you cannot see, so understanding how and where AI is used at your fund, is a necessary precondition of good governance. </div>

<p>The question then becomes not just whether AI was approved at the point of adoption, but whether it remains fit for purpose over time. </p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/the-pension-regulator--039-s-ai-plan---accountability-27036.htm</link>
<pubDate>Mon, 10 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Fca Review To Drive Higher Standards In Growing Mps Market</title>
		<description><![CDATA[<div>With the sector growing rapidly in recent years, greater scrutiny in these areas is both appropriate and necessary, particularly as advisers seek to demonstrate that the solutions they recommend are delivering good outcomes for clients.</div>

<div> </div>

<div>&ldquo;Scale, longevity and brand recognition should not be treated as substitutes for a robust investment process. The strongest MPS providers will be those that can clearly demonstrate how decisions are made, who is accountable for them and how portfolios are monitored and challenged over time. Advisers should expect evidence-based portfolio construction, formal governance structures and a clearly articulated investment philosophy, rather than relying on broad claims about performance or diversification.</div>

<div> </div>

<div>&ldquo;More consistent guidance on performance reporting and benchmarking would also be a positive development. Advisers need to be able to compare propositions on a meaningful basis, understand the risks being taken and assess whether investors are receiving genuine value after fees. Greater transparency should make it easier to distinguish between providers that have embedded governance throughout their investment process and those treating it primarily as a compliance exercise.</div>

<div> </div>

<div>&ldquo;Ultimately, the FCA review should encourage the MPS industry to move beyond product-led competition and focus more closely on the quality of investment decision-making. Providers that combine strong governance, transparent reporting and institutional-quality portfolio oversight will be best placed to support advisers and deliver better long-term outcomes for investors.&rdquo;</div>

<div> </div>

<div> </div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/fca-review-to-drive-higher-standards-in-growing-mps-market-27039.htm</link>
<pubDate>Mon, 10 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Six Months On  The Investment Outlook Revisited</title>
		<description><![CDATA[<div><iframe allow="accelerometer; autoplay; clipboard-write; encrypted-media; gyroscope; picture-in-picture; web-share" allowfullscreen="" frameborder="0" height="315" referrerpolicy="strict-origin-when-cross-origin" src="https://www.youtube.com/embed/XeO3jGMdz9I?si=L3zNgR177O1yiJ_J" title="YouTube video player" width="340"></iframe></div>

<p> </p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/six-months-on--the-investment-outlook-revisited-27040.htm</link>
<pubDate>Mon, 10 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Favourable Insurance Market Conditions Continue</title>
		<description><![CDATA[<div> Aon have announced the findings from its <a href="https://www.aon.com/en/insights/reports/global-insurance-market-insights">Q2 2026 Global Insurance Market Insights report</a>, which found that abundant capacity and strong competition continue to support favorable conditions for commercial insurance buyers across most major lines of business, with rate reductions, broader coverage and improved terms remaining available across many lines. At the same time, insurers are increasingly using data, analytics and artificial intelligence to guide underwriting decisions and differentiate risks.</div>

<div> </div>

<div><strong>AI and Analytics Are Transforming How Insurers Evaluate Risk</strong></div>

<div>According to the report, insurers are increasingly using data, analytics and artificial intelligence to support underwriting decisions and assess risk quality. While capacity and competition remain the primary drivers of market conditions, AI is enabling more granular and informed risk selection. High-quality risk information is becoming increasingly important as insurers use analytics and AI to make more targeted underwriting and capital deployment decisions.</div>

<div> </div>

<div><strong>Geopolitical Volatility Continues to Reshape Specialty Insurance Markets</strong></div>

<div>The ongoing conflict in the Middle East has resulted in heightened underwriting scrutiny across marine, aviation, terrorism, political violence, energy and trade-related risks. Insurers are placing greater emphasis on policy terms, conditions and exposure management.</div>

<div> </div>

<div><strong>Christian Hoffman, CEO of Global Commercial Risk Solutions at Aon: </strong>The Middle East conflict is driving a differentiated response across the insurance market,  The most pronounced impacts are in Marine Hull & War, Marine P&I, Aviation, and Terrorism & Political Violence, where insurers are exercising greater underwriting discipline, repricing risk and placing increased emphasis on policy terms and conditions. Despite these pressures, capacity remains available across all lines for well-managed risks.&quot;</div>

<div> </div>

<div>The report also highlights broader business implications of geopolitical instability, including supply chain disruption, energy price volatility and heightened  concerns around contingent business interruption exposures.</div>

<div> </div>

<div><strong>Claims Inflation and Casualty Trends Remain Key Watchpoints</strong></div>

<div>Beyond geopolitical developments, the report identifies claims inflation as an ongoing concern across property, casualty and specialty lines. Rising labor, transportation and repair costs continue to impact the value of property claims, while liability claims remain affected by higher legal, medical and settlement costs. These pressures continue to weigh most heavily on commercial automobile and U.S. casualty, which remain notable exceptions to otherwise favorable market conditions.</div>

<div> </div>

<div>Taken together, Aon's study finds that current market conditions present an opportunity for organizations to strengthen insurance programs and optimize risk transfer strategies before market conditions tighten.</div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/favourable-insurance-market-conditions-continue-27027.htm</link>
<pubDate>Thu, 6 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Call To Use Existing Transfer Technology To Fix Loa Problem</title>
		<description><![CDATA[<div>Pension Lab has completed a successful pilot showing that technology already used for pension and investment transfers can also validate Letters of Authority (LoAs) and return selected information through structured digital responses.</div>

<div> </div>

<div>The fintech is now calling on pension providers, platforms, wealth managers and technology firms to extend their existing open standards transfer infrastructure to LoAs - helping reduce delays, manual administration and uncertainty for advisers and their clients without requiring providers to build a new system or join another network.</div>

<div> </div>

<div>The pilot used Discovery Messages, a capability unique to open standards transfers, to check information against provider records, validate or reject requests and, where systems are integrated, return selected information within seconds.</div>

<div> </div>

<div>Open standards transfer service levels require responses to Discovery Messages within two business days. Where organisations have integrated systems, however, responses can be returned within seconds.</div>

<div> </div>

<div>Applying the same capability to LoAs could give providers a faster and more consistent way to validate requests and return information.</div>

<div> </div>

<div>Today, LoA requests reach providers through multiple inboxes, in different formats and with varying levels of information. Teams must identify and route each request, validate the client&rsquo;s authority and supplied data, compile the response and send it back - creating avoidable manual work for providers, uncertainty for advisers and longer waits for clients.</div>

<div> </div>

<div>To help overcome the LoA frustrations, costs and inefficiencies, Pension Lab is urging the industry &ndash; including 150+ organisations already using open standards transfers - to extend their existing transfer technology so that:</div>

<div>Providers benefit by having fewer inboxes, faster validation, reduced manual work, instant LoA validation, and faster initial responses.Advisers benefit by having their LoA request confirmed within seconds, quicker success or missing info alerts, fewer follow-ups, and ultimately improved transfer success.Clients and consumers benefit by having faster, better, more transparent advice and decisions.The market benefits by using existing and cost-effective transfer technology built on established, interoperable infrastructure rather than another proprietary route to help solve LoA frustrations.</div>

<div> </div>

<div><strong>Scott Phillips, CEO and founder of Pension Lab, said: </strong>&ldquo;There is a real irony here. When using the right technology, transfers can be completed in 6 to 10 days using open standards. Yet the Letter of Authority - often the essential first step in that same journey &ndash; can be slower, more manual, and so frustrating for all parties involved.</div>

<div> </div>

<div>&ldquo;Our pilot has shown that the Discovery Messages used in open-standards transfers can help tackle the LoA challenge without providers needing to rebuild new or replace existing systems. Instead, they can rely on a proven infrastructure that supports interoperability and competition.</div>

<div> </div>

<div>&ldquo;For providers already using open-standards transfers, LoA validation and selected information responses can happen in seconds. That matters because providers spend valuable time sorting genuine LoA requests from speculative or incomplete ones. The Discovery Message can help check validity earlier, reduce avoidable manual work and make responses more consistent - one of the clearest examples of how open standards can make LoAs work better.&rdquo;</div>

<div> </div>

<div><strong>Howard Finnegan, Director UK Product Sales for Equisoft, said: </strong>&ldquo;Open standards already do the heavy lifting in transfers, and demand is growing as the industry looks for scalable answers to challenges such as small pots and master trust transfers.</div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/call-to-use-existing-transfer-technology-to-fix-loa-problem-27028.htm</link>
<pubDate>Thu, 6 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Top Urban Hotspots For Wildfires</title>
		<description><![CDATA[<p>London takes the top spot with a wildfire detection referring to a fire event identified through satellite data. This analysis underscores the critical need for insurance providers to integrate historical wildfire data into both the insurance quote process and insurer portfolio management strategies as climate-related risks continue to intensify.</p>

<p><img alt="" src="https://www.actuarialpost.co.uk/images/pic_LexisNexisWildfire0608261.jpg" style="height:343px; width:586px" /></p>

<p>LexisNexis Risk Solutions analysis shows 2025 was the most severe year on record for wildfire activity in the U.K., with satellite technology recording 4,659 wildfire detections. This exceeds the previous peak of 3,305 recorded in 2018 and is nearly five times the 951 detections recorded in 2024.</p>

<p>The data also reveals a clear seasonal pattern in wildfires. Contrary to the common belief that wildfire risk peaks in summer, the LexisNexis Risk Solutions analysis identifies spring as the primary risk window by detection volume. In 2025, 2,635 wildfire detections were recorded in spring compared to 1,606 in summer.</p>

<p>However, spring and winter wildfires tend to occur, on average, almost twice as far from towns and cities as those recorded in summer months. In summer, fires move closer to urban centres, increasing exposure to property and infrastructure and increasing the potential for higher insurance claims severity. The findings are particularly relevant as fire services across parts of the U.K. respond to a series of wildfires during the current heatwave, with authorities warning of extreme pressure and elevated wildfire risk.</p>

<p><strong>Caroline Elliott-Grey, senior product manager, U.K. and Ireland insurance, LexisNexis Risk Solutions, says: </strong>&ldquo;Understanding the risk of wildfires spreading to homes and commercial properties has become almost as important as understanding flood or subsidence risk for property insurance providers. As we move into the peak summer months, following record-breaking temperatures in June and a dry spring[v], it is vital that insurance providers incorporate wildfire risk assessment at an individual property level, at the point of quote, to help price insurance cover accurately and fairly.</p>

<p>&ldquo;Historical wildfire data, combined with geospatial intelligence covering weather patterns, terrain and proximity to infrastructure such as fire stations, enables insurance providers to build a location-specific view of risk. Integrating this insight into property underwriting and pricing allows for more accurate risk assessment, clearer identification of accumulations across insurance provider portfolios, and more informed decisions as climate risks continue to evolve.&rdquo;</p>

<p><a href="https://risk.lexisnexis.co.uk/insights-resources/article/uk-wildfire-risk-data-for-property-insurance-providers?trmid=INSCMP26.UKIComPr26.109897.PRPR109919">LexisNexis Analysis on Top Urban Hotspots for Wildfires</a></p>

<p> </p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/top-urban-hotspots-for-wildfires-27029.htm</link>
<pubDate>Thu, 6 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>With Life Insurance And Ai  Mind The Performance Gap</title>
		<description><![CDATA[<div><u><strong>By Guy Moas, Senior VP of R&D, Sapiens</strong></u></div>

<div> </div>

<div>At the same time, we can improve risk calculations and create an error-free, continuously improving system. However, insurers need to adjust operating models and practices to capitalize on the AI opportunity.</div>

<div> </div>

<div>AI is no panacea and is the polar opposite of the &lsquo;one and done&rsquo; plug-in fix. It requires fundamental changes to achieve its impressively seismic effects. Indeed, when operating models are static, AI doesn&rsquo;t fix weaknesses, nor is it even neutral. Instead, it has the effect of amplifying them.</div>

<div> </div>

<div>Flawed underwriting logic becomes more apparent, inconsistent decisioning scales up and across, and compliance is voided, without even explainability and justification to mitigate the failure of governance.</div>

<div> </div>

<div>As for life insurance customers, operational inefficiencies present themselves in the form of reduced and/or restricted modern, flexible products, slow onboarding, and delayed payouts. And, as life claims often carry a significant emotional burden, inconsistent or impersonal experiences damage insurer-customer trust, leading to lapsed policies and opting out. So, the benefits of AI are great, but any failure to re-engineer thinking and processes also comes with risk.</div>

<div> </div>

<div>Individual failures are aggregated at the industry level into the global protection gap, valued at over $900bn and a figure that represents not just a commercial shortfall, but a failure of the industry&rsquo;s core social purpose.</div>

<div> </div>

<div><strong>The market opportunity</strong></div>

<div>Stronger investment margins have improved insurance performance, but they require a reset. Long-duration liability management and portfolio positioning must adjust to a steeper yield curve, while renewed demand for savings and retirement products is lifting volumes. To absorb that growth, operating models need scalable governance, solid ALM, and tighter capital planning, all to capture the expected uplift through 2027.</div>

<div> </div>

<div>The challenge for insurers is that their operating models are not dynamic enough to give them the agility they need to react in real time to such volatility. This creates what we call the Performance Gap, of which there are five main indicators &ndash; operational, financial, compliance, decision-making, and speed to market.</div>

<div> </div>

<div>The outperforming companies in the coming years will build dynamic operating models capable of absorbing change, aligning decisioning, and sustaining performance across cycles.</div>

<div> </div>

<div><strong>The role of AI</strong></div>

<div>McKinsey estimates that automation and AI can reduce claims-handling costs by 25 to 30%, and compress processing times by 40-50%. Forrester&rsquo;s 2026 forecast adds that AI and automation will improve expense ratios at the top 50 insurers by two percentage points, but only for carriers that have scaled beyond pilots into full production.</div>

<div> </div>

<div>So, how are insurers making use of AI? It&rsquo;s clear to me that the world is moving fast on LLMs and, sooner or later, we will see more adoption of embedded models unique to insurers as price points fall and as models mean that use cases become more immediately relevant.</div>

<div> </div>

<div>But it&rsquo;s also important that organisations plan for softer factors. One area to consider here is the impact on skills. Insurance veterans are used to specific role-based skills such as claims handling or underwriting. But AI acts as an accelerator here, flattening roles and steamrollering discrete processes.</div>

<div> </div>

<div>So, insurers need to think about how they encourage people to be all-rounders capable of orchestrating and adding value to end-to-end processes.</div>

<div> </div>

<div>Time to market is also key to success in modern insurance and AI is an enabler of this. But it&rsquo;s also an enabler of speeding up customer activities.</div>

<div> </div>

<div>Underwriting, for example, is still extensively based on lengthy, time-consuming questionnaires and check-list questions. AI is a massive force for collation, number-crunching and interpretation. We still need the human in the loop, but we can get to decisions faster and delight customers in doing so. Similarly, on the claims side, we see massive potential in how to initiate claims and in compliance management because we can narrow down the level of potential misunderstanding or misalignment.<br />
 </div>

<div>AI is only going to become more important, particularly now we can make use of so-called RAG and CAG tools to accelerate integration of data to and from LLMs, via query retrieval and pre-load caching techniques, respectively. That means, practically, that a junior underwriter, for example, can quickly cycle through harnessing key information, gaining managerial approval and completing the end-to-end process. Administration becomes a sign-off action and manual inputs are massively reduced.</div>

<div> </div>

<div>We are reaching the point where we are mapping all the key data in the insurance organisation, but also, just as important, seeing what is missing so an external source may be plugged in or another action taken.</div>

<div> </div>

<div>Insurers can&rsquo;t be bystanders, and they can&rsquo;t just rest on their laurels and admire their work in being benign early adopters of AI. The winners in the sector will be those who deploy at scale, and make the necessary adjustments to people and processes to take advantage of one of the great technology-enabled waves of change in our lifetimes.</div>

<div> </div>

<p> </p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/with-life-insurance-and-ai--mind-the-performance-gap-27035.htm</link>
<pubDate>Thu, 6 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Whose Surplus Is It Anyway </title>
		<description><![CDATA[<div>In its latest paper,<strong> <a href="https://www.actuarialpost.co.uk/downloads/cat_1/Hymans-whose-surplus-is-it-anyway-2026.pdf">'Whose surplus is it anyway?'</a></strong>, the firm argues that leaving difficult conversations until surplus decisions are needed could make agreement harder to reach. If schemes fail to resolve this now, disagreements over surplus allocation could delay endgame plans, increase costs and risks. It warns there are widely differing expectations around pension surplus allocation. This is creating a growing challenge for schemes as funding levels improve. The firm believes that key to unlocking any deadlock is for all parties to analyse the scheme&rsquo;s surplus history. In doing this they can weigh up all relevant factors, to create a stronger basis for discussions about surplus ownership.</div>

<div> </div>

<div>The leading pensions and financial services consultancy argues that understanding the origins of a surplus is crucial. Many schemes spent decades managing deficits, with trustees overseeing recovery plans and risk reduction strategies. Surplus history analysis can help establish the relative contribution of all the different factors and provide an informed basis for discussions about surplus allocation.</div>

<div> </div>

<div>While there may not be a single answer to the surplus-sharing question, schemes that understand their history will be better placed to navigate one of the most complex and contentious issues currently facing the defined benefit pensions market.</div>

<div> </div>

<div><strong>Commenting on surplus allocation, Martin Potter, Partner and Scheme Actuary, Hymans Robertson, said: </strong>&ldquo;There are strong views on all sides when it comes to pension scheme surplus. For some, the starting point is that all surplus belongs to the employer. For others, there are clear expectations that members should benefit. The challenge is that these positions are often formed before there has been any detailed discussion about how the surplus actually came about.</div>

<div> </div>

<div>&ldquo;As more schemes find themselves in surplus, competing expectations about how those funds should be used is an increasingly important issue for trustees and employers. Without engagement, there is a risk that expectations continue to diverge and become increasingly difficult to reconcile. That's why we believe trustees and employers should establish a clear, objective understanding of their scheme's journey back to surplus before making decisions about how any excess assets might be used.</div>

<div> </div>

<div>&ldquo;Surplus history analysis helps schemes move beyond assumptions and focus on evidence. Looking at factors such as employer contributions, investment returns and member experience over time provides valuable context for discussions about fairness and the appropriate use of surplus. Understanding the origins of surplus is particularly important given the long period many schemes spent managing deficits, with employers contributing substantial sums and trustees overseeing funding recovery plans and risk reduction strategies.</div>

<div> </div>

<div>&ldquo;There may not be a mathematically &lsquo;correct&rsquo; answer to the surplus-sharing question, but schemes that understand their history will be in a much stronger position to navigate one of the most complex and contentious issues facing the defined benefit pensions market today. A surplus history analysis can help ensure decisions are informed by facts rather than competing narratives.&rdquo;</div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/whose-surplus-is-it-anyway--27033.htm</link>
<pubDate>Thu, 6 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Db Pensions Adopt Objective led Approach To Endgame Planning</title>
		<description><![CDATA[<div>Trustees and corporate sponsors of UK Defined Benefit (DB) pension schemes should move away from treating insurance buyout as an automatic default and instead adopt an &quot;objective-led&quot; approach to endgame planning, according to a roundtable report released today by the SPP.</div>

<div> </div>

<div>The report, titled <a href="https://www.actuarialpost.co.uk/downloads/cat_1/SPP-Roundtable-Report-Choosing-an-Endgame-6.8.26-1.pdf"><strong>Choosing an Endgame: Timing, Trade-offs, and Trustee Decision-Making</strong></a>, synthesises insights from a major industry roundtable of leading actuaries, trustees, legal advisers, investment managers, and covenant specialists.</div>

<div> </div>

<div>The paper challenges traditional industry momentum by examining how improved funding positions, a &pound;160 billion aggregate surplus across UK DB schemes, and new alternatives such as superfunds and capital run-on strategies have transformed the endgame landscape.</div>

<div> </div>

<div><strong>Key Insights & Findings:</strong></div>

<div> </div>

<div><strong>From Outcome-Led to Objective-Led</strong></div>

<div>Industry professionals suggest trustee boards and sponsors should not assume buyout is the only valid destination. Strategic planning must start with clear, ranked objectives balancing benefit security, affordability, discretionary member upside, and corporate balance sheet risk.</div>

<div> </div>

<div><strong>The &pound;160bn Surplus Dilemma</strong></div>

<div>With surpluses across many schemes, an immediate buyout may permanently forfeit potential financial upsides for members and sponsors. Trustees face a nuanced value judgement between securing immediate guaranteed outcomes versus managed run-on strategies.</div>

<div> </div>

<div><strong>Size is not everything</strong></div>

<div>While smaller schemes face higher per-member governance costs that often make insurance buyout the most efficient path, scale alone should not dictate strategy.</div>

<div> </div>

<div><strong>Robust Governance & Dual Strategies</strong></div>

<div>To manage adviser conflicts and market volatility, schemes are advised to establish documented contingency frameworks (&quot;Plan A and Plan B&quot;) with explicit, agreed financial triggers to shift direction when market or sponsor conditions change.</div>

<div> </div>

<div><strong>SPP Covenant Committee member Alex Beecraft, who chaired the roundtable, said: </strong>&quot;The traditional assumption that buyout with an insurance company represents the default, automatic 'endgame' is increasingly being challenged. As the DB pension landscape evolves, decision-making should shift from being outcome-led to objective-led, balancing long-term member security against economic upside, commercial realities, and the expanding array of risk management tools available today. Crucially, where schemes elect to run-on, this should not be viewed as a permanent rejection of a risk transfer transaction, but rather a timing decision of 'not now'.&quot;</div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/db-pensions-adopt-objective-led-approach-to-endgame-planning-27034.htm</link>
<pubDate>Thu, 6 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Pet Insurance Prices Fall In Q2 But June Rebounds</title>
		<description><![CDATA[<div>Average top-five prices for Lifetime cover fell by -1.8% across Q2. Prices declined by -2.3% in both April and May before rising by 2.8% in June, partly reversing the reductions recorded earlier in the quarter. Despite the June increase, Lifetime prices remain -6.4% lower than at the beginning of the year and have fallen by -7.8% over the past 12 months.</div>

<div> </div>

<div><strong>Higher-cover products lead the rebound</strong></div>

<div>The change in direction was particularly evident among products offering higher levels of veterinary fee cover. Average top-five prices for policies providing at least &pound;5,000 of cover rose by 1.7% during Q2, although they remain -5.9% lower than a year ago. The contrasting quarterly and annual movements indicate that insurers may be beginning to adjust prices selectively, rather than applying increases consistently across their portfolios.</div>

<div> </div>

<div>Price movements also varied by policy type. Maximum Benefit and Time-Limited policies recorded only modest year-on-year reductions and did not experience the pronounced fall in prices seen among Lifetime products during the first quarter.</div>

<div> </div>

<div><strong>Prices rise across the market in June</strong></div>

<div>The June increase was broad-based, with prices rising for both cats and dogs, across every age group and in all UK regions. However, annual reductions remain significant. Average top-five prices for dogs are -8% lower than a year ago, compared with a -6% reduction for cats. Prices for kittens and puppies have fallen by around -10%, while the reduction for animals aged over six is approximately -4%.</div>

<div> </div>

<div><strong>Customer contributions rise as veterinary costs continue to climb</strong></div>

<div>The reduction in headline prices continues to contrast with the rising cost of veterinary care. Since 2023, Defaqto&rsquo;s analysis shows that its index of pet insurance prices has increased by approximately 4%, compared with a 31% rise in the ONS Veterinary Services Index.</div>

<div> </div>

<div>Insurers are increasingly managing this gap through product design, including higher excesses and co-payments. Defaqto&rsquo;s analysis shows that a customer claiming the full veterinary fee allowance would, on average, contribute around 20% more towards the claim than they would have done 12 months ago.</div>

<div> </div>

<div><strong>Frances Luery, Product Manager at Defaqto, said: </strong>&ldquo;Pet insurance prices continued to fall overall during the second quarter, but June marked a clear change in direction. A 2.8% monthly increase does not establish a new trend on its own, although the breadth of the movement suggests that some insurers are beginning to respond to the growing gap between premiums and veterinary costs.</div>

<div> </div>

<div>&ldquo;The market remains highly competitive and consumers can still benefit from prices that are materially lower than a year ago. However, the headline premium is only part of the picture. Excesses, co-payments and other customer contributions are becoming increasingly important as insurers seek to manage claims inflation. We expect pricing to remain competitive, but further selective increases are likely during the second half of the year as insurers seek to balance affordability with the sustained rise in veterinary and claims costs.&rdquo;</div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/pet-insurance-prices-fall-in-q2-but-june-rebounds-27023.htm</link>
<pubDate>Wed, 5 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>So You ve Connected To Pensions Dashboards  What Next </title>
		<description><![CDATA[<p><strong>By Ella Holloway, Senior Consultant at LCP</strong></p>

<p>Since the dashboards regulations were laid, we&rsquo;ve had several dashboards-related ministerial statements, one &lsquo;reset&rsquo; and six pensions ministers, and now the statutory deadline for connection of 31 October 2026 is finally in sight. Connection is a milestone moment for any scheme in scope for pensions dashboards, but of course it is just the beginning. With the public launch of the MoneyHelper dashboard possibly only a year away, how prepared is your administrator for the next phase?</p>

<div><strong>Handling possible matches</strong></div>

<div>While administrators might have modelled how many possible matches they expect to receive on a scheme, based on how clean members&rsquo; data is and the combinations used in their matching strategy, this will still only act as a rough guide. Users might not provide all the data items used in a matching strategy (particularly a National Insurance number), or may mistype those items which are not verified before they are used to match. If your administrator doesn&rsquo;t have a matching policy that can help deal with such scenarios, it may end up producing more possible matches than originally thought.</div>

<p>While the onus is on users to contact schemes to resolve possible matches, administrators need to be ready should the majority choose to do so. How will your administrator handle potential match queries &ndash; are they planning a dedicated telephone line or an online form specifically for this purpose? And how automated is the process? How much does it rely on resource that may need to be taken from business as usual queries or other projects?</p>

<div><strong>Can your administrator meet the 10-day deadline for benefit data?</strong></div>

<div>The provision of Value &ndash; or benefit &ndash; data is a key element of pensions dashboards, and users will expect to see it when they log on. Schemes will have varying levels of Value data provision, for a variety of reasons. Smaller schemes and those about to trigger wind up may decide that the cost of calculating all members&rsquo; benefits solely for dashboards is not a viable exercise. Most schemes will also have small cohorts of &lsquo;special case&rsquo; members where it would be time consuming and expensive to calculate their benefits in advance when the members might not even access dashboards.</div>

<p>Administrators need to have a plan to deal with these members should they access dashboards and request this information &ndash; even if a large scheme is 95% automated, that may still leave several hundred members needing benefit data calculated on request. And with a statutory 10 working day deadline to provide defined benefit information (and only three for defined contribution), it&rsquo;s going to require a slick and well managed process.</p>

<div><strong>Planning for follow-up queries</strong></div>

<div>We hope that insights gained from the user testing currently being carried out on the MoneyHelper dashboard will show what users typically do after visiting dashboards. Administrators should use this information to model how many of their members might request a retirement or transfer quote, or contact them with a more general dashboards query, and plan how to resource any uptick in work. Again, will they be relying on existing resource, or perhaps a digital solution to manage some of these queries? And have they explained to you how they might charge for this extra work?</div>

<div> </div>

<div><strong>What management information should your administrator record?</strong></div>

<div>The retention of management information is a requirement under the dashboard regulations, and your administrators &ndash; including any AVC providers who are connecting directly to dashboards - should be recording various metrics once your scheme is connected. This includes items such as the number of view requests received and the time taken to respond to each one, the use of Value data unavailable codes, and confirmation that the scheme has remained connected to dashboards for over 99.5% of the time.</div>

<p>For now this information needs only to be recorded and made available to regulatory bodies on request, but routine reporting of these metrics is expected to be a requirement in future. As trustees, you are ultimately responsible for recording this information, so make sure your administrator has a plan for doing this on your behalf which is compliant and transparent. They should also have a way of letting you view and keep track of key dashboard metrics, be that via quarterly administration reports or a live dashboard that shows the information in real time.</p>

<p>While trustees&rsquo; focus has for so long been on connecting schemes to dashboards, they now need to look ahead to the initiative&rsquo;s next phase. Ask your administrator what plans they are putting in place for each of the areas above. And ask them how you can help prepare for the launch of the MoneyHelper dashboard &ndash; consider putting an item in your next newsletter warming members up to dashboards so they know what they can expect to see and what they need to do should they have a query. Can you use your communications to explain to members why keeping their details up to date with all of their pension schemes will be beneficial? Taking the time now to work out what might be needed, and how these needs will be met, could make for a less painful experience when dashboards are launched to the public.</p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/so-you-ve-connected-to-pensions-dashboards--what-next--27025.htm</link>
<pubDate>Wed, 5 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Tribunal Upholds Fca Ban On Pair In Pension Transfer Advice</title>
		<description><![CDATA[<p>The Tribunal found that Ms Dunne falsely claimed she had given advice to some pension schemes before she had done so. Also, that she had failed to take proper care when giving pension transfer advice. Meanwhile Mr Fenech failed to properly oversee her work.</p>

<p>Ms Dunne advised about 92% of her clients to move out of defined benefit pension schemes between April 2015 and June 2017. This led to more than &pound;126m being transferred, including when it was not in clients&rsquo; best interests.</p>

<p>The FCA had based both fines on the finding that all of Ms Dunne's advice breached regulatory requirements. The Tribunal ruled that the fines should reflect its finding that 18% of Ms Dunne's clients received unsuitable advice. It also ruled that only the income Mr Fenech earned from his relationship with Ms Dunne should count towards his fine. </p>

<p><strong>Therese Chambers, the FCA's executive director of enforcement and market oversight, said: </strong>'We welcome the Tribunal's ruling, which supports our decision that Mr Fenech and Ms Dunne are unfit to work in financial services. The Tribunal agreed that the FCA must be able to rely on those it regulates at all times, including in periods of stress and high pressure. These individuals failed that test and breached the trust placed in them. Dishonesty and negligence have no place in our industry, and we will continue to take action against those who fall short of our standards.'</p>

<p>The Tribunal agreed fines were appropriate but reduced these to &pound;41,230 for Ms Dunne and &pound;16,046 for Mr Fenech.</p>

<div><em>Upper Tribunal judgments: <a href="https://assets.publishing.service.gov.uk/media/69ef4368606c20d412163429/Fenech_and_Dunne_final_for_issue.docx.pdf">27 April 2026</a> and <a href="https://assets.publishing.service.gov.uk/media/6a6722935e871227830938c7/Fenech_and_Dunne_v_FCA_Penalties_Final_for_Issue.pdf">27 July 2026</a></em></div>

<div><em>Ms Dunne and Mr Fenech have 14 days from the date of the Upper Tribunal's decision to appeal.</em></div>

<div><em><a href="https://www.fca.org.uk/publication/decision-notices/heather-dunne-2024.pdf">Decision Notice 2024: Heather Dunne.</a></em></div>

<div><a href="https://www.fca.org.uk/publication/decision-notices/richard-fenech-2024.pdf"><em>Decision Notice 2024: Richard Fenech.</em></a></div>

<div><em>Ms Dunne traded as an independent financial adviser under Heather Dunne Independent Financial Adviser (HDIFA) and was a pension transfer specialist. HDIFA was an appointed representative of Financial Solutions Midhurst Ltd (FSML), which was owned and run by Mr Fenech.</em></div>

<div><em>Information for customers wishing to make a <a href="https://www.fscs.org.uk/making-a-claim/claims-process/complaints/">complaint to the Financial Services Compensation SchemeLink is external.</a></em></div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/tribunal-upholds-fca-ban-on-pair-in-pension-transfer-advice-27024.htm</link>
<pubDate>Wed, 5 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Who Can Spot A Pension Scam </title>
		<description><![CDATA[<div>Many UK adults could struggle to spot some of the most common warning signs of a pension scam, according to new research from Standard Life, a retirement specialist focused entirely on retirement savings and income.</div>

<div> </div>

<div>Despite 62% of people saying they feel confident that they could spot a pension scam, Standard Life&rsquo;s pension scam test found that three in five (60%) people did not know that pension providers or advisers are not legally allowed to cold call people about pension opportunities or reviews &ndash; a misunderstanding that could make it harder to recognise one of the most common warning signs of a pension scam.</div>

<div> </div>

<div>According to Report Fraud, UK pension scam victims lost an average of around &pound;47,000 last year, highlighting the importance of protecting retirement savings that people have often spent decades building. More broadly, the findings suggest some savers may be vulnerable to approaches that exploit misunderstandings about how pensions work, what legitimate firms can and cannot do, and which checks are worth making before taking action.</div>

<div> </div>

<div><strong>How did people score on a pension scam test?</strong></div>

<div>The research explored several common myths and misunderstandings that scammers can use to make fraudulent approaches appear more convincing.</div>

<div> </div>

<div>Nearly three in four (73%) either believed that if a company appears on the FCA register, any investment it offers is guaranteed to be safe, or were unsure.Three in five (60%) either got the answer wrong or said they did not know whether pension providers or advisers are legally allowed to cold call people about pension opportunities or reviews.Four in ten (40%) either believed you can withdraw money from your pension at any age or said they did not know.</div>

<div> </div>

<div>The findings suggest there is an opportunity to improve understanding of some key pension rules and scam warning signs, helping more people feel confident identifying risks and making informed decisions about their financial future.</div>

<div> </div>

<div><strong>False signs of trust</strong></div>

<div>The findings also suggest some people may be placing trust in factors that do not necessarily indicate whether a pension opportunity is genuine. One in five (20%) believe a professional-looking website and positive online reviews are reliable indicators that a pension opportunity is genuine, while one in seven (14%) believe adverts on professional or social networking sites mean a company is trustworthy and can act in their best interests.</div>

<div> </div>

<div>Encouragingly, more than half (53%) correctly identified that a pension scam may involve real companies, real advisers and genuine paperwork, suggesting many people recognise that modern scams are not always easy to spot. This is an important distinction, as some of the most serious risks can arise where an approach looks legitimate on the surface but involves unsuitable investments, poor advice or recommendations that are not in a saver&rsquo;s best interests.</div>

<div> </div>

<div><strong>Not everyone is carrying out independent checks</strong></div>

<div>Despite this, some people are still not taking independent steps to verify opportunities before engaging with them. While some said they discussed the opportunity with family or friends (7%) or researched the company online (7%), 8% admitted they carried out no checks at all.</div>

<div> </div>

<div><strong>Donna Walsh, Head of Master Trust and IGC Governance at Standard Life, said:</strong> &quot;Pension scams are increasingly sophisticated making them appear genuine. They can come with convincing websites, positive reviews, familiar names and paperwork which is exactly why they can be so dangerous. What stands out from our test is that many people could benefit from greater awareness of some key pension rules and warning signs. That's important because understanding how pensions work can help people make more confident decisions and better protect the savings they've worked hard to build.  </div>

<div> </div>

<div>The industry from providers, workplace employers, and advisers to our regulators, is taking action and pulling together to build awareness to help pension scheme members spot fraudulent approaches. Likewise, a reinvigorated PSIG, the pensions scams industry group, is stepping up its activity and education programme to combat such approaches. </div>

<div> </div>

<div>&ldquo;With changes to the inheritance tax treatment of pensions approaching and people likely to be reassessing their retirement plans increased vigilance is required, with fraudsters often quick to exploit periods of change and uncertainty. </div>

<div> </div>

<div>&ldquo;The best protection people can take is to pause, check independently and avoid being rushed. A legitimate pension opportunity should never depend on pressure, urgency or confusion. If in doubt, contact your pension provider. The more people understand the warning signs and know which checks to make, the better placed they are to protect their savings, achieve greater financial security in later life and make informed decisions about their financial future.&quot; </div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/who-can-spot-a-pension-scam--27026.htm</link>
<pubDate>Wed, 5 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Pensions Iht Ripple Effect 22  Have Less Trust In Pensions</title>
		<description><![CDATA[<div>The upcoming pensions IHT change in April 2027 is having a wider impact on pensions confidence despite the majority of adults being unaffected, new research from Standard Life finds.</div>

<div> </div>

<div>Around half (49%) of adults say their confidence in pensions remains unchanged, but just over a fifth (22%) say this has reduced since the new rules were announced in the 2024 Autumn Budget.</div>

<div> </div>

<div>The change comes against a backdrop of a &ldquo;perfect storm&rdquo; for IHT of a frozen nil-rate band (until April 2031) and rising asset values. IHT receipts are projected to increase from &pound;8.7bn in 2025/26 to &pound;14.5bn in 2030/31.</div>

<div> </div>

<div>For those with lower pension confidence, passing on a higher IHT burden tops concerns. This is followed by uncertainty on the new rules and complexities around pensions more generally.</div>

<div><img alt="" src="https://www.actuarialpost.co.uk/images/pic_StandardLifeIHT10408261.jpg" style="height:300px; width:448px" /></div>

<div><em style="font-size:11px">Standard Life research: Q: You mentioned you have less confidence in pensions because of the upcoming inheritance tax (IHT) rule change. Why is that? Base: 460 (weighted to be nationally representative)</em></div>

<div> </div>

<div><strong>Overestimating IHT liabilities</strong></div>

<div>Forecasts suggest that in 2027/28, around 213,000 estates will include unused pension funds, representing almost one in three deaths in the UK. However, despite the introduction of new IHT rules, more than three-quarters of these estates (~164,000) are still expected to pass on their pension savings free from IHT. The remaining estates are expected to face a financial impact, either because they become liable for IHT for the first time or because they will pay a higher tax bill.</div>

<div> </div>

<div>Most estates with unused pension funds will fall below the available IHT thresholds, including the Nil Rate Band and Residence Nil Rate Band, or assets will pass to a surviving spouse or civil partner, who are typically exempt from IHT. For married couples and civil partners, the combined IHT allowances can allow up to &pound;1 million to be passed on tax-free when a main residence is included.</div>

<div> </div>

<div><strong>Impact of pension IHT change on estates in 2027/28</strong></div>

<div><strong><img alt="" src="https://www.actuarialpost.co.uk/images/pic_StandardLifeIHT20408261.jpg" style="height:214px; width:600px" /></strong></div>

<div>Over time, the number affected is likely to rise as frozen IHT thresholds and growing asset values gradually drag more estates into paying IHT. However, the change is most significant for those who had planned to preserve pension assets for IHT purposes, rather than draw on them to provide retirement income. Effective retirement saving and decumulation strategies can help people make the most of their pension wealth and achieve their long-term retirement goals.</div>

<div> </div>

<div><strong>Neil Jones, Tax and Wealth planning specialist at Standard Life said: </strong>&ldquo;There is a real risk that the upcoming IHT change could undermine confidence in pensions, with some people considering alternatives for their long-term savings. The research is a timely reminder for the new Prime Minister that even seemingly technical changes to pensions and savings rules can seep into the public consciousness and influence behaviour. Pensions are a long-term investment, often built over decades, so people need confidence that the rules supporting retirement saving will remain stable. Moving away from pensions could mean sacrificing a sustainable retirement income to avoid a tax people may never pay.&rdquo;</div>

<div> </div>

<div><strong>Impact of pension pausing</strong></div>

<div>Individuals thinking about pension changes should consider the future impact on retirement income. Standard Life analysis shows that an employee in their mid-20s earning &pound;25k could lose out on &pound;5,014 in today&rsquo;s money terms at retirement age from pausing pension contributions for just one year, if contributing the auto-enrolment minimum. Pausing for 5-years could means losing out on &pound;24,715.</div>

<div> </div>

<div><strong>Total retirement fund at age 68 for 25-year-old</strong></div>

<div><img alt="" src="https://www.actuarialpost.co.uk/images/pic_StandardLifeIHT30408261.jpg" style="height:85px; width:531px" /></div>

<div><span style="font-size:11px"><em>Standard Life analysis: assumes &pound;25k starting salary, 3.50% salary growth/yr, and 5%/yr investment growth (less annual management charge of 0.75%). Figures shown in real term accounting for 2% inflation. Fund starting at &pound;0 aged 25. 8% pension contribution on full salary. Values are used as an illustration and are not guaranteed.</em></span></div>

<div> </div>

<div><strong>Neil Jones continues: </strong>&ldquo;Pensions are central to retirement planning and one of the most tax efficient ways to build retirement savings. This won&rsquo;t change post April 2027. They carry the triple benefit of pensions tax relief, long-term gains from compound interest, and employer contributions for eligible employees. Those considering alternatives should carefully weigh up any long-term impact before making decisions.</div>

<div> </div>

<div>&ldquo;Those who think they might be impacted should speak to a qualified professional such as a financial adviser or estate planner. For this group, the benefits of pension saving may still outweigh any potential IHT implications, but an adviser will be able to support with each individual circumstance.&rdquo;</div>

<p> </p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/pensions-iht-ripple-effect-22--have-less-trust-in-pensions-27019.htm</link>
<pubDate>Tue, 4 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>August 2026 Edition Of The Actuarial Post Magazine</title>
		<description><![CDATA[<div>
<p><a href="https://library.myebook.com/ActuarialPost/actuarial-post-august-2026/6735/#page/1"><img alt="" src="https://www.actuarialpost.co.uk/images/pic_APMagazineAUGUST2026.jpg" style="float:right; height:276px; width:199px" /></a>Well, they say a week is a long time in politics and true to the saying we now have a new Prime Minister in Andy Burnham and the Middle East peace talks, well, they now have the honour of the longest every peace talks in history with no end in sight. I was hoping to talk about a World Cup triumph but unfortunately, we were beaten by Argentina, the less said about their lack of sportsmanship in the final the better. Congratulation to worthy winners in Spain. We also had within a single week in July, France recording its most devastating wildfire outbreak in at least half a century and Spain recording the largest wildfire in its modern history.</p>

<p>Our usual authors give their insights including a new series from Bolton Associates interviewing actuaries within the Catastrophe Modelling space.</p>

<p>We look forward to welcoming you all back next month.</p>
</div>

<div> </div>

<div> </div>

<div><a href="https://library.myebook.com/ActuarialPost/actuarial-post-august-2026/6735/#page/6">News</a></div>

<div><a href="https://library.myebook.com/ActuarialPost/actuarial-post-august-2026/6735/#page/8">Movers & Shakers</a><br />
<a href="https://library.myebook.com/ActuarialPost/actuarial-post-august-2026/6735/#page/8">City Dealings</a></div>

<div><a href="https://library.myebook.com/ActuarialPost/actuarial-post-august-2026/6735/#page/10">Insuring an Income in Retirement by Dale Critchley, Aviva</a></div>

<div><a href="https://library.myebook.com/ActuarialPost/actuarial-post-august-2026/6735/#page/12">Virgin Media - What Now for Pensions by PMI members Joe Moore and Julia Yates</a></div>

<div><a href="https://library.myebook.com/ActuarialPost/actuarial-post-august-2026/6735/#page/14">FCA Financial Systems- By Mark Francis, FCA and Simon Dixon, PRA</a></div>

<div><a href="https://library.myebook.com/ActuarialPost/actuarial-post-august-2026/6735/#page/16">Retirement Puzzle by Alex White from Gallagher</a></div>

<div><a href="https://library.myebook.com/ActuarialPost/actuarial-post-august-2026/6735/#page/18">Lights, Camera, Actuary! by Claire Chowne from Bolton Associates</a></div>

<div><a href="https://library.myebook.com/ActuarialPost/actuarial-post-august-2026/6735/#page/20">Information Exchange by Tom Clarke, Director of Motor Strategy, LexisNexis Risk Solutions</a><br />
<a href="https://library.myebook.com/ActuarialPost/actuarial-post-august-2026/6735/#page/22">Recruitment</a></div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/august-2026-edition-of-the-actuarial-post-magazine-27021.htm</link>
<pubDate>Tue, 4 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>7 Steps To Protect Finances From Whatever The Budget Holds</title>
		<description><![CDATA[<p><strong>Sarah Coles, head of personal finance at AJ Bell, comments: </strong>&ldquo;Like Christmas, Budget speculation season has kicked off even earlier this year, with everything from wealth taxes to frozen tax thresholds being thrown into the mix. When faced with the threat of higher taxes, people will always want to take steps to protect themselves. But if you do, it&rsquo;s essential to focus on those you&rsquo;ll be grateful for, whatever the Budget delivers.</p>

<p>&ldquo;We know from previous years just how much damage people can do to their finances if they feel forced into panicked decisions. Ahead of both the 2024 and 2025 Budgets, widespread speculation about possible reform to tax-free cash on pensions persuaded people to raid their pots. AJ Bell analysis of FCA data indicates that in 2024/25 an additional &pound;10 billion may have been taken out of pensions for no reason other than panic.</p>

<p>&ldquo;If this money is withdrawn without a plan, there&rsquo;s a real risk it comes out of a tax-efficient environment, misses out on investment growth, and is eroded by tax, inflation and incidental spending. It&rsquo;s why AJ Bell has written to Chancellor John Healey, calling for a &lsquo;Pensions Tax Lock&rsquo;, and urging him to commit to long-term pension tax stability.</p>

<p>&ldquo;The fact that raiding your pensions may not be the best approach doesn&rsquo;t mean you have to sit and wait to be knocked sideways by fiscal surprises, because there are still seven sure-fire steps you can take ahead of 28 October, which you&rsquo;ll be grateful for whatever the Budget holds.&rdquo;</p>

<div><strong>Protect existing investments</strong></div>

<div>&ldquo;Wealth taxes have already been the subject of some speculation. During the Makerfield by-election, Andy Burnham said he would look in detail at Wes Streeting&rsquo;s proposal to equalise capital gains tax with income tax, pushing that potential tax increase to the top of people&rsquo;s minds.</div>

<p>&ldquo;Recent governments have demonstrated enthusiasm for moving investment tax thresholds and rates, and there&rsquo;s nothing to stop them doing it again. If you have investments outside an ISA, and the available allowance this year, you can move investments into a Stocks and Shares ISA using the Bed and ISA process to protect them from dividend and capital gains tax.&rdquo;</p>

<div><strong>Protect new investments</strong></div>

<div>&ldquo;If you&rsquo;re starting out with investments, or topping them up, Stocks and Shares ISAs should be your first port of call, so you&rsquo;re protected from tax from day one.&rdquo;</div>

<div> </div>

<div><strong>Protect your savings</strong></div>

<div>&ldquo;Even if nothing else is announced in the Budget, the tax on savings interest will rise by two percentage points at the start of the new tax year, and the Cash ISA allowance will fall to &pound;12,000 for people under the age of 65. There&rsquo;s always the chance this isn&rsquo;t the end of the bad news on savings taxes either. It means that if you have some of your ISA allowance available, it&rsquo;s worth moving savings into a Cash ISA, where the interest is completely protected from tax. Alternatively, if you don&rsquo;t envisage needing to use a portion of your cash savings for longer than five years, you may want to consider investing them using a Stocks and Shares ISA.&rdquo;</div>

<div> </div>

<div><strong>Protect yourself from a wealth tax</strong></div>

<div>&ldquo;If the government was to consider a broader wealth tax, and bring in some sort of levy on overall assets, it could focus people&rsquo;s minds on how they hold assets as a family. Even if there are no changes, you can save an impressive amount of tax this way. If you&rsquo;re married or in a civil partnership, transferring them between you won&rsquo;t trigger a tax bill. Not only will it cut how much one of you owns, but it also means you can both take advantage of annual allowances for things like dividends and capital gains tax. Plus you can make the most of two sets of annual pension and ISA allowances, so as much of your portfolio is protected from tax as possible. If you have children, you could also consider investing for them through Junior ISAs or Junior SIPPs. Think carefully about what you can afford to give away, so you don&rsquo;t regret losing those assets, but if gifts are affordable, they can save a big chunk of tax and protect you from the risk of an overall wealth tax too.&rdquo;</div>

<div> </div>

<div><strong>Consider lifetime gifts</strong></div>

<div>&ldquo;Any Budget may hold the risk of changes to inheritance tax &ndash; whether it&rsquo;s the cutting of allowances, the removal of exemptions or a new cap on gifts. No government will want to wade into this thorny area without careful consideration of a potential backlash, but even if they don&rsquo;t, you could be grateful for the fact you used this opportunity to plan ahead. You can give large gifts, which will leave your estate for inheritance tax purposes after seven years. You also have a &pound;3,000 annual gift allowance, you can give &pound;250 away to any number of people, and there are gift allowances for weddings. In addition, you can give regular gifts from income, which leave your estate immediately for tax purposes. The key is not to give away too much, too soon. If you&rsquo;re not sure what you can afford to part with, it&rsquo;s worth speaking to a financial adviser, who can assess your finances and model what you&rsquo;re likely to need, and what you can give away.&rdquo;</div>

<div> </div>

<div><strong>Protect against frozen tax thresholds by paying into a pension</strong></div>

<div>&ldquo;Making extra pension contributions is a brilliant way to cut your income tax bill, while building your resilience later in life. It also helps protect you from the impact of frozen tax thresholds. If a pay rise has pushed you over a frozen income tax threshold, upping pension contributions may bring you back down below it by reducing what&rsquo;s called your adjusted net income. It&rsquo;s worth checking if your employer will match any additional contributions into your workplace pension, to super-charge your efforts. If not, you can consider other pension options, and whether you&rsquo;d benefit from the extra choice and flexibility of a SIPP, which you can access from age 55 (rising to 57 in 2028).&rdquo;</div>

<div> </div>

<div><strong>Secure pension tax relief while you know where you stand</strong></div>

<div>&ldquo;While the sensible approach would be for the government to commit to making no changes to tax relief, and to do it early, if there are no commitments forthcoming, you can take advantage of pension tax relief while you know where you stand. Consider how much you can afford to pay into your pension, and boost your contributions if it makes sense. If there ends up being no change, all you&rsquo;ve done is improve your retirement finances.&rdquo;</div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/7-steps-to-protect-finances-from-whatever-the-budget-holds-27022.htm</link>
<pubDate>Tue, 4 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Pension Engagement Rising But Retirement Decisions Difficult</title>
		<description><![CDATA[<p>Pension savers are more actively engaging with their retirement savings, but many remain unsure how they will use their pension when they retire, according to the latest member research from TPT Retirement Solutions (&quot;TPT&quot;).</p>

<p>The findings point to a clear rise in engagement since 2024, with more members checking their pensions, exploring what income it could provide and reviewing the choices available to them as they approach retirement. Overall, the proportion of members regularly reviewing their TPT pension increased from 38% in 2024 to 45% in 2026.</p>

<p>Over the same period, the proportion who said they never review their pension nearly halved, falling from 21% to 11%. Among active members, 68% said that they had checked their pension balance or current value over the past 12 months, up from 59%.</p>

<p>The findings also showed that members were paying more attention to the wider aspects of retirement planning. Just over half of active members, 51%, had looked at the income their pension might provide, up from 44%. The proportion who had changed their target retirement age increased from 11% to 16%, while 30% had reviewed their retirement options or ways of accessing their savings, up from 24%. TPT&rsquo;s research also found that 24% of active members had looked into their investments or investment choices, up from 16%.</p>

<div><strong>Retirement decisions remain unresolved</strong></div>

<div>Among members aged 50 and over, uncertainty was particularly evident. Almost half, 47%, did not know whether they planned to take a lump sum. Of those who did not expect to take their entire pension in one go, just over half, 52%, were uncertain what they would do with the remainder or majority of their savings.</div>

<p>Only 22% of members aged 50+ either already pay for professional financial advice or plan to do so when making retirement decisions. This leaves a significant proportion who may benefit from more structured support.</p>

<p>Guided retirement products can provide a clearer pathway for turning pension savings into income, and this research suggests that support amongst savers is growing. TPT&rsquo;s 2026 research found that support for guided retirement among this cohort substantially outweighed opposition among its members, at 35% compared with 4%. To address this, TPT offers a managed income-for-life product, which provides a streamlined path from pension saving to income withdrawal, enabling members to convert their pension pots into a sustainable, inflation-linked income for life.  </p>

<p><strong>Philip Smith, DC Director at TPT Retirement Solutions, said:</strong> &ldquo;It is encouraging to see more members checking their pensions and exploring the options available to them. However, engagement is only the first step and does not, by itself, lead to better retirement outcomes. While members are paying greater attention to their pensions, many remain uncertain about how they will use their savings at retirement.</p>

<p>&ldquo;The research underlines the need for the industry to make retirement pathways simpler, both enabling informed, confident decisions where members are able, and putting in place good value default solutions where they do not engage. There is a clear opportunity to turn growing awareness into better retirement outcomes through clearer information, more effective support and innovative solutions that guide members through the choices they face at retirement.&rdquo;</p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/pension-engagement-rising-but-retirement-decisions-difficult-27018.htm</link>
<pubDate>Tue, 4 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Smaller Pensions Continue To Seize Buy in Opportunities</title>
		<description><![CDATA[<div>The comments follow the successful completion of a buy-in for a client in the transport sector by Quantum&rsquo;s risk transfer team. The &pound;9.7m transaction, which covers 100 members, was completed with Aviva.</div>

<div> </div>

<div>Quantum Advisory,acted as lead transaction adviser in the process, with legal advice from Stephenson Harwood. The independent Chair of Trustees was Lynne Stewart-Brindle, Deputy Chair at PAN Trustees.</div>

<div> </div>

<div>The transaction forms part of the Scheme&rsquo;s long-term strategy, providing increased security for members&rsquo; benefits while helping the Scheme trustees and sponsoring employer meet their endgame objectives.</div>

<div> </div>

<div><strong>Chris Mason, Principal Consultant at Quantum Advisory, said:</strong> &ldquo;The market remains highly competitive and we continue to see attractive opportunities for smaller schemes that are well prepared and have a clear strategy. There can sometimes be a perception that insurers are focused solely on the largest transactions, but our experience is that smaller schemes can achieve excellent outcomes when they enter the market in the right way.</div>

<div> </div>

<div>&ldquo;Preparation is key. Trustees who understand their objectives, have high-quality data and take advice in the process from specialists in small scheme deals, like Quantum Advisory, are often in a much stronger position to secure a successful transaction. This was certainly the case for our client in the transport sector who wanted to buy-in and had been working towards it. With the right approach and support, smaller schemes like our client&rsquo;s can achieve their long-term goals.&rdquo;</div>

<div> </div>

<div>The latest transaction is one of a number of buy-ins on which Quantum Advisory has advised, reflecting the firm&rsquo;s continued focus on supporting small and medium-sized pension schemes through their full de-risking and endgame journey.</div>

<div> </div>

<div><strong>Chris Mason added:</strong> &ldquo;Smaller schemes are increasingly moving towards endgame risk transfer transactions. &ldquo;Every scheme is different, but what remains consistent is the importance of planning ahead. Risk transfer is not simply about completing a transaction; it&rsquo;s about ensuring trustees are in the strongest possible position to make informed decisions at the right time. We&rsquo;re continuing to see encouraging opportunities for smaller schemes and expect that to remain the case as the market develops.&rdquo;</div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/smaller-pensions-continue-to-seize-buy-in-opportunities-27020.htm</link>
<pubDate>Tue, 4 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Average Claim For Subsidence Hits Record  20k In Hot Weather</title>
		<description><![CDATA[<div>The figures follow the warmest spring on record in England and Wales, and the third warmest across the UK, with prolonged dry weather increasing the risk of ground movement and damage to properties. </div>

<div> </div>

<div><strong>Advice for homeowners</strong></div>

<div>Subsidence occurs when the ground beneath a property sinks, causing the building&rsquo;s foundations to move. It is most commonly caused by soil losing moisture and shrinking, often during prolonged dry weather. Trees and large shrubs can also contribute by drawing water from the ground.</div>

<div> </div>

<div><strong>Homeowners concerned about subsidence should be aware of several warning signs: </strong></div>

<div><em>Subsidence-related cracks often appear suddenly, rather than developing gradually through normal wear and tear.</em></div>

<div><em>Keep an eye out for cracks that are wider than 3mm &ndash; about the thickness of a &pound;1 coin &ndash; as these may need further investigation.</em></div>

<div><em>Be particularly aware of diagonal cracks, especially if they are wider at the top than at the bottom.</em></div>

<div><em>Check whether cracks appear both inside and outside your home, as this can be a sign of a more serious issue.</em></div>

<div><em>Watch for doors and windows that suddenly become difficult to open or close.</em></div>

<div><em>Look out for wallpaper that starts to wrinkle, ripple or tear without an obvious cause.</em></div>

<div><em>If you're concerned about possible subsidence, seek professional advice and contact your insurer.</em></div>

<div> </div>

<div><strong>Average home insurance payout reaches new high </strong></div>

<div>Between April and June 2026, the average payout across all types of home insurance claims went above &pound;7,000 for the first time &ndash; having only broken the &pound;6,000 mark in the same period last year. The cost of damage caused by extreme weather continued to rise. The average claim for damage to people&rsquo;s homes and possessions from flooding, storms and burst pipes reached &pound;8,548 in the second quarter of 2026, up 12% on the same period in 2025. The average claim for theft also reached a record &pound;5,100 this quarter, up 27% year-on-year.</div>

<div> </div>

<div><strong>Chris Bose, Director of General Insurance Policy at the ABI, said: </strong>&quot;The growing cost of subsidence and weather-related damage is a reminder of why improving the resilience of our homes matters. While insurers continue to be there for customers when they need them most &ndash; providing financial protection and support &ndash; reducing future losses demands a coordinated effort from homeowners, industry and government. </div>

<div> </div>

<div>&ldquo;Simple steps can make a real difference. For new homes, building deep foundations can reduce the risk of subsidence. For older properties, maintaining nearby trees and drains and fixing leaking pipes can prevent problems from developing. As extreme weather becomes more common, protecting homes will be increasingly important to help communities better withstand its impacts.&rdquo;</div>

<div> </div>

<div><strong>Household property premiums</strong></div>

<div>The average combined home insurance premium was &pound;383 between April and June 2026, 2% (&pound;9) lower than a year earlier. While premiums increased by &pound;8 compared to the previous quarter, this was the first quarterly rise since the start of 2025.</div>

<div> </div>

<div>The average buildings-only premium was &pound;309, 5% (&pound;16) lower than a year earlier, and up &pound;4 compared to Q1 2026.</div>

<div>Contents-only policies averaged &pound;118, down 9% (&pound;11) year-on-year, while increasing by &pound;1 compared to the previous quarter.</div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/average-claim-for-subsidence-hits-record--20k-in-hot-weather-27014.htm</link>
<pubDate>Mon, 3 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Iht Impacting Higher Proportion Of Families</title>
		<description><![CDATA[<p>Total Inheritance Tax liabilities were &pound;7.03 billion for 2023/24 compared with &pound;6.70bn in 2022/23. The latest figures come as the Office for Budget Responsibility forecasts that the number of estates paying Inheritance Tax will rise to nearly 10% of deaths by 2029/30 as frozen thresholds and recent policy changes bring more families within the scope of the tax and raise a projected &pound;13.7bn by 2029/30.</p>

<p><strong>Simon Martin, Head of UK Technical Services at Utmost, a leading global provider of insurance-based wealth solutions, commented: </strong>&ldquo;The inexorable rise in the proportion of estates facing Inheritance Tax shows how a tax once associated primarily with only the very wealthy is now affecting a growing proportion of families as frozen thresholds continue to bite.</p>

<p>&ldquo;This direction of travel looks set to accelerate as recent reforms to the Inheritance Tax regime begin to take effect. Measures such as the inclusion of pension benefits in estate calculations from April 2027, for example, will further increase the number of families facing a potential liability.</p>

<p>&ldquo;Families should not wait until these changes take effect, as the range of options available to manage a potential liability may narrow over time. It underlines the importance of professional financial advice in helping families understand their individual situation and pass on their wealth to loved ones as efficiently as possible.&quot;</p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/iht-impacting-higher-proportion-of-families-27008.htm</link>
<pubDate>Mon, 3 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Forces Driving The Institutionalisation Of Wealth Management</title>
		<description><![CDATA[<p><strong>By Aman Hanspal, Director, WTW</strong></p>

<p>For most clients, wealth must do many things, sometimes more than one at the same time. It needs to preserve capital, support growth, provide income, maintain liquidity, fund lifestyle choices and help plan for succession and legacy. These objectives often overlap and evolve over time. No single product or structure can address them all. That complexity is what makes the institutionalisation of wealth management both important and less predictable than similar shifts elsewhere in the industry.</p>

<p>Wealth combines multiple goals, long time horizons and emotional considerations. Even so, the direction of travel is becoming clearer. A handful of forces are reshaping how wealth firms are built, how portfolios are governed and how outcomes are delivered.</p>

<div><strong>Structural pressures are changing the economics of wealth</strong></div>

<div>Consolidation is one of the most visible signs of this shift. Across the wealth industry, margins are under pressure with profit as a share of AUM already lower by c.19% since 2018 and set to fall further. Meanwhile, regulatory, compliance and operational demands continue to rise. Technology has become a central cost driver, with wealth managers typically investing around 5&ndash;10% of revenue in IT. For the largest firms, this translates into multi-billion-dollar annual technology budgets, with global wealth management IT spending reaching approximately $54 billion in 2023 and continuing to grow. In that environment, scale has become less about advantage and more about keeping up. Larger platforms are better able to invest in technology, data infrastructure and regulatory change. They can spread costs across broader client bases and often bring more of the advisory value chain in house. This has accelerated consolidation as firms look to build operating models that are more resilient and sustainable, with PwC estimating that around 16% of asset and wealth management firms could be bought or closed by 2027 as business model pressures intensify. Consolidation is also evolving beyond traditional mergers. Asset managers, insurers, wealth firms and technology providers are increasingly working together through partnerships, acquisitions and distribution-led strategies. As distribution becomes more critical, the boundaries between these sectors are becoming less defined.</div>

<div> </div>

<div><strong>Professionalisation is raising the bar on governance</strong></div>

<div>Alongside consolidation sits a broader push towards professionalisation. Multi-family offices offer a clear example. Their growth reflects a shift towards more formal governance and investment processes, with defined committees, multi-asset frameworks and greater exposure to private markets and direct investments becoming more common. At the same time, building a fully institutional-grade platform internally is expensive and complex. For many wealth firms, outsourcing in some way, shape or form has become a practical alternative. OCIO, co-manufacturing and extension of staff investment models all provide different variations for wealth firms to access institutional-quality portfolio construction, reporting and infrastructure in a cost effective, scaled way without the need to replicate the entire function in-house. In many cases, this reflects a conscious choice to strengthen investment and financial outcomes while allowing internal teams to focus on advice, planning and crucially, client relationships.</div>

<div> </div>

<div><strong>Operating models are being rebuilt from the inside</strong></div>

<div>Technology is no longer a support function in wealth management; it is becoming the key determinant of scalability and competitiveness. Many wealth firms are reworking legacy systems that have become fragmented over time, particularly as they have consolidated smaller firms through acquisitions but haven&rsquo;t fully integrated them. Disconnected front, middle and back-office processes are giving way to more integrated platforms designed to improve efficiency and decision-making. Technology is central to this transition. Adoption is already widespread, with most firms scaling AI across multiple use cases to improve efficiency, insight and decision making. Further, Alpha FMC report that 47%&ndash;77% of firms are using AI to undertake cost optimisation initiatives, reinforcing that operating model transformation is now a core industry-wide priority rather than an incremental change. Research from the <a href="https://www.thinkingaheadinstitute.org/research-papers/tai-global-wealth-study-2025/">Thinking Ahead Institute&rsquo;s Global Wealth Study 2025</a> highlights the challenge this creates. Meeting evolving client expectations remains the top priority for wealth managers, closely followed by the need to expand services, improve efficiency and keep pace with technology, all while scaling operations in a tougher environment (Figure 1).</div>

<p><strong>Figure 1: Top business priorities (2-3 years) of wealth managers</strong></p>

<p><img alt="" src="https://www.actuarialpost.co.uk/images/pic_WTW Wealth0308261.jpg" style="height:333px; width:600px" /></p>

<p><span style="font-size:11px"><em>Source: Thinking Ahead Institute, Global Wealth Study 2025</em></span></p>

<div><strong>Finding balance as the wealth management industry evolves</strong></div>

<div>One result of these forces has been the rise of larger, multi-asset and multi-channel platforms. At the same time, the market is not converging on a single model. Instead, it is polarising. Large, integrated firms are building scale and breadth, while specialist boutiques compete through focused expertise, clearly defined propositions and strong relationships. Institutionalisation should not be viewed in isolation. It interacts closely with professionalisation and personalisation. While institutional frameworks bring discipline and resilience, long-term success still depends on delivering outcomes that feel relevant to individual clients. The challenge for wealth firms is to combine institutional standards with personal judgement and flexibility. For that reason, institutionalisation is best seen not as a one-off transition, but as an ongoing evolution that will continue to shape who succeeds as the industry evolves ever more rapidly.</div>

<p> </p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/forces-driving-the-institutionalisation-of-wealth-management-27013.htm</link>
<pubDate>Mon, 3 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Aviva Completes  300m Buy in With Elementis Group Pension</title>
		<description><![CDATA[<div>The deal was completed in May 2026. Aon acted as lead adviser to the Trustee, with Squire Patton Boggs (UK) LLP providing legal advice. Aviva&rsquo;s legal advice was provided in-house.  It included a price lock, enabling the Trustee to sell down credit fund holdings and transition into the premium payment portfolio, helping to minimise mismatch risk and support pricing certainty throughout the process.</div>

<div> </div>

<div><strong>Sean Rooney, Senior BPA Deal Manager at Aviva, said:</strong> &ldquo;Completing this transaction with the Elementis Group Pension Scheme is a strong example of what can be achieved through close collaboration between parties and clear objectives.</div>

<div> </div>

<div>Aviva has significant post-transaction expertise, having completed more than 650 data cleansing exercises as part of the transition to buyout or long-term buy-in.  As part of this transaction, the Trustee has the option to draw on Aviva&rsquo;s expertise, alongside our specialist partners, to support completion of their data cleansing and verification activities. This provides certainty to the Scheme and its sponsor that, regardless of any scheme administration constraints, they can always rely on Aviva to ensure their preferred timescales for data cleanse are met, providing greater flexibility over the timing of any potential future buyout.&rdquo;</div>

<div> </div>

<div><strong>Brian Taylorson, Chairman of the Trustee Board of the Elementis Group Pension Scheme, said:</strong> &ldquo;We are delighted in our selection of Aviva as our insurance partner for securing fully the defined benefits of our members and their dependents. Aviva has a strong brand and rich heritage similar to Elementis whose own history goes back to 1844. This deal would not have been possible without the full support of our sponsor, Elementis plc1, which was and remains strongly collaborative throughout this process.</div>

<div> </div>

<div><strong>Wai Wong, Secretary of the Elementis Group Pension Scheme, said:</strong> &ldquo;Even with extensive planning and preparation, we had to overcome a number of challenges in our journey but our risk transfer advisory team at Aon were excellent and methodically guided the Trustees through every step in the process, supported by all of the Scheme's key advisers and Aptia as Scheme Administrator. Our focus now turns to the data validation phase and a comprehensive plan and strong project management will ensure we deliver for all our stakeholders.&rdquo;</div>

<div> </div>

<div><strong>Leah Evans, Partner at Aon, added: </strong>&ldquo;The unusual liability profile of the Scheme required in-depth considerations of scheme experience and cashflow profiles in order to complete a successful transaction. We worked closely with the Trustee and Aviva to develop solutions both for the initial transaction and to support the Trustees in the next stage of their journey. The Trustees&rsquo; strong governance structure and engagement throughout the project, as well as the support by the sponsor, allowed for efficient decision making and was key to achieving a good outcome for the Scheme and its members.&rdquo;</div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/aviva-completes--300m-buy-in-with-elementis-group-pension-27010.htm</link>
<pubDate>Mon, 3 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Ppi Publish Their Pensions Primer For 2026</title>
		<description><![CDATA[<p> As the UK pensions landscape continues to evolve, staying up to date has never been more important.</p>

<p>Whether you're new to pensions policy or looking for a reliable reference, the Primer provides a clear and accessible overview of how State and private pensions work, together with the latest policy and legislative developments. Fully updated to reflect the policy and legislative framework as at June 2026, it brings together everything you need to understand the UK's pensions landscape in one trusted resource.</p>

<p>The Primer is designed for policymakers, pension professionals, researchers, journalists, educators, students and anyone with an interest in retirement policy.</p>

<p><a href="https://www.actuarialpost.co.uk/downloads/cat_1/PPI-the-uk-pensions-primer-2026.pdf"><strong>PPI Pensions Primer 2026</strong></a></p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/ppi-publish-their-pensions-primer-for-2026-27009.htm</link>
<pubDate>Mon, 3 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Touching Records On Both Sides Of The Pond</title>
		<description><![CDATA[<p>The positive momentum looks likely to continue today, after the US President announced over the weekend that a planned major attack on Iran had been cancelled as a diplomatic solution to the conflict is sought. Oil fell by more than 5% to around $83 per barrel, which compares to approximately $72 pre-conflict, although investors may be circumspect since this playbook has been seen on many occasions over recent months.</p>

<p>In the meantime, the AI theme continued to play out as has become the theme for this earnings season, whereby companies are increasingly being punished if the continued and committed levels of AI spending are not obviously translating into physical earnings. On the other hand, if there are signs of progress the rewards can be meaningful, as evidenced by Microsoft last week which was followed by a 15% spike in the Amazon share price on Friday. The company beat expectations for revenue in the second quarter, boosted by the strength of its cloud-computing business which provided some comfort that AI spending can be at least partially rewarded. In contrast, Apple shares dropped by more than 7% despite topping estimates, with a weaker revenue outlook which the company blamed on a supply crunch in the components space in the midst of high AI demand.</p>

<p>The initial reaction to the new Federal Reserve Chair&rsquo;s tenure has not been positive. He has moved away from the forward guidance to which the market had become accustomed, while also admitting last week that there was no &ldquo;magic wand&rdquo; to hand in the battle against persistently high inflation. This translated into a loss of faith from investors which was most acutely reflected in the bond market, where the yield on the 10-year and 30-year Treasuries has risen to either side of 5%, which is becoming uncomfortable for the wider economy and borrowing levels in general.</p>

<p>Indeed, there will be further clues this week from both corporates and economic readings. On the company front, there will be updates which will shed light on the consumer (Walt Disney, McDonald&rsquo;s), industry (Caterpillar) and inevitably tech (Advanced Micro Devices), with other highlights being Pfizer numbers and the first post-IPO report from SpaceX. At the end of the week, the non-farm payrolls release is pencilled in at 87500 jobs having been added in July, up from 57000 the previous month, with unemployment ticking marginally higher to 4.3% from 4.2% previously.</p>

<p>In the meantime, the main indices have ploughed on regardless of the volley of worries which they have faced and in the year to date there have been gains of 9.2% for both the Dow Jones and Nasdaq, with the benchmark S&P500 having added 9.4% and each of the indices close to recent record highs.</p>

<p>The technology turbulence in particular has been a catalyst as the FTSE100 comes back into global investment fashion. Although the index has flirted with record highs and passed the number intraday over recent trading sessions, it has been unable to maintain the momentum later in the day and has yet to eclipse the record closing high set at the end of February. Even so, the attraction of the solidity and stability typical of most of its constituents has lifted the index to a gain of 9.4% in the year so far, although any gains at the open were limited by a lurch downwards from a core heavyweight.</p>

<p>There was a sense of palpable alert in the pharmaceutical sector after weekend reports that US giant Bristol-Myers Squibb and the FTSE100&rsquo;s second largest constituent, AstraZeneca were considering a major merger which could reach some $400 billion. The talks were not confirmed by either party, and it is questionable whether such a merger would be to the benefit of either party given some value destruction in such moves historically, even if there would be some obvious symmetry given their complementary expertise in oncology and cardiovascular. The opening reaction was a fall of around 7% in Astra shares, sending a clear signal that investors would potentially be strongly opposed to such a deal.&rdquo;</p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/touching-records-on-both-sides-of-the-pond-27011.htm</link>
<pubDate>Mon, 3 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Unlock Value Through Conversational Intelligence</title>
		<description><![CDATA[<div><iframe allow="accelerometer; autoplay; clipboard-write; encrypted-media; gyroscope; picture-in-picture; web-share" allowfullscreen="" frameborder="0" height="315" referrerpolicy="strict-origin-when-cross-origin" src="https://www.youtube.com/embed/_D6lUyr3Opk?si=pQ4hr7ClZ8FG_BaN" title="YouTube video player" width="340"></iframe></div>

<p> </p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/unlock-value-through-conversational-intelligence-27016.htm</link>
<pubDate>Mon, 3 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Tax Charges On Pension Savers Surge 22 </title>
		<description><![CDATA[<div><em>In 2024/25, 30,440 individuals reported pension contributions exceeding their personalised AA through SA. This has increased from 24,950 individuals in 2023/24 </em></div>

<div><em>The total value of contributions in excess of the AA that were reported via SA was &pound;672 million in 2024/25. This has increased from &pound;505 million in 2023/24 </em></div>

<p><strong>David Little, Partner in Financial Planning at wealth management firm Evelyn Partners, comments: </strong>&lsquo;These are quite striking increases of 22 per cent in the number of individuals reporting AA breaches and 33 per cent in the total value of contributions above the AA. The pensions annual allowance is the maximum amount of tax-free money you can contribute to your pensions each tax year, and the full AA is currently &pound;60,000, as it was in both these tax years.</p>

<p>'What is slightly surprising about the figures is that the AA was raised from &pound;40,000 to &pound;60,000 by then Chancellor Jeremy Hunt in April 2023 following his Spring Budget. That, you might have expected, would lead to a fall in breaches in the subsequent years as people had more leeway to make large annual pension contributions than they had enjoyed for nearly 10 years.</p>

<p>'It's not easy to pin down the cause, but a very plausible one is that more high earners were being surprised by the tapered annual allowance. Plausible because this was a period of elevated inflation when high earners could easily have lost track of the impact on pension contributions of increasing salaries and bonuses. Also many AA breaches occur within defined benefit schemes where it is harder for employees to keep track of how their pension is tested against the AA, and generous public sector pay deals during this period could have contributed.</p>

<p>&lsquo;However, there may be other factors at play than just the tapered annual allowance. Both years being compared had the &pound;60,000 standard allowance, and the increase could be due to earners exceeding the full AA by mistake as their earnings rose or as they sacrificed large bonuses into their pension. Increased employer contributions and unexpectedly high pension growth within defined-benefit schemes can also drive AA breaches.</p>

<p>'But the taper remains a particular trap because the headline &pound;60,000 allowance can give higher earners a false sense of security. Where threshold income exceeds &pound;200,000 and adjusted income exceeds &pound;260,000, the allowance is reduced by &pound;1 for every &pound;2 of additional adjusted income, potentially falling to just &pound;10,000.</p>

<p>'Adjusted income includes employer pension funding, so somebody may be caught even where their personal contributions appear relatively modest. Bonuses paid at the end of the tax year, variable earnings and contributions across several schemes make the final position difficult to predict until late in the tax year, by which time it&rsquo;s very difficult to unwind pension contributions made during the tax year. Also HMRC doesn&rsquo;t monitor these breaches in real time, it relies on self-reporting, which means some savers don&rsquo;t realise for two or three years that they&rsquo;ve been over-contributing, and then are faced with a big tax back-charge.</p>

<p>'The key is to plan before the tax year has ended rather than waiting for a pension statement or tax return to reveal the problem. Savers should obtain up-to-date pension input figures from every scheme, estimate their total income including bonuses and benefits, and check whether unused allowance can be carried forward from the previous three tax years. Defined-benefit members need particular care because the amount tested is the increase in the value of their promised pension, not simply what they have personally paid in.</p>

<p>'Where a charge on an AA breach is unavoidable, savers should establish whether Scheme Pays is available to allow the charge to be paid from their pension scheme, but they should not automatically stop pension saving simply to avoid a tax charge. Giving up valuable employer contributions, tax free growth inside the pension fund or defined-benefit accrual could leave them materially worse off in the long run. Sometimes paying the tax charge is the best option.</p>

<p>'What we are seeing here is evidence that pension taxation remains too complex for most people and even financially savvy earners can get caught out. It&rsquo;s striking how many high earners are completely unaware that their pension allowances are tapered until it&rsquo;s too late.' </p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/tax-charges-on-pension-savers-surge-22--27015.htm</link>
<pubDate>Mon, 3 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>The Life Moments Dashboards Will Matter Most</title>
		<description><![CDATA[<div>The webcast poll, conducted in June 2026 among UK trustees and pension scheme managers, found that 43% believe members will turn to dashboards at pivotal life events, while 40% expect usage to depend on prompts from communications. Only 13% anticipate regular, proactive use.</div>

<div> </div>

<div>The results suggest that dashboards, on their own, may not drive sustained behavioural change. Instead, they reinforce the need for communications strategies built around specific life stages, when members are most likely to act.</div>

<div> </div>

<div><strong>Geraldine Brassett, senior director in WTW&rsquo;s Pensions Outsourcing business, said:</strong> &ldquo;It&rsquo;s becoming clear that dashboards will be most powerful at moments that matter to members. Schemes should not assume that access alone will drive engagement. Targeted communications, aligned to life events, will be critical if dashboards are to translate into better decisions and outcomes.&rdquo;</div>

<div> </div>

<div>Beyond engagement, the research highlights a more immediate operational concern. Managing increased member enquiries was cited as the leading post-launch challenge by 39% of respondents. This reflects expectations that greater visibility of pension data will prompt a wave of questions from members seeking clarity on their benefits.</div>

<div> </div>

<div>Data quality also emerged as a key risk. More than a third (36%) of respondents identified accuracy as a primary concern, with a clear link between poor data and potential erosion of member trust. The findings underline the reputational stakes for schemes as dashboards bring legacy data issues into sharper focus.</div>

<div> </div>

<div>At the same time, there is broad optimism about the overall impact of dashboards. More than three quarters (76%) of those polled expect at least a moderate increase in engagement following launch. However, most believe this uplift will be concentrated among members who are already engaged, unless schemes invest in more proactive support.</div>

<div> </div>

<div>Taken together, the polling paints a balanced picture of opportunity and risk. Dashboards are widely seen as a catalyst for improved engagement, but not a complete solution. Their success is likely to depend on how effectively schemes manage the surrounding experience, from communications to administration and data readiness.</div>

<div> </div>

<div><strong>Brassett added:</strong> &ldquo;Dashboards represent a significant step forward in how members access their pension information. But the real test will be what happens next, how schemes respond to increased demand, how they maintain data quality, and how they support members in turning insight into action.&rdquo;</div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/the-life-moments-dashboards-will-matter-most-27012.htm</link>
<pubDate>Mon, 3 Aug 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Advice On Affects Of Wildfires In Suffolk And Across The Uk</title>
		<description><![CDATA[<div><strong>Louise Clark, General Insurance Policy Manager at the ABI, said: </strong>&ldquo;With a major incident declared in Suffolk, people are understandably concerned for themselves and their property. It&rsquo;s vital to put safety first and follow the advice of local authorities and emergency services. &ldquo;Supporting customers who have suffered damage from fires, including wildfires, is what insurance is there for. Our members are on hand to support affected customers, so if your property has been damaged, speak to your insurer as soon as possible. They will be able to offer help and advice on next steps.&rdquo; </div>

<div> </div>

<div><strong>If your home or property is in the affected area, the ABI advises: </strong></div>

<div><em>The most important thing is to stay safe. Monitor official warnings closely and follow guidance from the Fire and Rescue Service, Local Authority or other emergency services. </em></div>

<div><em>If your property has been affected, contact your insurer as soon as it is safe to do so. They will be able to explain the claims process, provide practical support and help you understand what assistance may be available under your policy. </em></div>

<div><em>Standard home insurance policies typically cover damage caused by fire, including wildfires, and your insurer can also offer support and advice to help you get back on your feet. This can include making emergency payments and helping to repair or rebuild damaged properties.  </em></div>

<div><em>Cover for items in your garden may vary. For example, some policies include cover for garden furniture, trees, hedges, lawns, and fences, while others do not. If you&rsquo;re not sure what&rsquo;s included in your policy, speak to your insurer who can help. </em></div>

<div><em>Most home insurance policies will also provide alternative accommodation where a property has been damaged and is no longer safe to live in. </em></div>

<div><em>If you are evacuated as a precaution and your property has not been damaged, temporary accommodation is typically arranged through the Local Authority.  If you&rsquo;re unsure exactly what is covered in your policy, check your documents or speak to your insurer.  If you do not have insurance, you will not be able to make a claim for damage to your property. However, anyone affected should contact their local authority or the Red Cross, which may be able to support following a fire. </em></div>

<div> </div>

<div><strong>If your business has been affected:  </strong></div>

<div><em>Contact your insurer or broker as soon as possible. </em></div>

<div><em>Depending on the circumstances and the cover in place, your insurer or broker may be able to provide support such as emergency payments, loss adjusters and assistance with repairs and reinstatement to help you recover as quickly as possible. </em></div>

<div><em>Many business insurance policies cover fire damage to insured buildings, stock, equipment and machinery, although cover will depend on the terms, limits and exclusions of the policy. </em></div>

<div><em>If you have business interruption insurance, it may cover loss of income and certain ongoing costs if your business is forced to close because of damage to insured premises. Some business interruption policies may also help cover the cost of temporary alternative premises while repairs are carried out. </em></div>

<div><em>Depending on your policy, some will also cover costs if your business cannot operate because of evacuation orders, road closures or restricted access to the area.  If you&rsquo;re not sure what is covered, check your policy or speak to your insurer or broker. </em></div>

<div> </div>

<div><strong>For homes and businesses that have been damaged: </strong></div>

<div><em>Speak to your insurer before carrying out significant clean-up or repair work unless immediate action is needed to protect people or prevent further damage. </em></div>

<div><em>Keep records of any damage, including photographs where possible, and retain receipts for emergency expenses or temporary measures.Unless they are a safety hazard, do not dispose of damaged items until your insurer has advised you.</em></div>

<div> </div>

<div>You can find more information and frequently asked questions on fire damage on the <a href="https://www.abi.org.uk/products-and-issues/choosing-the-right-insurance/home-insurance/fire/">ABI's website here.</a> </div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/advice-on-affects-of-wildfires-in-suffolk-and-across-the-uk-27003.htm</link>
<pubDate>Fri, 31 Jul 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>What Does Europes Record Wildfire Season Signal To Insurers</title>
		<description><![CDATA[<div><strong>By Firas Saleh, Director of Product Management, Moody's</strong></div>

<div> </div>

<div><strong>France</strong></div>

<div>In France, the Gironde and Biscarrosse wildfires, which ignited on July 22 in the neighboring Gironde and Landes departments in coastal southwest France, have burned more than 45,000 hectares and are not yet contained. The French authorities say the outbreak surpasses the historic 1949 Landes de Gascogne fire. Nationally, more than 115,000 hectares have burned in France so far this summer, nearly double the 2022 total, with around 240 homes destroyed.</div>

<div> </div>

<div>Roughly a quarter of a million people were evacuated, including the entire Cap Ferret peninsula 30 miles southwest of Bordeaux, which was cleared by land and by sea. French authorities described the evacuations as the country's largest since the Second World War. Contingency planning extended to Bordeaux itself, France&rsquo;s sixth-largest city, with 1.37 million people living in the wider metropolitan area.</div>

<div> </div>

<div><strong>Spain and Italy</strong></div>

<div>In Spain, a national emergency now spans four provinces. The Burgohondo fire has burned approximately 77,000 hectares across an area between &Aacute;vila, Madrid and Toledo, the largest wildfire in the country&rsquo;s recorded history. Three separate fires west of Madrid have merged into a single 28,000-hectare complex, destroying at least 43 homes and damaging nearly 300 more in initial counts.</div>

<div> </div>

<div>More than 115,000 people have been evacuated across Spain, and in Italy, crews in Sicily have carried out more than 1,400 firefighting interventions since mid-July. With a further heatwave forecast this week and damage surveys only beginning, reliable loss estimates remain weeks away. What can be assessed now is what the event reveals about the changing nature of this peril.</div>

<div> </div>

<div><strong>A peril on a new trajectory</strong></div>

<div>For much of the insurance industry's history, wildfire was treated as a regional hazard, severe in specific geographies, but episodic in its contribution to global catastrophe losses. The past decade has rewritten the record.</div>

<div> </div>

<div>From the 2017 and 2018 California fire seasons, the 2019&ndash;20 Australian bushfires, the 2023 Maui fires and, most recently, the January 2025 Los Angeles fires, with reported insured losses in the tens of billions of dollars, all have established wildfire as a recurring driver of major loss years rather than an occasional outlier. This July indicates that the European dimension of the peril now warrants the same analytical attention, and three features of the event show why.</div>

<div> </div>

<div><strong>Three features from these events that stand out for the insurance industry</strong></div>

<div><strong>First, simultaneity.</strong> This is not a French or Spanish event. It is a European event: a synoptic weather pattern driving correlated fire activity across France, Spain and Portugal simultaneously, with Sicily also active within the same window. The sequencing is instructive: in early July, Spain and Italy sent firefighting support to Portugal, and within three weeks, both were managing record fires at home. Just as telling, the correlation extends to response capacity. French fire officials note that its northern crews can no longer reinforce the south of the country as they once did, because the north itself is now at risk. Suppression capacity, the quiet assumption that has historically capped European fire losses, is being stretched thin at precisely the moment fire weather is intensifying. Correlated hazard plus correlated response strain is how tail events are made. Primary insurers are experiencing these events as separate national losses, but reinsurers experience them as an accumulating regional position, stacking property, business interruption, agricultural and forestry losses across borders.</div>

<div> </div>

<div><strong>Second, the loss channels are multiplying.</strong> Burned structures are only the visible layer of a modern wildfire loss. In Gironde, France, over 13,000 businesses have been evacuated, such as in the coastal resort of Lacanau. This has resulted in business interruption, all with no physical damage. French insurers are covering costs of temporary accommodation for evacuees whose homes still stand. Bordeaux wine producers have raised concerns about potential smoke effects on the 2026 vintage; an agricultural and brand impact that requires no direct contact with flame. Highways were closed, and rail service south of Bordeaux was suspended, a direct drag on regional output that will never appear in a property claims file. Travel insurance recoveries may hinge on whether formal evacuation orders were in force, a policy-wording detail with material consequences.</div>

<div> </div>

<div>In &Aacute;vila, Spain, fire moved through livestock farms and agricultural infrastructure, segments that are often underinsured. And nearly 2,000 residents were evacuated from care facilities across the Madrid and &Aacute;vila regions and coastal France, introducing duty-of-care and liability considerations alongside property covers. Wildfire loss has become a network phenomenon; models and products calibrated to account for destroyed buildings alone risk systematically understating it.</div>

<div> </div>

<div><strong>Third, fire behavior is testing the limits of historical experience.</strong> Responders in Gironde, France encountered pyrocumulonimbus clouds, thunderstorms generated by a fire&rsquo;s own heat, while officials described fire spread as erratic, multi-directional and self-sustaining. According to M&eacute;t&eacute;o-France, soil moisture in France has fallen to record lows, and separate fires in Spain merged into single complexes. These are signatures of a fire regime that the historical record only partially contains, and a catastrophe model calibrated in the past that may miss the tail that matters. Forward-looking, climate-conditioned views of wildfire risk, fuel state, vegetation stress, and the expanding wildland-urban interface along coastlines and exurbs are becoming a practical necessity rather than a refinement.</div>

<div> </div>

<div><strong>An emerging infrastructure peril</strong></div>

<div>Among the less-reported aspects of this event is its impact on critical infrastructure. NASA evacuated its Madrid Deep Space Communications Complex located in Robledo de Chavela, Spain, and a biomass processing facility in Portugal was destroyed. Disruption to infrastructure, specifically during the peak season in this tourism-oriented region, can have a rapid impact on the tourism industry. Wildfire increasingly functions as an infrastructure peril, in which contingent business interruption from disabled lifelines, water, power, and transport can extend well beyond the burn scar. Exposure assessment framed only around structures at the wildland-urban interface will not capture this dimension.</div>

<div> </div>

<div><strong>The protection gap and the public response</strong></div>

<div>According to the European Insurance and Occupational Pensions Authority (EIOPA), only about a quarter of European natural catastrophe losses have historically been insured, with the remainder being borne by households, businesses and public finances.</div>

<div> </div>

<div>Governments are already responding: the Madrid regional government announced a &euro;30 million housing and recovery package, and France extended claims-filing deadlines to the end of August while opening partial unemployment support to affected businesses.</div>

<div> </div>

<div>The gap underscores both the societal role of risk transfer and the case for product development, non-damage business interruption, parametric structures, and agricultural and forestry covers, alongside public-private collaboration on prevention and resilience.</div>

<div> </div>

<div><strong>Considerations for the market</strong></div>

<div>Pricing pressure was visible before this event, with home insurance rates in France&rsquo;s Nouvelle-Aquitaine region reported to have risen by roughly 20% this year. Experience in other markets, notably California, suggests that broad repricing and withdrawal can lead to availability strains over time. The alternatives include granular, risk-reflective pricing; underwriting that recognizes mitigation at the property and community level; and risk signals that inform development decisions at the wildland-urban interface before exposure is built.</div>

<div> </div>

<div>A final consideration concerns communication. With fires uncontained and surveys incomplete, loss development will take weeks rather than days. Credible analysis in this period means being explicit about what is known, what is not, and which factors - final burned area, structure counts, the duration of business disruption, and claims volumes - will ultimately determine the outcome.</div>

<div> </div>

<div><strong>What to watch from here</strong></div>

<div>The trajectory of this event will become clearer over the coming weeks: containment progress against this week's forecast heat, final burned-area and structure counts, the duration of business and transport disruption, and claims volumes as filings come in through the extended end-of-August deadline in France. Those indicators, more than any early estimate, will determine the eventual economic and insured outcome, and they will shape how the market prices and manages a peril that this July has placed firmly on the European agenda.</div>

<div> </div>

<div><a href="https://www.actuarialpost.co.uk/downloads/cat_1/Moodys - Fire - 2026.pdf"><strong>Moody's Impact of European Wildfires Report</strong></a></div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/what-does-europes-record-wildfire-season-signal-to-insurers-27005.htm</link>
<pubDate>Fri, 31 Jul 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Scale Is A Clear Differentiator In Workplace Pensions</title>
		<description><![CDATA[<p>Financial advisers recognise the importance of scale as the workplace pensions market consolidates, but providers will need to do more to demonstrate how it translates into better outcomes for members, according to new research&sup1; from People's Pension&sup2;.</p>

<p>More than half (51%) of advisers believe scale will become an increasingly important differentiator between workplace pension providers, versus just 8% who disagree. At the same time, only 11% believe smaller providers can continue to compete effectively with larger schemes, underlining the increasingly important role advisers expect scale to play as the market evolves.</p>

<p>However, advisers are looking beyond size alone when assessing DC providers. A quarter (25%) believe scale delivers important operational advantages but does not necessarily translate into better retirement outcomes, while only 9% believe increasing provider scale directly improves member outcomes.</p>

<p>People&rsquo;s Pension also found that the majority (58%) of advisers say member outcomes and support matter more than cost alone, versus a small minority (12%) who disagree. The findings suggest advisers increasingly expect providers to demonstrate how scale translates into tangible benefits for members.</p>

<p>The research comes as the Pension Schemes Act accelerates the next phase of workplace pension reform, with greater emphasis on consolidation, value for money and improving member outcomes. Against that backdrop, advisers recognise the benefits that larger providers bring, but need more evidence they are using their scale to deliver consistently better member outcomes.</p>

<p><strong>Stuart Reid, Distribution Director for People's Pension, said: </strong>&quot;It's encouraging to see advisers recognising that scale is becoming increasingly important as schemes consolidate and employers look for providers with the governance, resilience and investment capability to deliver over the long term.</p>

<p>&quot;What stands out from these findings is that whilst advisers clearly see the value of scale, they're not yet convinced that it automatically translates into better outcomes for members. That reinforces the importance of providers demonstrating the value scale can create in practice. We're committed to continuing to improve retirement outcomes for members, and I believe that as the market sees more examples of how scale is being put to work, advisers will become increasingly confident in the benefits it can deliver.&quot;</p>

<p>&quot;Ultimately, scale should never be judged in isolation. Its real value lies in what it enables providers to deliver for employers and members, and that's where the market is increasingly focusing its attention.&quot;</p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/scale-is-a-clear-differentiator-in-workplace-pensions-27004.htm</link>
<pubDate>Fri, 31 Jul 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Tpr Accepting Applications For Multi employer Cdc Schemes</title>
		<description><![CDATA[<p>Applications for multi-employer CDC schemes are now open for multiple, unconnected employers, expanding access beyond the single-employer CDC framework introduced in 2021.</p>

<p>CDC schemes pool members' contributions and investments, allowing risks and rewards to be shared collectively. They provide a target retirement income for life, rather than relying solely on individual pension pots. Benefits can be adjusted up or down depending on investment performance and the scheme's funding position.</p>

<p>The new framework gives employers and members an alternative between traditional defined benefit (DB) and defined contribution (DC) pension arrangements.</p>

<p>Any organisation wishing to establish a CDC scheme must be authorised by The Pensions Regulator (TPR) before operating. Authorisation provides important protections for members and helps ensure high standards of governance and administration. TPR has today published new and updated guidance to help prospective schemes understand the authorisation process, regulatory requirements and what will be expected of them as authorised schemes.</p>

<p>This includes <a href="https://www.thepensionsregulator.gov.uk/document-library/scheme-management-detailed-guidance/collective-defined-contribution-schemes">new guidance</a> on promotion and marketing and sectionalisation of schemes, and updates to existing systems and processes and fees guidance.</p>

<p>Organisations considering establishing a CDC scheme are encouraged to engage early with TPR through its supervision teams and Innovation Support Service to support a smooth authorisation process and avoid surprises as new provision is developed: <a href="https://www.thepensionsregulator.gov.uk/en/get-support-with-pensions-innovation">Get support with pensions innovation.</a></p>

<p><strong>Richard Knox, Executive Director of Strategy, Policy & Analysis at The Pensions Regulator, said: </strong>&quot;We are delighted to open applications for multi-employer CDC schemes, marking an important milestone in the development of the UK's pensions system. At The Pensions Regulator, we want everyone to be able to achieve a sustainable income in retirement, and multi-employer CDC schemes could become an important part of the pensions landscape to support this goal. We also want a no-surprises approach as new innovations like CDC come to market. That is why we encourage anyone considering establishing a scheme to engage with us early so we can support the process.&rdquo;</p>

<p> </p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/tpr-accepting-applications-for-multi-employer-cdc-schemes-27007.htm</link>
<pubDate>Fri, 31 Jul 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Comment On Cdc Authorisation From Tpr</title>
		<description><![CDATA[<div>It marks the point at which CDC begins to be accessible to the mass market of employers and their people, representing one of the most significant innovations in UK pension provision for many years. It&rsquo;s also an important moment for TPR, whose role in scrutinising and authorising schemes will be critical in building confidence throughout the industry as the market develops. Reaching this stage has required substantial collaboration across government, regulators, providers and advisers, and it&rsquo;s important to recognise the work that has gone into creating a robust framework for these new schemes.</div>

<div> </div>

<div>&ldquo;CDC can play a meaningful role in addressing the significant challenge of retirement adequacy. By pooling longevity risk and investing collectively, it offers the prospect of higher retirement incomes than other DC alternatives, alongside a simpler member experience with fewer complex decisions at retirement. The trade-off for this is typically less flexibility, or the ability to pass on a legacy if you die.</div>

<div> </div>

<div>&ldquo;As employers look for ways to help improve retirement outcomes for their workforce, CDC represents an attractive new option. Having worked closely with policymakers and regulators, and supported the development of a number of emerging CDC propositions, we have seen first-hand the level of innovation and commitment being invested in bringing these schemes to market.</div>

<div> </div>

<div>&ldquo;While authorisation is an important step, the long-term success of CDC will ultimately depend on how schemes are designed, governed and operated in practice. The experience of the first generation of authorised schemes will be critical in building confidence across the market and demonstrating how multi-employer CDC can deliver in practice for both employers and members. We are excited to be part of this with our clients as CDC moves towards becoming an established part of the UK pensions landscape.&rdquo;</div>

<p> </p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/comment-on-cdc-authorisation-from-tpr-27006.htm</link>
<pubDate>Fri, 31 Jul 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Royal London Secure  208m Bpa Transaction With Hickson Group</title>
		<description><![CDATA[<div>Royal London, the UK&rsquo;s largest customer owned life, pensions and investment provider, has completed a c.&pound;208 million bulk purchase annuity (BPA) transaction with the trustees of the Hickson UK Group Pension Scheme (&ldquo;the Scheme&rdquo;). The transaction completed in June.</div>

<div> </div>

<div>The transaction secures the benefits of more than 1,250 members and is Royal London's third-largest external BPA transaction to date. Including internal BPA transactions, it ranks as the firm's sixth largest overall, further strengthening its position in the mid-sized segment of the market.</div>

<div> </div>

<div>The trustees, chaired by BESTrustees Limted were advised by Barnett Waddingham as risk transfer adviser, with Pinsent Masons providing legal advice and Mercer providing investment advice. Royal London was advised by Mayer Brown. This transaction builds on a long-standing relationship with Royal London Asset Management (RLAM). </div>

<div> </div>

<div><strong>Mark Sharkey, BPA Origination Lead at Royal London, said: </strong>&ldquo;This transaction with the trustees of the Hickson UK Group Pension Scheme demonstrates our growing track record in the mid-market sized BPA market, with our sixth transaction over &pound;200m. The trustees&rsquo; long-standing relationship with RLAM established a strong starting point for us to really understand their priorities and develop a tailored BPA solution. That extended to moving at pace to meet the Scheme&rsquo;s evolving needs at the point of exclusivity.&rdquo; </div>

<div> </div>

<div><strong>Nikhil Patel, Head of Bulk Annuities at Barnett Waddingham, part of Howden, said: </strong>&ldquo;In such a competitive space in the market, the transaction led to some strong proposals for the trustees to consider. Ultimately, the trustees were able to secure a deal that met the needs of the Scheme, sponsor and members, including insuring the non-standard features of the benefits. It was a pleasure working with the trustees, Royal London and the Scheme&rsquo;s other advisers on the first of several significant transactions Barnett Waddingham expect to complete in 2026.&rdquo;         </div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/royal-london-secure--208m-bpa-transaction-with-hickson-group-26995.htm</link>
<pubDate>Thu, 30 Jul 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Ms Amlin Appoints Laura Hobern As Chief Actuary</title>
		<description><![CDATA[<p>Reporting to Chief Financial Officer, Jessie Burrows, Laura will oversee all actuarial operations, including reserving and pricing, ensuring actuarial insight supports strategic decision-making, financial resilience and sustainable growth.</p>

<p>Laura joins MS Amlin from consultancy firm LCP, where she is a Partner advising insurance boards and executive teams on actuarial, risk and strategy.</p>

<p>She brings more than 20 years of industry experience and has previously held senior actuarial positions at Milliman, Hiscox and Brit Insurance. She began her career at Swiss Re.</p>

<p>Laura serves on the Institute and Faculty of Actuaries' General Insurance Board and is Deputy Chair of the London Market Actuaries' Group.</p>

<p>MS Amlin's current Chief Actuary, Paul Lucas, has been appointed to the newly created role of Underwriting Portfolio Director, reporting to Martin Burke, the Chief Underwriting Officer. In the role, Paul will bring together insight from across the business to help shape MS Amlin's underwriting appetite, portfolio strategy and capital allocation decisions.</p>

<p><strong>Jessie Burrows, Chief Financial Officer at MS Amlin, said:</strong> &quot;We&rsquo;re delighted to welcome Laura to the team and to appoint Paul to the new role of Portfolio Underwriting Director.  Laura brings a strong combination of actuarial expertise, commercial judgement and leadership experience. Having advised boards and executive teams across the insurance market, she understands how actuarial insight can support better business decisions and stronger performance. As market conditions continue to evolve, both Laura and Paul will play an important role in helping us balance growth with discipline, ensuring we continue to make informed decisions that support financial resilience and sustainable profitability.&rdquo;</p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/ms-amlin-appoints-laura-hobern-as-chief-actuary-26994.htm</link>
<pubDate>Thu, 30 Jul 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Getting The Balance Right On Ssas Transfers</title>
		<description><![CDATA[<div><strong>By James Jones-Tinsley, Self-Invested Pensions Technical Specialist, Barnett Waddingham</strong></div>

<div> </div>

<div>However, any new measures should be targeted at genuine indicators of risk and should not create unnecessary barriers for legitimate pension savers seeking to transfer into well-governed SSAS arrangements.</div>

<div> </div>

<div>In our response to the DWP's consultation on proposed changes to the Occupational and Personal Pension Schemes (Conditions for Transfers) Regulations 2021, we support stronger protections against fraud while highlighting the need for a proportionate, evidence-based approach to transfers into Small Self-Administered Schemes (SSASs).</div>

<div> </div>

<div><strong>Why SSASs continue to play an important role</strong></div>

<div>SSASs continue to play a unique and valuable role for directors, family businesses and owner-managed companies. They offer flexibility, support long-term retirement planning and can facilitate investments that support wider business objectives, such as purchasing commercial property or lending to sponsoring employers within existing regulatory limits.</div>

<div> </div>

<div>While the consultation highlights concerns relating to a small number of cases involving dormant SSASs, pension liberation activity and non-standard investments, these examples represent only a very small proportion of the wider SSAS market. Regulatory intervention should focus on behaviours and circumstances that indicate potential scams, rather than on SSASs as a specific type of pension scheme.</div>

<div> </div>

<div><strong>Could the proposed employment link test create unintended barriers?</strong></div>

<div>One of the key proposals would strengthen the requirement for transferring members to demonstrate an employment link with the receiving occupational pension scheme. While we understand the rationale behind this proposal, we believe it risks creating significant unintended consequences for legitimate SSAS members. Many SSAS members operate outside traditional employment models, making it difficult to demonstrate an employment link using conventional evidence. For example:</div>

<div> </div>

<div><em>Directors often remunerate themselves through dividends and irregular salary payments.</em></div>

<div><em>Employer pension contributions may be paid annually rather than monthly.</em></div>

<div><em>Members may remain in a SSAS after retirement.</em></div>

<div><em>The sponsoring employer may have been sold or ceased trading.</em></div>

<div><em>Beneficiary members may legitimately wish to consolidate pension arrangements into an existing SSAS.</em></div>

<div> </div>

<div>In these circumstances, members could struggle to provide the evidence currently envisaged by the draft regulations despite having entirely legitimate reasons for transferring accrued pension benefits into a SSAS. We are concerned that the proposals could hinder genuine pension consolidation while doing little to deter those intent on establishing fraudulent arrangements.</div>

<div> </div>

<div><strong>A more flexible and practical approach</strong></div>

<div>Rather than relying solely on conventional employment evidence, there should be greater flexibility in how an employment link can be demonstrated. For example, Companies House records could be used to verify an individual's role as a director of the sponsoring employer where traditional payroll evidence is unavailable. More broadly, employment status should form part of a wider risk assessment, rather than acting as a standalone determinant of whether a transfer can proceed. This approach would provide trustees and administrators with greater flexibility while maintaining appropriate safeguards against fraud.</div>

<div> </div>

<div><strong>Focus on fraud risks, not scheme structure</strong></div>

<div>In our experience, the greatest risks do not arise from SSASs themselves, but from specific behaviours and distribution channels.We therefore encourage the DWP to focus on indicators such as:</div>

<div> </div>

<div><em>Unregulated introducers and lead generators.</em></div>

<div><em>High-pressure sales tactics.</em></div>

<div><em>Pension liberation arrangements.</em></div>

<div><em>Undisclosed commission structures.</em></div>

<div><em>Inappropriate or excessively high-risk investments.</em></div>

<div> </div>

<div>These factors are far stronger indicators of potential consumer harm than the structure of the receiving pension scheme alone. A more effective approach would be for concerns around an employment link to act as a warning sign only when accompanied by additional risk indicators.</div>

<div> </div>

<div><strong>Why clarity is needed on &quot;reputable&quot; pension schemes</strong></div>

<div>We welcome the DWP's proposal to distinguish transfers into reputable pension schemes. However, the consultation does not currently define what constitutes a &quot;reputable&quot; scheme. Without a clear definition, there is a risk of:</div>

<div> </div>

<div><em>Inconsistent decision-making across transferring schemes.</em></div>

<div><em>Increased complaints and disputes.</em></div>

<div><em>Defensive administration practices.</em></div>

<div><em>Different outcomes for members presenting identical evidence.</em></div>

<div> </div>

<div>This uncertainty could lead to poor outcomes for members seeking legitimate transfers into SSASs. To support consistency across the industry, we believe the DWP should publish clear guidance alongside a non-exhaustive list of factors that trustees and administrators can consider when assessing whether a receiving scheme can be regarded as reputable.</div>

<div> </div>

<div><strong>Recognising the value of regulated financial advice</strong></div>

<div>Greater weight should be given to transfers supported by FCA-regulated financial advisers. Where a transfer has been recommended by an authorised adviser operating within the existing regulatory framework, this should be treated as a strong indicator that the transfer is legitimate. Recognising regulated financial advice in this way would provide an additional layer of consumer protection while helping trustees and scheme administrators make informed and efficient decisions.</div>

<div> </div>

<div><strong>Alternative evidence for legitimate SSAS transfers</strong></div>

<div>Where a member is transferring into a SSAS, practical indicators of genuine engagement with the scheme could include evidence that they:</div>

<div> </div>

<div><em>Act as a trustee of the SSAS.</em></div>

<div><em>Are a signatory on the scheme bank account.</em></div>

<div><em>Receive annual accounts or financial statements.</em></div>

<div><em>Participate in investment decision-making.</em></div>

<div><em>Have awareness of, and input into, the scheme's fees and charges.</em></div>

<div> </div>

<div>Together, these factors provide evidence that a member understands the arrangement and is actively engaged in its governance.</div>

<div> </div>

<div><strong>Our key message: proportionate regulation delivers better outcomes</strong></div>

<div>We support the Government's objective of preventing pension fraud and strengthening confidence in the transfer process. However, any new transfer conditions should recognise the realities of owner-managed businesses and the legitimate role that SSASs play in retirement planning. The challenge is not to prevent transfers into SSASs, but to identify and stop the small number of arrangements that may be misused for fraudulent purposes.</div>

<div> </div>

<div>The focus should be on identifying behaviours that indicate genuine risk rather than creating barriers for members transferring into well-governed schemes. A proportionate, risk-based framework, supported by clear guidance, consistent standards and appropriate recognition of regulated financial advice, would better protect consumers while preserving access to legitimate SSAS arrangements.</div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/getting-the-balance-right-on-ssas-transfers-27002.htm</link>
<pubDate>Thu, 30 Jul 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>4 Reasons Why Smart Doorbells May Raise Home Insurance Risk</title>
		<description><![CDATA[<div><strong>The security contradiction </strong></div>

<div>With interest in home security systems up 30% recently, safety is clearly at the forefront of homeowners&rsquo; minds. Many are installing Ring, Nest or Yale devices for peace of mind against theft.</div>

<div> </div>

<div><strong>Tamzin Metcalfe, Home insurance expert at Go.Compare explains: </strong>&ldquo;Things like smart doorbells make life much easier, and they&rsquo;re great tools. But you need to make sure your tech is actually working for you, rather than advertising a tech-savvy household full of expensive gadgets. It&rsquo;s a bit of a Catch-22: the exact thing you bought to protect your home might actually end up attracting thieves who think a fancy doorbell means your house is full of pricey items like 4K TVs, bladeless fans or top-spec gaming consoles.&rdquo;</div>

<div> </div>

<div><strong>Affluence clue</strong></div>

<div>While a visible smart doorbell could deter opportunist burglars, criminologists argue that this savvy tech could signal to calculated criminals that you&rsquo;re more likely to have expensive gadgets inside worth stealing. If your household appears to own state-of-the-art tech, you could be making yourself more vulnerable to planned burglaries.</div>

<div> </div>

<div><strong>Signal jamming</strong></div>

<div>Many homeowners are unaware of the prevalence of signal jamming devices linked to home break-ins and vehicle thefts. Devices capable of cutting your smart doorbell&rsquo;s Wi-Fi connection can be bought online for as little as &pound;30. A criminal can then use these to prevent your smart tech from recording or sending security alerts. Even if your doorbell appears to be up and running, if one of these devices are used, you might find you have no footage to use as evidence if you need to make a claim.</div>

<div> </div>

<div><strong>Footage quality</strong></div>

<div>Installing a smart doorbell is one thing, but obtaining useable footage is another. Homeowners tend to assume their smart tech is accurate enough but might neglect to check their device settings for quality. Unusable footage could make it harder to claim. If the coverage range is poor, it might miss the incident entirely. Or if the video is grainy or shaky, it could be tricky to use as evidence. Plus, some security systems require a paid subscription to save clips - or else you might lose the footage.</div>

<div> </div>

<div><strong>Insurance blind spot</strong></div>

<div>Research reveals that homeowners are already underinsured for the tech they own - 67% of Brits have never totalled the value of their home contents and laptops and tablets are among the most commonly forgotten items.</div>

<div>Installing flashy security features without checking your home contents cover exacerbates the risk of both theft and a claim that falls short.</div>

<div> </div>

<div><strong>Take the right measures to protect your home</strong></div>

<div>&ldquo;To get the most out of it, make sure your smart doorbell is set up correctly. Here are three things you can do right now if you have a smart doorbell:</div>

<div> </div>

<div><em>Check whether you need a monthly subscription to save and watch older footage. If someone tries to break in and you haven't activated that history, you won&rsquo;t have any evidence to hand over to the police or your insurer.</em></div>

<div><em>Check the camera angle and quality of the footage - like if it&rsquo;s blocked directly by a hanging basket. If you capture footage and it&rsquo;s just silhouettes where you can&rsquo;t make out any faces, it won&rsquo;t be much use. </em></div>

<div><em>Check the connection, most smart doorbells rely on WiFi, so make sure yours reaches the front door. You could choose a model with a backup local memory card in case of signal jammers or WiFi issues. </em></div>

<div> </div>

<div>It&rsquo;s also the perfect time to update your contents insurance. Make sure your policy includes all your newest tech as well as designer clothing, smart TVs, or expensive jewellery - so if anything does happen, you&rsquo;re fully covered for the replacement costs.&rdquo;</div>

<div>Homeowners are advised to review both their smart doorbell security system and contents cover: </div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/4-reasons-why-smart-doorbells-may-raise-home-insurance-risk-26998.htm</link>
<pubDate>Thu, 30 Jul 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Six Reasons The Ftse 100 Has Hit A Record High</title>
		<description><![CDATA[<p><strong>Tom Stevenson, Investment Director, Fidelity International, comments:</strong> &ldquo;The FTSE 100 hit a new all-time high this week, recovering and then exceeding the previous record set shortly before tensions in the Middle East escalated at the end of February. The strong performance of the UK&rsquo;s benchmark stock market index builds on six consecutive quarterly gains, the best run for the UK market since the recovery from the Covid pandemic. Perhaps most surprisingly, it comes despite heightened volatility in global stock markets, most notably in the AI-related shares listed mainly in the US and Asia.</p>

<p>&ldquo;There are six main reasons why the FTSE 100 has proved relatively resilient.</p>

<div><strong>1. Low technology weighting</strong></div>

<div>&ldquo;The FTSE 100 is behaving much as we might expect an &lsquo;old economy&rsquo; index to behave. While the Nasdaq has fallen 10% from its 2 June peak, Japan&rsquo;s Nikkei 225 is 14% below its 22 June high and Korea&rsquo;s Kospi has lost around a third of its value over the same period, the UK market has been relatively insulated by its limited exposure to technology. Those technology-heavy markets are more dependent on the small group of companies that drove global equities higher during the first half of the year, but which are now facing greater investor scrutiny over the sustainability of the AI boom. The Korean market is dominated by chip makers Samsung and SK Hynix, which slumped this week after disappointing investors. Taiwan is heavily influenced by another chip maker TSMC. In the US, Nvidia was the market&rsquo;s largest company until Apple reclaimed the top spot this week.</div>

<div> </div>

<div><strong>2. Rising oil price</strong></div>

<div>&ldquo;Renewed tensions in the Middle East have pushed the oil price higher, which for most markets is viewed mainly as a driver of inflation and, as such, a negative influence on interest rates and growth. While this is also true in the UK, the impact is mitigated by the FTSE 100&rsquo;s big exposure to oil companies. BP and Shell account for roughly a tenth of the value of the UK&rsquo;s benchmark. The two stocks are 10% and 5% higher, respectively, since the start of March. At their peak they were more than 25% and 15% up.</div>

<div> </div>

<div><strong>3. Other commodity exposure</strong></div>

<div>&ldquo;The FTSE 100 is also heavily exposed to non-oil commodity stocks like Rio Tinto, Glencore, Anglo American and Antofagasta. Commodity prices have been supported by expectations of further Chinese stimulus and concerns about constraints on global supply. This gives the FTSE another important source of earnings that is largely independent of the AI investment cycle.</div>

<div> </div>

<div><strong>4. Resilience to higher bond yields</strong></div>

<div>&ldquo;Rising interest rates negatively impact the valuation of growth companies so fears that the Federal Reserve may raise rates two or three times over the next year or so provide a headwind for tech stocks. Banks can be more resilient in this environment. UK banks make up a meaningful part of the UK market and may benefit from stronger lending margins and higher net interest income, although the effect will also depend on the health of the wider economy and demand for borrowing.</div>

<div> </div>

<div><strong>5. Cheap valuation</strong></div>

<div>&ldquo;The FTSE 100 continues to trade at a substantial valuation discount to the US market while offering investors a significantly higher dividend yield. That combination is increasingly attractive as investors become more cautious about paying high prices for future growth.&rdquo;</div>

<div> </div>

<div><strong>6. Political change has not unsettled markets</strong></div>

<div>&ldquo;UK financial markets have remained relatively stable through the recent political transition. During that period, the 10-year gilt yield has traded within a range of approximately 4.7% to 5.1%. It stood at 4.75% at the beginning of the period and is 4.99% at the time of writing. Over the same period, the FTSE 100 has risen by 3.4%. This suggests that recent political developments have not prompted a significant repricing of UK assets, although it is important to remember that government bond yields are also influenced heavily by global factors such as geo-political uncertainty and inflation expectations.&rdquo;</div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/six-reasons-the-ftse-100-has-hit-a-record-high-26996.htm</link>
<pubDate>Thu, 30 Jul 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Record  3 2 Bn Paid Out To Support Motor Insurance Customers</title>
		<description><![CDATA[<p>The average claim payout increased to &pound;4,900, up 4% on the previous quarter, reflecting continued pressure from rising repair costs. While modern vehicles are increasingly fitted with advanced technologies such as cameras, sensors and driver assistance systems that can improve road safety, these features can also make repairs and replacements more costly. </p>

<p>Windscreen repairs in particular saw a sharp quarterly increase, with the average repair cost rising 7% to &pound;283.</p>

<p>Despite these ongoing claims pressures, motor insurance premiums remained relatively stable. The average premium paid rose by &pound;6 (1%) during the quarter to &pound;566. Adjusted for inflation, this remains &pound;14 lower than the average premium in the same quarter of 2025.</p>

<p><strong>Chris Bose, Director of General Insurance and International Policy at the ABI commented:</strong> &quot;Motor insurers are working hard to keep premiums competitive and affordable for customers, despite ongoing high claims costs. The Motor Insurance Taskforce provides a real opportunity for the new government to work with insurers and the automotive sector on this, to help improve affordability for drivers further. </p>

<p>Alongside the positive steps the industry is taking to improve the claims handling process and to tackle vehicle-related crime and fraud, Government investment is also needed. By increasing repair sector skills and improving parts availability, policymakers can help the sector keep pace with vehicle innovation and support a more resilient market. We stand ready to work with government and industry to help deliver these reforms.&quot;</p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/record--3-2-bn-paid-out-to-support-motor-insurance-customers-27001.htm</link>
<pubDate>Thu, 30 Jul 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Inheritance Tax Liabilities Hit Record Ahead Of Iht Reforms</title>
		<description><![CDATA[<p><strong>Alice Haine, head of personal finance, Hargreaves Lansdown:</strong> &ldquo;The Inheritance Tax (IHT) net is tightening as frozen nil rate bands continue to collide with rising property prices and investment values. The result is that a higher proportion of deaths are resulting in an inheritance tax bill, while a larger share of wealth within those estates is exposed to the levy.</p>

<p>Inheritance tax receipts reached a record &pound;7.03 billion in 2023-24 and the proportion of deaths resulting in an IHT charge climbed to 4.72%, highlighting the powerful effect of fiscal drag. IHT still affects a minority of estates, and the number of estates caught by the tax dropped in 2023-24 &ndash; down 3.6% on the previous year - though the decrease may only be temporary as this dataset predates the IHT changes introduced by former Chancellor Rachel Reeves at the Autumn 2024 Budget.</p>

<p>The nil-rate band has remained frozen at &pound;325,000 since 2009, while the residence nil-rate band has been fixed at &pound;175,000 since 2020-21. With both bands now set to remain unchanged until 2031, the real value of these thresholds will erode over time. It means more estates are likely to drift into taxable territory even where there has been little change in a family&rsquo;s underlying wealth. </p>

<p>The threshold freeze is already cutting deep, but this could be just a taster of the IHT pain to come. Plans to bring unused defined contribution pension assets within the scope of inheritance tax from April 2027, alongside significant changes to business and agricultural property relief, will undoubtedly have an impact.</p>

<p> The IHT reforms to agricultural property relief (APR) and Business Property Relief (BPR) that took effect in April are already increasing the amount of wealth potentially exposed to tax.  Meanwhile, imposing IHT on unused DC pension assets from next April brings a longstanding estate planning advantage for many families to an end.</p>

<p>The combination of policy change, asset growth, frozen thresholds and a widening tax base will accelerate the inheritance tax take considerably in the years to come and families that fail to plan ahead could find themselves facing an unexpectedly large tax bill. In many parts of the country, it doesn't take vast wealth to create a potential inheritance tax liability. A family home, combined with a modest investment portfolio, can easily push estate values beyond &pound;1 million &ndash; the IHT-free threshold for a beneficiary inheriting from married parents - which helps explain why the more affluent areas of London and the South East continue to account for the highest proportion of inheritance tax-paying estates.</p>

<p>For now, inheritance tax is predominantly paid by those with significant accumulated wealth rather than the average family, but that will change in the future. Families must remember there are solutions to mitigate an inheritance tax liability. With the average effective tax rate paid by taxpaying estates in the 2023-24 tax year coming in at 13% - significantly lower than the headline marginal rate of 40%, the data demonstrates the importance of taking advantage of available exemptions and reliefs.</p>

<p>Being married, for example, remains a key tax advantage with the largest exemption applied to transfers between spouses and civil partners. After the spousal exemption, the next greatest protection against IHT was taken through business and agricultural property reliefs &ndash; with the combined value of relief claimed coming in at &pound;5.96bn, up 13% on the &pound;0.68bn in the previous tax year &ndash; though relief limits introduced since April are likely to propel that figure even higher in the coming years.</p>

<p>The planned inclusion of pensions within inheritance tax calculations from April 2027 has already radically shifted estate planning. In the past, many carefully preserved pension wealth both to support later-life spending needs and to provide a legacy for loved ones. The new rules have substantially altered those plans, with more retirees choosing to gift and spend their pensions rather than preserve their pension wealth until their final years. Research from Hargreaves Lansdown has found that nearly one in four people plan to gift their pension tax-free cash to loved ones to reduce their inheritance tax liability.</p>

<p>That said, the Government&rsquo;s proposal to reform social care may alter the retirement landscape once again. While Britain urgently needs a sustainable solution for social care, how that will be funded and the potential impact on retirement saving over the long term, remains unclear at this stage.</p>

<p>For now, those approaching retirement, or already in later life, must first consider whether their beneficiaries could be in the frame for an inheritance tax bill, and then explore what steps they can do to reduce that burden.</p>

<p>The key message is that inheritance tax planning should not be left until it's too late. Families concerned about the potential impact of inheritance tax should review their circumstances early, consider whether gifting strategies are appropriate, ensure wills remain up to date and explore the role whole-of-life insurance or trust arrangements could play in meeting future liabilities.</p>

<p>However, estate planning is a balancing act. The greatest mistake can be giving away too much wealth too soon and jeopardising your own financial security in retirement. With people living longer, it's vital that any inheritance tax strategy ensures sufficient resources remain available to support your own needs first. Given the complexity of the rules and the significant sums involved, professional financial advice can be invaluable in helping families strike the right balance between protecting wealth and maintaining long-term financial security.&rdquo;</p>

<p><a href="https://www.gov.uk/government/statistics/inheritance-tax-liabilities-statistics/inheritance-tax-liabilities-statistics-commentary#key-points"><strong>The government has released the Annual Inheritance Tax liability statistics for 2023-24</strong> </a></p>

<p> </p>

<p> </p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/inheritance-tax-liabilities-hit-record-ahead-of-iht-reforms-26999.htm</link>
<pubDate>Thu, 30 Jul 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Spp Launches Ai Governance Framework For Pensions Industry</title>
		<description><![CDATA[<div>The paper, titled Governance in the Age of AI: A Practical Framework for Responsible Leadership, emphasises that while AI adoption has rapidly accelerated, trustees' core fiduciary duties remain unchanged.</div>

<div> </div>

<div>Scheme leaders are urged to adapt existing governance, data security, and risk frameworks to oversee AI's growing influence on scheme administration, investment strategies, and member communications.</div>

<div> </div>

<div><strong>Key Principles for Responsible AI Leadership</strong></div>

<div> </div>

<div>The SPP framework outlines five core principles for schemes navigating AI integration:</div>

<div> </div>

<div><strong>Proportionality to Risk: </strong>Classifying AI usage into low, medium, and high-risk tiers. High-risk uses (such as outputs directly affecting member benefits or advice) require enhanced governance and robust validation.</div>

<div><strong>Meaningful Human Oversight:</strong> Ensuring automated decision-making (ADM) involves qualified human reviewers who hold real authority to evaluate and alter outcomes.</div>

<div><strong>Data Security & Privacy:</strong> Guarding against data breaches by ensuring confidential scheme information or sensitive personal data is never inputted into unapproved or public AI models.</div>

<div><strong>Third-Party & Adviser Governance:</strong> Updating supplier contracts to mandate transparency around AI tools, human review policies, and protection against AI-enabled cyber fraud or deepfakes.</div>

<div><strong>Member Guidance:</strong> Providing clear scheme communications to prevent members from relying on inaccurate or hallucinated guidance from public AI tools.</div>

<div> </div>

<div>The SPP stresses that AI governance is not a separate discipline but an essential component of fulfilling fiduciary responsibilities under existing regulatory standards. By embedding these controls into risk registers and service reviews today, trustee boards can confidently harness AI's efficiencies while protecting member interests</div>

<div> </div>

<div><strong>Jo Fellowes, Chair of the SPP Administration Committee said: </strong>&quot;Artificial Intelligence has moved from an emerging technology to an everyday reality across the pensions industry. The challenge is therefore not whether AI should be used, but how it can be used safely, transparently and with appropriate oversight. This SPP guide should help schemes achieve this&quot;</div>

<div> </div>

<div><a href="https://www.actuarialpost.co.uk/downloads/cat_1/SPP-Governance-in-the-Age-of-AI-29.7.26.pdf"><strong>The framework is available free, to everyone, here:</strong></a></div>

<div> </div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/spp-launches-ai-governance-framework-for-pensions-industry-26993.htm</link>
<pubDate>Thu, 30 Jul 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>2025 26 Taxable Flexible Payments From Pensions Hit  22 4bn</title>
		<description><![CDATA[<div>in 2025 to 2026, &pound;22.4 billion in taxable payments was withdrawn from pensions flexibly. This has increased from &pound;18.6 billion in 2024 to 2025 and &pound;15.3 billion in 2023 to 2024</div>

<div> </div>

<div>Through Q1 2026 (January-March 2026), &pound;5.9 billion of taxable payments was withdrawn from pensions flexibly by 770,000 individuals across 1.9 million payments. The average taxable withdrawal per person was &pound;7,700 in this period &ndash; an 18% increase in the value of payments withdrawn in this quarter compared to the same quarter in 2025, and a 15% increase in the number of individuals withdrawing.</div>

<div> </div>

<div><strong>David Brooks, Head of Policy at Broadstone, commented: </strong>&ldquo;The continued growth in taxable pension withdrawals is to be expected given the growing number of people reaching retirement with defined contribution pension pots. However, the 18% annual increase in the value withdrawn during the first quarter of 2026 compared to the previous year is striking and suggests that financial pressures may be encouraging savers to access more of their pensions.</div>

<div> </div>

<div>&ldquo;The true concern is that we have little conclusive evidence to gauge how savers are accessing their pensions and whether they are doing so in a sustainable way. Pension freedoms provide valuable flexibility but inevitably increase the risk that savings are depleted too quickly, particularly where people underestimate how long their retirement may last.&rdquo;</div>

<div> </div>

<div><a href="https://www.gov.uk/government/statistics/personal-and-stakeholder-pensions-statistics/private-pension-statistics-commentary#pension-flexibility"><strong>HMRC data can be found here: </strong></a></div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/2025-26-taxable-flexible-payments-from-pensions-hit--22-4bn-26997.htm</link>
<pubDate>Thu, 30 Jul 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Pension Withdrawals Up  3 8bn Risking Unsustainable Drawdown</title>
		<description><![CDATA[<div>In the latest tax year, (2025/26), &pound;22.4 billion in taxable payments was withdrawn from pensions flexibly &ndash; marking a new record. This has increased by &pound;3.8 billion from &pound;18.6 billion total in the previous financial year (2024/25) and by &pound;7.1 billion since 2023/24 when the total stood at &pound;15.3 billion.</div>

<div> </div>

<div>The total number of individuals withdrawing in 2025/26 also increased by 123,000 from 1.14 million people in 2024/25 to 1.27 million people.</div>

<div> </div>

<div>In Q1 2026, &pound;5.9 billion of taxable payments was withdrawn by 770,000 individuals across 1.9 million payments. The average taxable withdrawal per person was &pound;7,700 in this period. There was an 18% increase in the value of payments withdrawn in this quarter compared to the same quarter in 2025, and a 15% increase in the number of individuals withdrawing.</div>

<div> </div>

<div>Separately DWP released their latest statistics on Workplace Pension Participation and Savings Trends, which again demonstrated the increasing percentage of individuals who receive a lump sum or other Defined Contribution product when they first access their pension, which has risen from 37% in the 2016/17 financial year to 49% in the 2025/26 financial year.</div>

<div> </div>

<div><strong>Maurice Titley, Commercial Director, Data & Dashboards at Lumera, said:</strong> &ldquo;Total flexible withdrawal values continue to rise, and increasing numbers of individuals choose this route when first accessing their pension, however, there is little evidence here about how sustainably members are accessing their pension capital. That matters given many people already underestimate how much they need to save for a comfortable retirement, and the pace at which they draw down their pension can have a significant impact on how long their savings last.</div>

<div> </div>

<div>&ldquo;While some people will be accessing their pots as part of a carefully planned retirement strategy, others may not fully consider the longer-term impact on their retirement income. There is also a potential tax trap - taking a large sum in one go can push someone into a higher tax band, leaving them with an unexpectedly large tax bill.</div>

<div> </div>

<div>&quot;These figures reinforce why policymakers are shifting their focus beyond simply giving people more choice towards helping more savers achieve better retirement outcomes. Reforms such as Guided Retirement have the potential to help millions of disengaged scheme members achieve sustainable pension incomes, and the introduction of Targeted Support will help to nudge individuals appropriately during their saving journey, without them having to request personalised financial advice.</div>

<div> </div>

<div>&quot;However, delivering those reforms successfully will depend on the quality of member data and the technology underpinning pension schemes. Providers and trustees will increasingly need to make evidence-based decisions about appropriate retirement pathways at scale using the information they hold on members. That requires robust governance, accurate data and flexible technology platforms that can adapt to changing regulation while supporting more guided retirement journeys.&rdquo;</div>

<p><a href="https://www.gov.uk/government/statistics/personal-and-stakeholder-pensions-statistics"><strong>HMRC Private Pension Statistics</strong></a></p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/pension-withdrawals-up--3-8bn-risking-unsustainable-drawdown-27000.htm</link>
<pubDate>Thu, 30 Jul 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Increasing Resilience Across An Interlinked Financial System</title>
		<description><![CDATA[<div><strong>By Mark Francis, FCA director of specialists and Simon Dixon, director of supervisory risk specialists at the Prudential Regulation Authority (PRA)</strong></div>

<div> </div>

<div>Let&rsquo;s be honest, you probably didn&rsquo;t. Most people don&rsquo;t &ndash; until something goes wrong. Financial services rely on a network of providers working behind the scenes &ndash; including technology, data and operational service providers. These are so important to the resilience of the financial system that the government granted us powersLink is external to implement a new oversight regime, and has now designatedLink is external the first critical third parties (CTPs).</div>

<div> </div>

<div>That means, the Bank of England, PRA and FCA will together directly oversee these providers, with a targeted, proportionate focus on ensuring the services they provide to UK financial firms and financial market infrastructures (FMIs) are resilient. </div>

<div> </div>

<div>Our oversight aims to address system level risks, where many firms rely on the same services from common service providers. And improve coordination and information-sharing across the sector, particularly during major incidents. This complements the existing rules in place for regulated firms to manage the risks they individually face.</div>

<div> </div>

<div><strong>Operational resilience has evolved</strong></div>

<div>The primary focus of our operational resilience regulatory framework has been on the ability of individual firms to prevent, respond to and recover from disruption to maintain financial stability and confidence &ndash; including from risks arising from their outsourcing and third party arrangements. That remains vital. </div>

<div> </div>

<div><strong>What's changed is the environment in which those firms operate.</strong></div>

<div>Banks, insurers, payment firms and FMIs increasingly rely on a relatively small number of common third party service providers. These may be cloud providers, technology firms, data providers or other specialist service providers. The benefits of this approach are obvious: it can support innovation, boost efficiency, help firms improve the services they offer to millions of consumers and businesses, and contributes to the competitiveness and growth of UK financial services.</div>

<div> </div>

<div>But what happens if there&rsquo;s a failure or disruption to the services that one of these third parties offer? Recent events have demonstrated how interconnected such modern services have become. The CrowdStrike outage in 2024 affected a wide range of organisations around the world, while cyber incidents affecting retailers such as Marks & Spencer and Jaguar Land Rover showed how disruption can quickly extend beyond a single organisation. These incidents starkly illustrate how operational disruption at one provider can affect many organisations simultaneously, including financial services.</div>

<div> </div>

<div><strong>Taking a system-wide view</strong></div>

<div>Having more visibility across the system is becoming increasingly important, as the financial services landscape has changed. The numbers speak for themselves. In 2025, 27% of incidents reported to the FCA by firms were attributed to a third party issue, and 37% of those were cyber-related. </div>

<div> </div>

<div>Operational resilience can't solely be about understanding risks within individual firms. It is also about understanding how disruption at commonly used critical service providers could affect the wider system. The CTP regime adds this essential system-wide perspective. It&rsquo;s not about replacing firms' responsibilities for managing their own operational resilience and third party arrangements. Nor is it about regulating every third party provider that firms use. Put simply, it's about making sure our oversight reflects the way the system actually works today.</div>

<div> </div>

<div><strong>What this means in practice</strong></div>

<div>This regime can&rsquo;t and won&rsquo;t end all disruptions. But it is designed to make a practical difference, particularly when disruption occurs. For critical third parties, the expectations are clear. They must identify and manage risks relating to the critical services they provide. They need to test and improve their resilience arrangements, and engage openly with regulators and firms, especially during incidents.</div>

<div> </div>

<div>The regime also aims to promote greater transparency and stronger communication between critical third parties and their UK financial services clients, including through activities such as joint testing exercises and the sharing of self-assessments where appropriate. For firms, the regime should support better visibility of risks and improved communication during major incidents. When many firms are affected by the same disruption, timely information and effective coordination become even more important.</div>

<div> </div>

<div>And for consumers and businesses, the services they rely on every day should be more resilient to disruption and, where disruption does occur, be restored quickly. No framework can eliminate operational incidents entirely. But strengthening resilience across the wider system that supports financial services can help reduce the likelihood that disruption escalates or spreads unnecessarily.</div>

<div> </div>

<div><strong>Building resilience together</strong></div>

<div>One of the clearest lessons from recent years is that the operational resilience of the financial system is a shared mission. A more resilient system helps create the conditions for firms to innovate, invest and grow with confidence. Firms, regulators and third party providers all play an important role in maintaining the services that consumers, businesses and markets rely upon. The CTP regime reflects our connected reality. It recognises how the financial system operates today and ensures our approach to resilience evolves, so that the financial system can continue to safely serve businesses and consumers now and in the future.</div>

<div> </div>

<div>As the regime is now live, firms should continue to consider how they identify, test and manage dependencies on critical services. Designated CTPs should engage openly with regulators and firms, including through testing and information-sharing.</div>

<div> </div>

<div>You can find more information on critical third parties on the FCA and PRA&rsquo;s website: </div>

<div><em><a href="https://www.fca.org.uk/firms/critical-third-parties-strengthening-uk-financial-services">Critical Third Parties: Strengthening UK Financial Services | </a></em></div>

<div><a href="https://www.bankofengland.co.uk/financial-stability/operational-resilience-of-the-financial-sector/critical-third-parties"><em>FCA. Critical Third Parties (CTPs) | Bank of England</em></a></div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/increasing-resilience-across-an-interlinked-financial-system-26989.htm</link>
<pubDate>Wed, 29 Jul 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Dc Market Enters New Era As Member Outcomes Hit Centre Stage</title>
		<description><![CDATA[<div>Automatic enrolment has brought millions more people into pension saving, but many savers are unlikely to achieve the retirement income they expect. The leading pensions and financial services consultancy&rsquo;s report details the current state of the UK DC pensions market. The paper explores key themes including contribution adequacy, affordability, retirement support, financial wellbeing, investment strategy, value for money requirements and the growing role of technology in improving member outcomes. The firm warns that in a rapidly changing market, employers and trustees must routinely evaluate their schemes to ensure better retirement outcomes for employees and members.</div>

<div> </div>

<div>The UK DC market is shifting, regulatory and policy developments, including the Pensions Commission review, the Value for Money framework, pensions dashboards and guided retirement reforms, are increasing scrutiny of scheme design.  This is placing greater emphasis on whether savers are achieving good retirement outcomes. The firm argues that investment strategy, member engagement, retirement support and financial resilience will all play a critical role in helping trustees, employers and providers deliver better, fairer and more sustainable outcomes.</div>

<div> </div>

<div><strong>Commenting on the UK DC pensions market, Hannah English, Head of DC Corporate Consulting, Hymans Robertson, said: </strong>&ldquo;It&rsquo;s an exciting time for the UK DC pension market. We&rsquo;re seeing innovative solutions from across the industry to tackle some of the most pressing challenges facing savers today.</div>

<div> </div>

<div>&ldquo;Over the past decade, automatic enrolment has transformed pension saving in the UK and successfully brought millions more people into workplace pensions. However, the conversation is now moving beyond participation alone. Employers are increasingly focused on the outcomes members achieve and whether current approaches are delivering adequate retirement incomes across a diverse workforce, and the commercial impact of their businesses if this is not the case. This is driving greater scrutiny of scheme design, contribution structures, retirement support and member engagement.</div>

<div> </div>

<div>&ldquo;At the same time, the market is evolving rapidly. Developments such as pensions dashboards, guided retirement reforms, advances in technology and growing use of AI are creating new opportunities for employers to choose strategies and appoint providers to support members more effectively. We&rsquo;re also seeing greater recognition that pensions need to be considered alongside wider financial wellbeing challenges, including housing affordability and short-term financial resilience. Employers that take a holistic, long-term approach will be best placed to improve member outcomes while balancing affordability and sustainability.&rdquo;</div>

<div> </div>

<div><strong>Commenting on retirement adequacy, Kathryn Fleming, Head of DC Consulting, Hymans Robertson, said: </strong>&ldquo;Despite more people contributing to their pension than ever before, many face inadequate savings in retirement. This problem has the potential to impact millions of workers, particularly those contributing at minimum automatic enrolment levels and groups who continue to experience poorer pension outcomes, including women, ethnic minority groups and people with disabilities. While automatic enrolment has been a significant success story, participation alone does not guarantee a good standard of living in retirement.</div>

<div> </div>

<div>&ldquo;We also need to recognise that retirement adequacy does not exist in isolation. Many people are balancing competing financial priorities throughout their working lives, including housing costs, childcare, debt repayment and day-to-day living expenses. For some, improving financial resilience or achieving home ownership can be just as important to long-term financial security as increasing pension contributions. This means employers and trustees need to think more broadly about how they support members and help them balance short-term and long-term goals.</div>

<div> </div>

<div>&ldquo;With pensions dashboards on the horizon, it will become clearer for savers to see how prepared they are for retirement and what kind of living standard they can expect. That visibility should help drive engagement, but it will also shine a spotlight on the scale of the adequacy challenge facing many households. Trustees, employers and providers should use this opportunity to help members understand their position, take informed action and access appropriate support. Better retirement outcomes will depend on a combination of effective scheme design, strong investment strategies, meaningful retirement support, financial wellbeing initiatives and a clear focus on delivering long-term value for members.&rdquo;</div>

<div> </div>

<div><a href="https://www.actuarialpost.co.uk/downloads/cat_1/Hymans-uk-dc-pensions-in-2026-from-participation-to-outcomes.pdf"><strong>Hymans Robertson&rsquo;s latest paper: UK DC pensions in 2026: from participation to outcomes. </strong></a></div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/dc-market-enters-new-era-as-member-outcomes-hit-centre-stage-26986.htm</link>
<pubDate>Wed, 29 Jul 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Tensions Flare In Middle East And Ai Sell Off Continues </title>
		<description><![CDATA[<p><strong>Susannah Streeter, Chief Investment Strategist, Wealth Club: </strong>&lsquo;Tensions have flared again in the Iran conflict, just as hopes had been mounting that fresh negotiations would lead to a resolution. But instead of steps forward there&rsquo;s been a series of setbacks raising fresh concerns about the flow of energy supplies from the Middle East. Brent crude, a gauge of worry, has crept up again as traders digest the latest twists in the fractious saga.  However, the FTSE 100 has largely shrugged off events, with energy giants gaining ground on higher oil prices offering support.</p>

<p>Washington claims to have intercepted an attempted surprise attack on US bases in the region by Tehran, with Iranian missiles launched intercepted. Working with Saudi forces, the American military struck sites in Iraq, where Iranian backed militia are believed to have been operating from, with drones attacking Saudi&rsquo;s oil facilities, East of the country. High hopes that Oman&rsquo;s attempt to broker a deal over transit through the Strait of Hormuz have been dashed, with Tehran insisting it must keep control of key routes.</p>

<p>The conflict has opened up a hornets' nest of hostilities, and each retaliatory sting threatens to draw yet more regional players into an increasingly difficult conflict to control. There still remains some optimism that an agreement will be eventually brokered, but it looks set to be a long drawn-out process.</p>

<p>AI jitters are still causing volatility on indices as investors question lofty tech valuations, increased competition and future demand. Futures markets indicate a downbeat start for the Nasdaq while it&rsquo;s been another turbulent ride for South Korea&rsquo;s Kospi.  The index is down 40% from recent highs as heavyweight chipmaker SK Hynix and tech giant Samsung Electronics have lost considerable heft after a spectacular runup. The advances made by Chinese companies keep causing jolts of worry about how long the dominance of the current chip-making incumbents can continue for.</p>

<p>Federal reserve policymakers are meeting against this complex backdrop of geopolitical tensions and tech volatility. They are still largely expected to keep interest rates on hold this month to get a better reading on where inflationary pressures will land, but there&rsquo;s increased doubts coming into play, given sticky inflation and a surprise hike can&rsquo;t be ruled out.  With services inflation still too hot for comfort, wage growth elevated and higher energy prices feeding back into the mix, more of a hawkish tone is expected to emerge from this meeting. So even if rates are held all ears will be tuned into any hints from Fed chair Kevin Warsh about a possible hike in September.</p>

<p>Finally, Greggs, the baker, has put its batch of flaky sales behind it and baked up a strong set of results. New store openings, brisk grocery sales and careful cost control have helped lift profits by 20% in the first-half, showing there's still healthy appetite for affordable treats even while many consumers have turned super-cautious. Greggs has continued to take a bigger slice of the food-to-go market, proving its value proposition is resonating as households look for cheaper lunch and breakfast options. It's also proving nimble at keeping pace with the latest food trends, showing it can compete with far more premium caf&eacute;s. The iced matcha latte has emerged as one of the hits of its latest menu revamp, demonstrating that the bakery chain can blend social media-inspired tastes with its trademark value offering.</p>

<p>There is a slight soggy bottom to the outlook, though. The company is warning that investment in expanding its supply chain will weigh on second-half profits unless consumer confidence improves. It's a reminder that while Greggs is continuing to grow its store footprint and invest for the future, it's doing so against a backdrop where shoppers are still feeling the pinch. Even so, with costs well controlled, expansion continuing and its loyal customer base returning for everything from sausage rolls to pizzas and iced drinks, the long-term recipe for growth still looks firmly in place.&rdquo;</p>

<p> </p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/tensions-flare-in-middle-east-and-ai-sell-off-continues--26985.htm</link>
<pubDate>Wed, 29 Jul 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Housing Benefit  hb  System Lacks Pension Saving Incentive</title>
		<description><![CDATA[<p>The Pensions Policy Institute (PPI), the UK's leading independent authority on pensions and retirement policy, has published new research today finding that the current Housing Benefit (HB) system lacks incentive for pension saving.</p>

<p>The analysis,<strong> <a href="https://www.actuarialpost.co.uk/downloads/cat_1/PPI-private-pension-savings-for-older-renter-2026.pdf">&lsquo;Do Pension Savings Pay? Assessing the Interaction Between Housing Benefit and Private Pension Savings for Older Renters&rsquo;</a></strong>, sponsored by Independent Age, highlights that the means test of private pension savings used to calculate the amount of HB a pensioner (or pensioner household) receives could dissuade private pension saving.</p>

<p>The assessment highlights how current HB rules lack incentive for pension saving, due to the net impact of every &pound;1 of private pension income reducing HB entitlement by 65p, leaving an only 35p improvement to a person&rsquo;s disposable income. The analysis explains how this impact is created by modest private pension income currently immediately forming part of the income assessed by the HB means test, reducing the overall HB entitlement. The examination also shows how the form in which pension wealth is held can matter as much as the amount.</p>

<p>The research also reveals that HB spending may increase by &pound;3.4bn by 2044 despite the assessed eligibility rules. This reflects the growing pensioner population, and a 14% fall in home ownership rates, which will see one in three pensioner households expected to be renting by 2044.</p>

<p>A total of 330k otherwise eligible pensioners with private pension income currently see their HB entitlement either reduced or removed entirely, at an average &pound;50 weekly reduction, the investigation finds. This comes at a time when renters in retirement face growing cost of living overheads.</p>

<p>Addressing the highlighted risk of HB eligible retirees lacking incentive to save into their private pension, the study explores an alternative policy option, which would disregard part of private pension income in the HB calculation. It would disregard the first part of a person&rsquo;s private pension income, so that it would not reduce their HB at the taper rate of 65%, which is applied to private pension income or on notional income arising from private pension savings where no, or low amounts of income are being drawn.</p>

<p>For example, for someone with a full State Pension and a private pension income of &pound;100 a week, a &pound;25 a week disregard would effectively increase disposable income by &pound;16.25 per week due to the increase in HB eligibility. A &pound;25 disregard on pension saving would lift approximately 20,000 people into HB eligibility, costing the government approximately &pound;100m, according to the research.</p>

<p><strong>John Adams, PPI Senior Policy Analyst and lead author of the research, commented:</strong> &ldquo;The interaction between Housing Benefit rules and private pension income is working against eligible retirees, at a time when more pensioners facing spiralling retirement rental costs. With housing costs in retirement set to look markedly different to the last generation, policymakers will need consider how they reach the right balance to ensure Housing Benefit support works as intended.&rdquo; </p>

<p><strong>Independent Age Chief Executive Joanna Elson, CBE, said:</strong> &ldquo;As this important research shows, the Housing Benefit system isn&rsquo;t working for older renters on low incomes, especially those with small pensions. Reducing the already inadequate rental support they receive is a disproportionate response to the tiny amounts of income the pensions provide.</p>

<p>To prevent more older renters on low incomes being dragged deeper into financial hardship, we&rsquo;re urging the Pensions Commission to recommend changing the eligibility criteria for Housing Benefit, so small amounts of private pension income are disregarded. It&rsquo;s also vital the Government unfreezes Local Housing Allowance rates and ensure they keep pace with the rising costs of renting.</p>

<p>The growing number of older private renters, one third of whom are in poverty after housing costs, really do need these changes.&rdquo;</p>

<p> </p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/housing-benefit--hb--system-lacks-pension-saving-incentive-26987.htm</link>
<pubDate>Wed, 29 Jul 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Social Care Reform Must Focus On Sustainable Solutions</title>
		<description><![CDATA[<p>&quot;There is a critical need for reform of the care system in England. We hope the decision to accelerate the publication date for recommendations will in turn, bring forward the implementation of these reforms.</p>

<p>The terms of reference of the Casey Commission point to the delivery of &quot;a fair and affordable adult care system&quot;. Resolving how care is funded in a sustainable way must be a key part of any reforms. </p>

<p>The UK population is rapidly ageing. According to the Office for National Statistics, the population over age 85 is set to roughly double in the next 25 years from 2.5% to 4.9%. </p>

<p>With a rapidly ageing society, and an increasing proportion of the population comprising people in retirement, it is important that any system of funding takes this demographic change into account to ensure that the system remains sustainable, and fair from an inter-generational perspective. </p>

<p>The current social care system is complex and can be difficult to navigate for those needing care. The launch of the Big Conversation on Care consultation is a positive step forward in raising awareness of how the care funding system currently works and how it could be structured in future</p>

<p>It is encouraging to see the new Prime Minister taking a cross-party approach. To bring about effective policy change in the care system, it will need to endure over multiple electoral cycles.&quot;</p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/social-care-reform-must-focus-on-sustainable-solutions-26992.htm</link>
<pubDate>Wed, 29 Jul 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>More People Are Living To 100  5 Ways To Plan Your Pension</title>
		<description><![CDATA[<p>New figures from the Office for National Statistics (ONS) estimate there were 581,400 people aged 90 and over in mid-2025, up 3% on the previous year and more than 16% higher than a decade ago. The number of people aged 100 and over has risen to 15,172, more than a fifth higher than in 2015, while the number aged 105 and over has jumped by a third in just a year.</p>

<p><strong>Maike Currie, VP Personal Finance at PensionBee, comments:</strong> &ldquo;The growth in centenarians marks a remarkable shift in British longevity. When King George V introduced the tradition of sending congratulatory telegrams to centenarians in 1917, he wrote to just 24 people. Today, reaching 100 has become sufficiently common that the tradition has evolved into a dedicated royal operation.</p>

<p>&ldquo;Longer lives are something to celebrate, but they are also rewriting the rules of retirement. Britain has shifted away from defined benefit workplace pensions, where employers carried much of the investment and longevity risk, towards defined contribution pensions, where individuals are responsible for how much they save, where their pension is invested and ensuring it lasts throughout retirement. Living longer means our money has to work harder for longer too.&rdquo;</p>

<p><strong>Five ways to prepare your pension for a longer life</strong></p>

<div><strong>1.Plan for a longer retirement than previous generations</strong></div>

<div>Many people still assume retirement will last 15 or 20 years. Increasingly, it could last 30 years or more. The latest ONS figures show Britain is becoming a nation of centenarians, with more than 15,000 people now aged 100 or over and the number of people aged 90 and over rising by more than 16% over the past decade. Not everyone will live to 100, but many more people will spend three decades in retirement than previous generations.</div>

<div> </div>

<div>Rather than planning around average life expectancy, stress-test your finances for the possibility of living into your nineties or beyond. Running out of money is becoming one of the biggest financial risks in retirement.</div>

<div> </div>

<div><strong> 2. Think carefully about how you'll turn your pension into retirement income</strong></div>

<div>Building a pension is only half the challenge. A longer retirement means thinking carefully about how you&rsquo;ll generate an income that lasts. Some retirees choose flexible drawdown to keep their pension invested, while others value the certainty of an annuity. An increasing number are taking a &lsquo;flex then fix&rsquo; approach - using drawdown in the early years before buying an annuity later when guaranteed income becomes more important.</div>

<div> </div>

<div>Whichever route you choose, remember that inflation can reduce your spending power over time. The right solution will depend on your circumstances and, for many people, a combination of drawdown and an annuity may provide the best balance of flexibility and security.</div>

<div> </div>

<div><strong>3. Review your pension regularly</strong></div>

<div>Don&rsquo;t assume your pension is taking care of itself. Reviewing it regularly can help you understand whether you're saving enough and whether you're on track for the retirement you want. PensionBee&rsquo;s Pension Calculator can estimate how your pension could grow based on your current savings and contributions, showing whether you&rsquo;re on track and how increasing your contributions today could improve your retirement income. Even small increases made early can make a meaningful difference over time thanks to compound growth.</div>

<div> </div>

<div><strong>4. Consider a phased or semi-retirement</strong></div>

<div>Retirement doesn't have to happen overnight. Many people are choosing to reduce their hours gradually, continue consulting or freelance, or move into part-time work before stopping completely. Continuing to earn an income while drawing less from your pension can help your retirement savings last longer and gives you the opportunity to ease into retirement rather than making an abrupt transition.</div>

<div> </div>

<div><strong>5. Make the most of your pension while you're working</strong></div>

<div>The earlier you start saving, the longer your money has to grow. Taking full advantage of employer contributions, increasing contributions when you can and making use of pension tax relief can all help build a larger retirement pot.</div>

<div>If you have several old workplace pensions, consolidating eligible pots into one place can also make it easier to keep track of your savings and plan confidently for retirement.</div>

<p><strong>Maike Currie added:</strong> &ldquo;Living to 100 was once exceptional. Increasingly, it&rsquo;s becoming part of the retirement landscape that millions of people need to plan for. The biggest financial risk today isn&rsquo;t simply market volatility, it&rsquo;s underestimating how long retirement could last. The good news is that we have more control than ever before. Saving consistently, investing for the long term and making the most of the pension system can all help ensure our money lasts as long as we do.&rdquo;</p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/more-people-are-living-to-100--5-ways-to-plan-your-pension-26988.htm</link>
<pubDate>Wed, 29 Jul 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Aviva Completes  180m Full Buy in With Aston Martin Lagonda</title>
		<description><![CDATA[<div>The full scheme buy-in followed a tailored market approach led by LCP, which generated competitive terms and enabled all parties to move quickly to help the Scheme secure a transaction years ahead of expectations.</div>

<div> </div>

<div>The deal was completed in July 2026. LCP acted as lead risk transfer and investment adviser to the Trustee, with Burges Salmon providing legal advice on the transaction. Gallagher acted as Scheme Actuary and administrator to the Trustee. Aviva&rsquo;s legal advice was provided in-house.  PWC and Sackers provided advice to the Scheme&rsquo;s sponsor.</div>

<div> </div>

<div><strong>Kerry Foster, BPA Deal Manager at Aviva, said:</strong> &ldquo;Speed and certainty were critical to getting this transaction over the line and we were able to move at pace, helping the Scheme and its sponsor meet its objectives sooner than expected. This deal highlights the value of how a Scheme&rsquo;s approach to market is structured and LCP ran an effective process which allowed us to put our best foot forward to unlock an attractive opportunity for the Scheme. We&rsquo;re delighted to have been selected as a safe home for the Scheme&rsquo;s members.&rdquo;</div>

<div> </div>

<div><strong>Charles Ward, Chair of Trustee, Dalriada Trustees limited, said:</strong> &ldquo;This is a fantastic result for the Scheme&rsquo;s members, achieved significantly ahead of expectations. A huge amount of thanks are due to Aviva, the team at LCP, and all our advisers to help us unlock an opportunity which may have otherwise been missed and to deliver long-term security for members&rsquo; benefits. </div>

<div> </div>

<div><strong>Fiona Forster, Group Financial Controller, Aston Martin:</strong> &ldquo;We are delighted that the Scheme has been able to achieve this outcome and the financial security it will bring to our members. It demonstrates what can be accomplished with the right strategy in place, and the collaboration between sponsor, trustees and advisers in working together towards a common goal.&rdquo;</div>

<div> </div>

<div><strong>Sam Jenkins, Partner at LCP, added:</strong> &ldquo;It has been quite some journey for the Scheme; what was an aspirational transaction only a few months ago has rapidly turned into a hugely attractive opportunity which we are delighted to have helped secure for the Trustee. The Scheme benefited from a tailored market approach to help achieve its ambitions and it was a real team effort across the Trustee, sponsor and all advisers, allowing us to move </div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/aviva-completes--180m-full-buy-in-with-aston-martin-lagonda-26991.htm</link>
<pubDate>Wed, 29 Jul 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Db Pension Surpluses Must Be Viewed As Strategic Assets</title>
		<description><![CDATA[<p>With changes to the DB surplus regime currently under consideration, including the Department for Work and Pensions&rsquo; consultation on new surplus flexibilities, trustees will need to carefully consider how any surplus fits within their scheme&rsquo;s wider funding and endgame strategy.</p>

<p><strong>Ray Hughes, Director at HPW said:</strong> &ldquo;Improved funding positions are a positive development for many DB schemes, and the ability to consider surplus release creates new opportunities for schemes and sponsoring employers. However, surplus should not simply be viewed as capital available for distribution. The key question is how surplus fits within a scheme's broader funding and risk management strategy, and whether retaining, sharing or releasing it best supports the long-term interests of both the scheme and its members.</p>

<p>&ldquo;One of the biggest challenges will be balancing the interests of different stakeholders. While employers may have an interest in benefiting from surplus, trustees must continue to act in accordance with their fiduciary duties and consider whether members should also benefit from any surplus position.&rdquo;</p>

<p><strong>Hughes added:</strong> &ldquo;Ultimately, the question is not simply whether surplus can be released, but how it fits within the wider strategy for the scheme. Different schemes will have different objectives, whether that is progressing towards buy-out, pursuing a run-on strategy or maintaining additional resilience against future uncertainty. Good governance and a clear decision-making framework will be essential to ensuring any surplus decisions are sustainable and aligned with the long-term interests of the scheme and its members.&rdquo;</p>

<p><strong>Key considerations for trustee boards on DB pension surplus decisions include:</strong></p>

<p><em>&bull; reviewing scheme rules and any existing powers relating to surplus; <br />
&bull; assessing the sustainability of the surplus position, including under different economic scenarios; <br />
&bull; considering the employer covenant and the impact of any surplus release on long-term scheme resilience; <br />
&bull; ensuring member interests are properly considered and decisions are supported by clear evidence; <br />
&bull; reviewing whether the investment strategy remains aligned with the scheme&rsquo;s objectives; and <br />
&bull; engaging with actuarial, legal, covenant and investment advisers to support robust decision-making.</em></p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/db-pension-surpluses-must-be-viewed-as-strategic-assets-26990.htm</link>
<pubDate>Wed, 29 Jul 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Is Standard Insurance Leaving Your High value Assets Exposed</title>
		<description><![CDATA[<p><strong>By Bob Wilson, Head of Sales and Strategy for Private Clients, WTW </strong></p>

<p>Standard insurance, often arranged online or through comparison sites, may not always reflect how you live with your assets, how you travel with them and what it could cost to repair or replace them if the unexpected happens. Some standard policies may also have limitations around flexibility, global cover, or discretion when dealing with high-value claims.</p>

<p>Below, we look at where you could face insurance gaps and what to ask to shape cover more closely around the specifics of your higher-value home, cars and belongings.</p>

<div><strong>What happens if your stolen watch has risen in value since you insured it?</strong></div>

<div>We see many people running into problems with cover for their luxury watches. Let&rsquo;s say you bought a Rolex for around &pound;10,000 after being on a waiting list for several years. If it&rsquo;s stolen, you could find the same model changing hands for &pound;20,000 or more on the secondary market; more than double the original cost to replace it.</div>

<p>If your policy only covers the purchase price, that may be the amount your insurer pays out should you need to claim, subject to the policy terms and claims circumstances. More tailored cover, supported by updated valuations and extended replacement provisions where available, may improve the likelihood of replacing your luxury watch in line with current values.</p>

<div><strong>How do outdated valuations and protection weaken your fine art cover?</strong></div>

<div>Outdated valuations can leave your art collection exposed. In one case we supported, an art collection was insured at &pound;45 million, based on outdated figures. Once we reviewed the collection and revalued key works, the true value was valued at more than &pound;76 million.</div>

<p>The same review also identified an unmet fire protection requirement, which had left the client without fire cover for several years. We recommended a provider to install the required fire protection, helping the client address the identified gap and improve the suitability of cover for the collection.</p>

<div><strong>Could your high-spec home be underinsured due to rebuild costs?</strong></div>

<div>This happens more often than many owners of prime property realise. A building's sum insured can stay unchanged for years, even as rebuild costs rise.</div>

<p>In one case, a homeowner we supported believed &pound;3 million of cover was sufficient for their property. But when we carried out an on-site appraisal of the property that considered the high-specification finishes, including the services and materials needed to put the property back into its original condition. This showed the rebuild cost was closer to &pound;3.6 million, or &pound;600,000 of underinsurance.</p>

<div><strong>Does your jewellery cover reflect daily use?</strong></div>

<div>Your cover may not be the best value because it doesn&rsquo;t reflect how you use your jewellery. Let&rsquo;s say you own &pound;300,000 worth of jewellery, but usually wear closer to &pound;50,000 at any one time. If your policy assumes you&rsquo;re carrying the full collection whenever you leave home, it may be priced for a level of risk that doesn&rsquo;t reflect reality.</div>

<p>If &pound;250,000 of your collection remains securely stored in your safe, your policy can be structured to reflect that usage, which could affect the way your premium is calculated, potentially reducing the premium.</p>

<div><strong>Why should classic car owners check their insurance policies?</strong></div>

<div>Standard motor cover may not always be designed for the way some classic car owners use their vehicles. Owners regularly drive each other&rsquo;s cars at events, club meets or informal swaps. Under many standard policies, that can mean adding named drivers one-by-one, paying extra each time, or only discovering after an accident they weren&rsquo;t covered.</div>

<p>Specialist policies can work differently. In some cases, if each car in your collection sits below a certain value, any driver can be covered automatically. Some policies can offer you cover to drive someone else&rsquo;s car without prior notification, as long as they&rsquo;re not residing at your home address. That flexibility is valuable if you&rsquo;re part of a collector network and expect to use classic cars the way many enthusiasts do.</p>

<p>Rising and shifting values can sometimes leave gaps in your cover. Let&rsquo;s say you have a &pound;100,000 classic car that features in a film or sees a sudden surge in demand. Its value can jump to &pound;130,000 almost overnight. That means if you haven&rsquo;t adjusted your cover, you may not have enough cover should you need to claim. Some specialist policies may include agreed value or automatic uplift provisions, which can help address sudden market changes.</p>

<p>Specialist policies can also better reflect drops in value. Your &pound;200,000 classic car may be repaired to a flawless standard after an accident, but once original parts are replaced, the car is no longer considered fully original, meaning its market value could fall.</p>

<p>In one case we worked on, a specialist team revalued a classic car after repair and supported a further claims discussion with the insurer. This type of protection is not always well understood, so it can be helpful to ask your broker whether it is relevant to your circumstances.</p>

<div><strong>Where else can cover for high-value assets sometimes fall short?</strong></div>

<div>If you travel with your possessions or need to make a claim with discretion, some standard policies may not be designed to reflect the needs of owners of higher-value property and possessions.</div>

<p>In one case we managed, a client needed to move collectibles valued at $2 million from the UK to the US. As their private client insurance broker, we helped arrange specialist transport, guards and a lock box, based on the client&rsquo;s specific requirements.</p>

<p>In another case, a high-profile sports client lost a valuable watch. We supported the claims process discreetly and helped the client obtain a crime reference number, while being mindful of confidentiality considerations.</p>

<div><strong>What should you ask your broker to check if your cover is suitable for higher-value assets?</strong></div>

<div>There are a number of questions you can ask your insurance broker to check your cover is fit for purpose, including:</div>

<div><em>When did you last update the valuations on your policy?</em></div>

<div><em>How is your broker confident your home and contents insurance accurately reflects rebuild costs or how you use your valuables?</em></div>

<div><em>Is your classic car insured if someone else drives it?</em></div>

<div><em>How can your broker help if you need discretion to make a claim?</em></div>

<div><em>Who will help you if you need specialist logistics to transport valuables?</em></div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/is-standard-insurance-leaving-your-high-value-assets-exposed-26977.htm</link>
<pubDate>Tue, 28 Jul 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Aviva Appoints Mike Ambery As Director Of Wealth Policy</title>
		<description><![CDATA[<div><strong>Commenting on the appointment, Michele Golunska said: </strong>&ldquo;Aviva plays an important role in working with government to help shape the wealth policy landscape. Mike joins us at a pivotal time for our industry, following the recent introduction of the Pension Schemes Act and ahead of the forthcoming Pensions Commission recommendations. We&rsquo;re delighted to welcome him to the team. He brings huge experience and a genuine passion for policy.&rdquo;</div>

<div> </div>

<div>Mike joins from Standard Life, where his most recent role was Retirement and Savings Director.</div>

<div> </div>

<div>He joined Standard Life plc in 2024 and, as Retirement and Savings Director, led thought leadership on current and future savings and pensions issues for consumers and the pensions industry. Before that, he spent 17 years at Hymans Robertson as a Partner, leading firm-wide propositions, and overseeing DC Master Trust consolidation for several high-profile corporate clients. He also advised on M&A and helped create one of the UK&rsquo;s leading independent benchmarking tools for the provider market.</div>

<div> </div>

<div><strong>Mike Ambery said: </strong> &ldquo;I&rsquo;m thrilled to be joining Aviva and working closely with the leadership team within its Wealth business. With major regulatory change and savers&rsquo; needs evolving quickly, this is an important time for pensions. I&rsquo;m looking forward to helping Aviva build on its success while keeping customers firmly at the centre.&rdquo;</div>

<div> </div>

<div>Mike replaces Emma Douglas, who held the role for two years before recently becoming Chair of The Pensions Regulator.</div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/aviva-appoints-mike-ambery-as-director-of-wealth-policy-26980.htm</link>
<pubDate>Tue, 28 Jul 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Ai Jitters Hit Chip Stocks But Ftse 100 Proves Resilient</title>
		<description><![CDATA[<p><strong>Susannah Streeter, Chief Investment Strategist, Wealth Club:</strong>&lsquo;&rsquo;The AI powered rollercoaster has taken another lurch downwards, with chip stocks falling sharply, as investors reassess rising competition and future demand. Just as geopolitical tensions appear to be easing slightly, there&rsquo;s been a refocus on the runners and riders of the tech revolution, with a new kid on the chip block causing mayhem.</p>

<p>Markets in Asia were roiled by a sell-off, with South Korea&rsquo;s Kospi plunging 10% and Japan&rsquo;s Nikkei sliding more than 4%. Wavering sentiment towards semiconductor manufacturer stocks, which have hit eye-watering valuations and skewed the performance of indices, prompted the falls. SK Hynix and Samsung both were down more than 12% at one point, with trading halted on the Kospi amid the frenzied sell-off. The trigger appears to have been the blockbuster debut of ChangXin Memory Technologies (CXMT) on the Shanghai STAR Market, causing frissons of worry about just how quickly the Chinese memory maker will aggressively expand production.</p>

<p>It&rsquo;s the fourth-largest producer of DRAM and threatens to knock market leaders SK Hynix and Samsung off their perches. DRAM is the dynamic fast-working memory used in everyday items from smartphones and computers, but crucially also for AI accelerators, microprocessors designed to execute AI workloads at lightning speed. Investors had allocated significant chunks of portfolios to the South Korean chip makers and are rotating out to free up capital in expectation there will be more chip opportunities coming out of China and its ambitious AI strategy, with more expected to flow through the IPO pipeline. US-listed Micron shares also fell back, as investors assess the growing competition and adjust allocations.</p>

<p>It&rsquo;s a reminder just how volatile AI investments are right now, given how quickly tech is advancing and how the market share of mighty incumbents threatens to be gobbled up. There are also big questions about demand once this ferocious build-out phase of AI infrastructure has waned, but for now the big focus is who will be the future winners of growing global demand.</p>

<p>The Footsie&rsquo;s tech-light nature has insulated it from the turbulence hitting markets elsewhere. It&rsquo;s set for a flat start to trading, with lower crude prices pulling down listed energy giants, as hopes rise for a positive outcome of talks over the Middle East crisis. Investors are also digesting key corporate results, with Unilever providing particular cheer.</p>

<p> </p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/ai-jitters-hit-chip-stocks-but-ftse-100-proves-resilient-26975.htm</link>
<pubDate>Tue, 28 Jul 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Hidden Costs Of Oxford Street Going Car free</title>
		<description><![CDATA[<p>Go.Compare's motor insurance specialist Steve Ramsey is urging motorists to consider the less obvious consequences before the changes come into effect. </p>

<p><strong>Five things to check before Oxford Street goes car-free </strong></p>

<div><strong>1. Your Sat Nav is about to change your route - and that matters for your insurance </strong></div>

<div>Most drivers don&rsquo;t realise that regularly using new routes, particularly through busy residential streets, can impact their risk profile. Likewise, drivers with &lsquo;black-box&rsquo; telematics insurance should remember that their journeys are monitored automatically. </div>

<div> </div>

<div>But according to Steve, a changing route isn&rsquo;t usually a reason to update your policy. In reality, the key factor is whether route diversions will increase your annual mileage above the figure stated in your policy.  &ldquo;If it looks like you're going to drive significantly more miles than you stated at policy inception, then you should inform your insurer.&rdquo; </div>

<div> </div>

<div><strong>2. Delivery drivers and van drivers face major disruption </strong></div>

<div>Servicing vehicles will only have access to Oxford Street between midnight and 7am. This could create a significant operational challenge, as rerouted delivery drivers and couriers will cover more miles, and face longer journeys with more congestion at concentrated hours. Mileage-based van insurance policies could also be impacted as restrictions push traffic onto surrounding roads.<strong> Steve continues:</strong> &ldquo;Commercial motorists should monitor whether route diversions could result in a higher annual mileage than originally declared.&quot; </div>

<div> </div>

<div><strong>3. Taxi and private hire drivers need to check their business cover </strong></div>

<div>Trips for taxis and private hire vehicles (PHV) that previously used Oxford Street as a key through-route will become longer and more congested as they&rsquo;re rerouted to adjacent streets.  Business insurance policies for taxi and PHV drivers are often mileage-sensitive. As these diversions become part of their everyday route, drivers might find annual mileage creeping up.  &quot;The Oxford Street closure is likely to have the greatest impact on professional drivers who need to navigate diversions several times a day rather than once or twice a week. It&rsquo;s worth checking to see how this could impact your policy.&quot; </div>

<div> </div>

<div><strong>4. Driving challenges beyond the pedestrian zone  </strong></div>

<div>Oxford Street attracts more than half a million visitors [2] every day. Once the pedestrianisation spreads visitors across surrounding streets and traffic increases outside the car-free zone, drivers may be met with more challenging driving conditions. &ldquo;Drivers should take extra care when navigating roads around Oxford Street following the closure. While pedestrianisation plans won&rsquo;t directly impact your car insurance, making sure you have comprehensive cover can offer peace of mind in busy, urban environments.&rdquo; </div>

<div> </div>

<div><strong>5. The congestion charge and ULEZ implications </strong></div>

<div>For London motorists avoiding the Oxford Street car-free zone, the financial impact might be more than mileage and fuel costs alone. Drivers forced onto less familiar roads could find themselves travelling through congestion charge or ULEZ zones they wouldn't normally enter. &ldquo;Drivers who regularly travel through the West End of London could find themselves relying on alternative routes, making journeys longer, more congested, and potentially more expensive than they&rsquo;re used to. It&rsquo;s worth planning ahead and understanding any charges that could apply to your commute.&rdquo; </div>

<div> </div>

<div><strong>Check your cover and avoid unwanted surprises </strong></div>

<div><strong>According to Steve:</strong> &ldquo;Oxford Street shifting to a car-free shopping zone is one of the biggest changes to London&rsquo;s road network in recent years. Drivers don&rsquo;t need to tell their insurer if their daily route changes, but they shouldn&rsquo;t assume nothing else changes, either. Take a moment to check for increases in your mileage, anticipate any new charges, and to review your level of cover. The easiest way to work out your annual mileage is to look at your last two MOT certificates. The difference tells you how many miles you drove in the last year.&rdquo; </div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/hidden-costs-of-oxford-street-going-car-free-26981.htm</link>
<pubDate>Tue, 28 Jul 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Pensions Dashboards Webinar Connection Is Just The Start</title>
		<description><![CDATA[<div><iframe allow="accelerometer; autoplay; clipboard-write; encrypted-media; gyroscope; picture-in-picture; web-share" allowfullscreen="" frameborder="0" height="315" referrerpolicy="strict-origin-when-cross-origin" src="https://www.youtube.com/embed/Dj9Vn5F4oOE?si=xf2KEFZbM_zB_N7S" title="YouTube video player" width="340"></iframe></div>

<p> </p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/pensions-dashboards-webinar-connection-is-just-the-start-26978.htm</link>
<pubDate>Tue, 28 Jul 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>A Little Goes A Long Way For The Self employed</title>
		<description><![CDATA[<p>The analysis examines one-off contribution behaviour among more than 20,000 self-employed PensionBee customers over the past year, identifying three groups by contribution frequency. Just 9% contributed between six and twelve times, and only 4% made twelve or more one-off payments.</p>

<div><strong>Little and often adds up</strong></div>

<div>Low frequency savers make larger individual deposits, averaging &pound;1,036 per transaction compared to &pound;642 for medium frequency contributors and &pound;355 for high frequency savers. On the surface, that looks encouraging.</div>

<p>But the annual picture tells a different story. Despite putting in less per transaction, high frequency savers accumulate an average of &pound;7,760 over the course of a year. Medium frequency savers reach &pound;5,394. Low frequency savers, despite their larger individual deposits, average just &pound;1,763 annually. The data shows that contributing little and often can be far more effective than waiting for a single &lsquo;right&rsquo; moment.</p>

<p>The pattern reflects the reality of being self-employed. Variable and unpredictable income makes regular commitments difficult, and for many, pension saving happens when cash flow allows: a strong month, a good quarter, or a conscious decision to set money aside before it is spent elsewhere. But waiting for the right moment tends to mean contributing less overall.</p>

<div><strong>A wide spread of saving behaviour</strong></div>

<div>The data reflects the difficulty many self-employed people face with income predictability. For most, pension saving happens when cash flow allows: a strong month, a good quarter, or a conscious decision to set money aside before it is spent elsewhere. That is understandable, but it leaves retirement outcomes heavily dependent on timing and circumstance rather than consistency over time.</div>

<p>The spread is striking. High frequency savers end the year with more than four times the total contributions of low frequency savers, not because they earn more, but because they save regularly. Low frequency savers account for nearly 70% of total contribution value in aggregate, but that figure is concentrated among a small number of customers making very large deposits. For most in this group, contributions are modest and irregular.</p>

<div><strong>What the data tells us about self-employed pension engagement</strong></div>

<div>The picture that emerges is that of a self-employed saving population that is neither consistently engaged nor entirely disengaged, but episodic. Most self-employed pension savers dip in and out of active contribution, shaped by the rhythms of their income rather than by habit or structure.</div>

<p>For employees, Auto-Enrolment removes this problem by making saving the default. For the self-employed, no such mechanism exists. The result is a large population of savers who are willing to contribute, as the value of low frequency deposits demonstrates, but who either lack the regularity and predictability of income, or lack the consistent touchpoints that turn occasional saving into intentional retirement building.</p>

<p>The data also raises a question about the high frequency group. Contributing consistently over time can smooth out the impact of volatility rather than trying to time a lump sum. For people who find financial decisions stressful, that predictability has psychological value too. Consistency tends to be less anxiety-inducing than deciding when and how much to put in each time.</p>

<p><strong>Lisa Picardo, Chief Business Officer UK at PensionBee, said: </strong>&ldquo;What this data shows is that contributing little and often into a personal pension is often the best way to build a strong retirement pot. For most of the self-employed, this approach is the one most likely to soften the impact of volatility, whilst also likely being less stressful in comparison to making a handful of lump sum deposits.</p>

<p>&ldquo;The good news is that a personal pension is already built to support this kind of saving, offering maximum flexibility - no minimum contribution, no fixed schedule, no employer required. You put in what you can, when you can, and every penny attracts tax relief from day one. For people managing variable income, that flexibility is not a compromise, it&rsquo;s a must have. But by committing to making smaller contributions more frequently over the course of the year, pension saving becomes much more of an intentional part of wealth building for the future, rather than sporadic saving.</p>

<p>&ldquo;What is particularly striking is the small group contributing every single month by choice, is their election to mirror the saving habits of their employed peers who are Auto-Enrolled. They are not being nudged or defaulted into it, yet they&rsquo;ve decided to treat their pension like any other regular financial commitment. A personal pension makes that straightforward to do, as it&rsquo;s easy to set up regular monthly contributions as a baseline for saving, and then top-up further if and when cash flow allows. If more self-employed savers understood how well it fits around the way they actually work and earn, we believe far more would engage the same way.&rdquo;</p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/a-little-goes-a-long-way-for-the-self-employed-26976.htm</link>
<pubDate>Tue, 28 Jul 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Scots Could Save  46k In Income Tax By Living In England</title>
		<description><![CDATA[<p>In a new analysis, Rathbones shows top earners could save more than &pound;46,000 in income tax over five years by moving to England and commuting to their jobs, instead of remaining Scottish taxpayers.</p>

<p>The cross-border commuter trend is emerging through conversations with Rathbones clients and prospective clients who work in Scotland but are increasingly questioning where they should live as the gap between Scottish and rest-of-UK income tax rates continues to widen.</p>

<p>Rathbones&rsquo; analysis shows that someone earning &pound;250,000 could pay around &pound;8,900 less income tax in the first year alone if subject to the income tax rates that apply in England rather than Scotland. Assuming salary growth of 2% a year, the cumulative difference could exceed &pound;46,000 over five years.</p>

<p>The findings reflect the Scotland&rsquo;s devolved income tax system. Scotland currently operates six income tax rates above the Personal Allowance, ranging from 19% to 48%, while England, Northern Ireland and Wales have three main rates of 20%, 40% and 45%.</p>

<p>Rathbones recently warned that Scotland&rsquo;s divergent income tax regime could hamper efforts to attract investment, entrepreneurs and skilled workers.</p>

<p><strong>Gordon Lawrie, Head of Rathbones&rsquo; Edinburgh office, says:</strong> &ldquo;For higher earners, the tax map of the UK is becoming harder to ignore. A worker can live on one side of the border, work on the other and, depending on their tax residence, face a materially different income-tax bill.</p>

<p>&ldquo;High earners ask us a very simple question, namely can I save tax if I live in England and continue to work in Scotland? Someone earning &pound;250,000, the difference could exceed &pound;46,000 over five years, which is enough to make tax part of the conversation alongside housing, commuting and wider lifestyle considerations.&rdquo;</p>

<p>For someone earning &pound;150,000, the potential difference is around &pound;5,900 in the first year and more than &pound;30,500 over five years. The potential five-year income tax difference ranges from approximately &pound;12,300 for someone earning &pound;80,000 to more than &pound;46,000 for someone earning &pound;250,000.</p>

<p>The analysis also highlights the significant impact of the Personal Allowance taper. Between &pound;100,000 and &pound;125,140, taxpayers effectively face a marginal income tax rate of 60% in England. For Scottish taxpayers paying the 45% Advanced Rate, the equivalent effective marginal rate can rise to 67.5% while the Personal Allowance is being withdrawn.</p>

<p>Rathbones, which has offices in Glasgow and Edinburgh, argues that policymakers should place greater emphasis on Scotland&rsquo;s long-term competitiveness through a simpler and more competitive tax system, in turn strengthening the country&rsquo;s appeal as a place to live, work and do business.</p>

<p><strong>Adam Drummond, Head of Rathbones&rsquo; Glasgow office, says: </strong>&ldquo;There is also a broader economic question for Scotland.  If tax policy starts driving higher earners elsewhere policymakers should consider what that means for Scotland&rsquo;s long-term competitiveness, its ability to retain and attract investment and entrepreneurs to drive growth.&rdquo;</p>

<p> </p>

<p> </p>

<p> </p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/scots-could-save--46k-in-income-tax-by-living-in-england-26979.htm</link>
<pubDate>Tue, 28 Jul 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Tpr Uses Anti avoidance Powers To Protect Plumbing Industry</title>
		<description><![CDATA[<p>TPR has<a href="https://www.thepensionsregulator.gov.uk/document-library/enforcement-activity/regulatory-intervention-reports/plumbing-mechanical-services-uk-industry-pension-scheme-regulatory-intervention-report"> published a report</a> setting out its actions to protect members and businesses after a participating employer in the scheme paid out dividends prior to the company's liquidation - money which should have gone towards funding people&rsquo;s retirements.</p>

<p>The regulatory intervention report details how it took steps to exercise its anti-avoidance powers against Cliden Construction Limited (CCL) resulting in a settlement being reached with a former director of CCL and a related company.</p>

<p>Many DB schemes are better funded than at any point in recent memory, with around 90% of schemes fully funded (on the &lsquo;technical provisions&rsquo; basis). However, a small proportion are in deficit.</p>

<p>The multi-employer plumbing industry scheme, which has a deficit of around &pound;258 million, is an industry-wide defined benefit (DB) multi-employer scheme with over 30,000 members. The scheme is sponsored by more than 300 employers.</p>

<p>Participating employers leaving the scheme are required to pay a debt to meet their share of a pension deficit. If an employer fails to pay its debt, the liability is distributed across the remaining employers.  </p>

<p><strong>Gaucho Rasmussen, TPR&rsquo;s Executive Director, Enforcement and Legal Group, said: </strong>&ldquo;Members rely on pensions to provide them with a sustainable income in retirement and employers cannot simply walk away from their responsibilities. While we aim to prevent harms through constructive engagement, we will not hesitate to use our enforcement powers where necessary to secure positive outcomes and as a deterrent against this type of behaviour.&quot;</p>

<p>&ldquo;We will continue to work together with the trustees of the plumbers&rsquo; scheme to ensure that employers understand the importance of paying their debts to the scheme and the potential consequences of not doing so.&rdquo;  </p>

<p>CCL triggered a debt under section 75 of the Pensions Act 1995 in early 2019 when it ceased to employ active members of the scheme.</p>

<p>TPR&rsquo;s investigation found that CCL, alongside connected parties, had taken a series of steps to avoid its section 75 debt. These included issuing dividends effectively removing funds that could have gone into the pension scheme. CCL later entered liquidation in June 2023 with the debt still unpaid.</p>

<p>In response, TPR launched an anti-avoidance investigation culminating in a Warning Notice seeking Contribution Notices against CCL and connected parties.</p>

<p>TPR used a range of its legal powers in the case including compelling witnesses to attend interviews on three occasions to provide information, and fining CCL&rsquo;s accountants for failing to comply with statutory information requests.</p>

<p>Following the Warning Notice, a settlement was reached with the relevant parties, and funds have now been paid into the scheme.</p>

<p> </p>

<p> </p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/tpr-uses-anti-avoidance-powers-to-protect-plumbing-industry-26982.htm</link>
<pubDate>Tue, 28 Jul 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Poll Shows Need To Rethink Salary Sacrifice Pension Reforms</title>
		<description><![CDATA[<div>After attendees at the SPP event had heard from a panel of expert speakers about the costs and benefits of salary sacrifice, they were asked what they think should happen next.</div>

<div> </div>

<div>Nearly two thirds of respondents (62%) indicated they would like the reforms scrapped compared to only 5% who agreed with the government that the reforms should be implemented in their current form.</div>

<div> </div>

<div>Nearly a quarter (24%) opted for the reforms to be implemented but in a different form and just 9% chose the option, &ldquo;Salary Sacrifice for pension contributions should be abolished altogether.&rdquo;</div>

<div> </div>

<div><strong>SPP member Steve Hitchiner, who chaired the event, said: </strong>&ldquo;This industry polling reveals strong support for rethinking these reforms, which is not a huge surprise given the changes will result in higher costs to employees &ndash; including over 850,000 basic rate taxpayers - and employers, along with less pension saving when more saving is needed.</div>

<div> </div>

<div>Salary sacrifice has long been an effective way of helping both employers and employees maximise pension contributions while reducing National Insurance costs. Restricting the NIC exemption from 2029 risks undermining those benefits and could discourage some employers from continuing to offer salary sacrifice arrangements altogether.</div>

<div> </div>

<div>While there was recognition from some attendees that reform may be necessary, this SPP polling shows there is little appetite for the proposals in their current form. With a new Prime Minister and new Chancellor, the government should take this opportunity to engage with the pensions industry to explore alternative approaches that achieve its objectives without reducing incentives to save for retirement or placing additional financial burdens on workers and employers.&quot;</div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/poll-shows-need-to-rethink-salary-sacrifice-pension-reforms-26983.htm</link>
<pubDate>Tue, 28 Jul 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Ppf Consultation On Updated Db Scheme Valuation Assumptions</title>
		<description><![CDATA[<p>The assumptions are used to estimate the cost of securing PPF levels of compensation with an insurer and underpin section 143 valuations conducted during PPF assessment periods, as well as section 179 valuations used for a variety of purposes including, historically, PPF levy calculations.</p>

<p>The consultation follows a review of bulk annuity market pricing, which found pricing had become more competitive since the PPF&rsquo;s last detailed review. The main proposed changes cover discount rates and longevity assumptions. The proposed updates are intended to keep the assumptions aligned with current buy-out pricing and would generally reduce estimated scheme liabilities under the valuation bases.</p>

<p>The PPF regularly reviews market developments to ensure its assumptions remain appropriate. The current standard assumptions were set after a 2023 review, with guidance updated in 2024 to allow bespoke adjustments to the section 143 discount rate in limited circumstances.</p>

<p><strong>Aaron Pang, Acting Chief Actuary at the Pension Protection Fund, said:</strong>&quot;We regularly review our valuation assumptions to ensure they remain appropriately aligned with the bulk annuity market and continue to meet the objectives set out in legislation.</p>

<p>Our latest review suggests that market pricing has moved since the assumptions were last comprehensively updated. The proposals in this consultation are intended to reflect those developments while continuing to provide a practical and proportionate framework for valuations. We encourage trustees, actuaries, advisers, insurers and other stakeholders to review the proposals and share their views.&quot;</p>

<p>The consultation document is available in the PPF's valuation guidance section on the website: <a href="https://www.ppf.co.uk/trustees-advisers/valuation-guidance/new-consultation-documents">Consultation documents | Pension Protection Fund</a></p>

<p>The consultation closes at 5pm on 16 September 2026. Subject to the outcome of the consultation, the PPF intends to publish its final decision in October 2026. The proposals currently envisage the revised assumptions applying to valuations with an effective date on or after 31 May 2026.</p>

<p>Responses can be submitted by email to:  <a href="mailto:AssumptionsConsultation@ppf.co.uk">AssumptionsConsultation@ppf.co.uk</a>.</p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/ppf-consultation-on-updated-db-scheme-valuation-assumptions-26984.htm</link>
<pubDate>Tue, 28 Jul 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Lgr And The Lgps  Devolution In England Gathers Pace</title>
		<description><![CDATA[<p><strong>By Michael Burton, GAP Consultant, Hymans Robertson</strong></p>

<p>Once again, the LGPS didn&rsquo;t get a mention. However, virtually all funds can now start preparing for the future. </p>

<div><strong>What do we know? </strong></div>

<div>There will be both internal and external boundary changes when compared to the current position and there have been some surprises when it came to the number of unitary authorities to be adopted. Not least for Oxfordshire, which has seen an increase in the size of Oxford City and the establishment of three unitaries,  including taking over West Berkshire. </div>

<p>A key message, which is repeated across the various decision letters, is around housing and economic growth. The government has consistently approved the expansion of city boundaries across England with direct reference to increasing the available housing stock, something that will no doubt keenly interest funds and investment pools. </p>

<p>Another point of interest is that while the number of senior officers actively participating in funds will decrease, eg less 151 officers will be required, there will be service areas that may need to take on staff. In regions such as Warwickshire, the decision letter specifically points to disaggregation of services that are currently provided on a county wide basis and the loss of benefits of scale. This means funds in areas which see services disaggregated can expect to see a spike in the employment of more junior officers to fulfil these roles. </p>

<p>On the subject of administration tasks, we&rsquo;ve been talking for some time about the administrative challenges that LGR will bring. There will need to be bulk transfers, changes to contracts and, sadly, redundancies. Where boundary changes take place, these challenges will be all the greater and only increase the scale and complexity of the work that needs to be carried out. </p>

<div><strong>What does this mean for LGPS funds? </strong></div>

<div>Many funds will want to see guidance to understand the governments expectations. However, waiting for this guidance for too long can introduce risks. The government is clear that it won&rsquo;t seek to depart from the published timetable of elections in May 2027 and new authorities coming into being in April 2028 (in most places). </div>

<p>There are some key questions which need to be addressed, and funds will no doubt want to be part of the conversations: </p>

<div><strong>What will be the operational structure of the fund? </strong></div>

<div>Will it follow the existing approach where the Administering Authority is a local council or will it seek a different approach, such as becoming a Single Purpose Pension Authority (SPPA)? Each model has its own combination of benefits and challenges. While Surrey has received permission to adopt a SPPA model, and others are interested in a similar direction, LGPS funds are unlikely to benefit from a one-size-fits-all approach. </div>

<div> </div>

<div><strong>Which organisation will be the Administering Authority? </strong></div>

<div>Will the Administering Authority be the location with a history of hosting the local fund or will it move? There are opportunities and challenges associated with all options. While it's highly likely the decision will not be made locally, funds are at the forefront of preparation are keen to understand the implications and take part in the inevitable debate. We&rsquo;d recommend all funds investigate the pros and cons of the various Administering Authority options.</div>

<div> </div>

<div><strong>Who will sit on a Pension Committee? </strong></div>

<div>A new Pension Committee will need to be formed. There's likely to be an appetite to expand membership to cover the various unitaries that will make up the geographical area previously covered by a County Council (except for Gloucestershire, which is the only place to have a &ldquo;One Unitary&rdquo; proposal agreed). June&rsquo;s fund governance guidance referenced this being a possibility, which may ease the concerns some have for an expanded Committee. That said, having representatives from multiple authorities means various authority constitutions will need to cover how it works, creating the challenge of reaching a consensus. </div>

<div> </div>

<div><strong>How will contribution rates be affected? </strong></div>

<div>With member movements, retirements, redundancies and changing funding positions, contributions may look quite different when we reach the, surprisingly imminent, 2028 actuarial valuations. Not to mention the associated cashflow implications. All this may carry some unpleasant surprises for employers, and some funds are already starting to consider the implications. </div>

<div> </div>

<div><strong>What do stakeholders need to be told? </strong></div>

<div>It&rsquo;s hard to argue that LGR won&rsquo;t lead to a material change in how local funds in England will be run. So, there will be a duty to engage with LGPS members. It&rsquo;s likely the uncertainty such wide changes cause will also lead to members becoming more nervous about the sustainability of their retirement provisions. With nervousness comes a riper landscape for pension scams so funds need to think carefully about what they say and, crucially, when they say it. </div>

<div> </div>

<div><strong>Is there enough administrative support? </strong></div>

<div>Along with BAU tasks, funds will need to ensure all member movements are properly accounted for. The changes taking place in April 2028 mean Annual Benefit Statements for 2027/28 should be unaffected, but funds will still need to promptly update records. There are also the not inconsequential impacts of a likely increase in member queries to be addressed. </div>

<div> </div>

<div><strong>What happens next? </strong></div>

<div>For all areas affected by LGR, the government will need to guide a Structural Changes Order through Parliament. The timeline for these is yet to be declared, but work is expected to start shortly, if it hasn&rsquo;t already.  </div>

<div> </div>

<div>Elections for the new authorities will take place in May 2027, leading to the creation of shadow authorities ahead of them formally taking over in April 2028. From April 2028 the LGPS will see a raft of new Administering Authorities being in place and they&rsquo;ll have to be able to provide business as usual services from day one. </div>

<div> </div>

<div> It&rsquo;s vital that funds are proactive so they can make sure they are ready for April 2028 and continue to meet the needs of members. The ultimate question is, will you be ready? </div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/lgr-and-the-lgps--devolution-in-england-gathers-pace-26974.htm</link>
<pubDate>Mon, 27 Jul 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Travel Insurance Advice For Wildfires In France And Spain</title>
		<description><![CDATA[<p>Wildfires across France and Spain have continued to cause significant disruption during the peak travel season, with mass-evacuations in affected areas. Insurers are ready to support their customers and as the fire continues to spread the ABI is sharing travel insurance advice for those in the area or with trips planned. </p>

<div><strong>If you are on holiday and have been evacuated from your accommodation: </strong></div>

<div><em>If you&rsquo;re being forced to leave your accommodation, it&rsquo;s vital you follow the advice of emergency services on the ground and any local health advice.  </em></div>

<div><em>When safe to do so, check your travel insurance policy. If your policy includes trip disruption or natural disaster cover, you should be covered if you have to cut short or cancel your holiday.   </em></div>

<div><em>Your travel insurance will apply in the usual way if you need emergency medical treatment. </em></div>

<div><em>If you have lost or had to abandon your possessions, these will likely be covered by standard travel insurance policies.  </em></div>

<div><em>Policies can vary, so speak to your insurer if you&rsquo;re not sure what is covered and they can advise on what support is available.  </em></div>

<div><em>Refunds for cancelled flights or accommodation should be sought from the airline, tour operator or accommodation provider in the first instance. Any bookings made through a credit card may also have recoverable costs.  </em></div>

<div><em>If you want to book another flight back to the UK or need alternative accommodation, speak to your insurer first to check what is covered and they can advise on next steps.</em>  </div>

<div> </div>

<div><strong>If you have a trip planned to the region: </strong></div>

<div><em>Follow the latest advice from the FCDO, especially as travelling against this is likely to invalidate your travel insurance.  </em></div>

<div><em>If you&rsquo;ve not yet set off for your holiday, contact your insurer before you decide to cancel flights or book any new accommodation. They can advise on what your policy covers. </em></div>

<p><strong>Chris Bose, Director of General Insurance Policy at the ABI, said: </strong>&ldquo;We recognise how stressful and worrying the wildfires will be for people currently in the affected areas, as well as those due to travel there in the coming days. Safety must be the priority, so it&rsquo;s important to follow the advice of local authorities and emergency services. </p>

<p> &ldquo;Insurers are ready to support their affected customers. If your travel plans are disrupted by a wildfire and your policy includes trip disruption cover then travel insurance may cover some of the resulting costs. It can also help if you become ill or are injured. </p>

<p>&ldquo;Where flights or accommodation are cancelled, you should seek refunds from their airline, tour operator or accommodation provider in the first instance.  </p>

<p> &ldquo;Cover can vary between providers, so if you&rsquo;re not sure what&rsquo;s included in your policy, speak to your insurer who will be able to advise on what support is available.&rdquo; </p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/travel-insurance-advice-for-wildfires-in-france-and-spain-26973.htm</link>
<pubDate>Mon, 27 Jul 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Oil Prices Drop As France And Spain Count Cost Of Wildfires</title>
		<description><![CDATA[<p><strong>Susannah Streeter, Chief Investment Strategist, Wealth Club: </strong>&quot;Fresh talk of talks over Iran is raising hopes that this newly acute phase in the Middle East crisis could see some resolution. The FTSE 100 has set off on a confident run upwards in early trade, while futures markets indicate that Wall Street will also start on the front foot. Corporate news has also lifted sentiment, with AstraZeneca shaking off some of the gloom surrounding its recent trial disappointment, with investors welcoming a stronger-than-expected set of second-quarter results. Solid growth in its oncology and rare diseases businesses helped offset weaker performances elsewhere, while the company reiterated its confidence in its long-term growth ambitions despite the setback. </p>

<p>The big confidence booster for investors at the start of the week remains signs of progress in the Middle East. Early speculation that negotiations could resume has been reinforced by a second consecutive night without US strikes and by Tehran&rsquo;s decision not to respond with further retaliatory action. While on the face of it the US administration is pushing the line that pressure is being maintained, markets remain cautious given the twists and turns during this conflict and the uncertainty over whether talks will actually come to fruition. Brent crude has fallen back sharply to trade around $90 a barrel, down by 10% since Friday, as fears of a prolonged energy crunch begin to ease. However, there is still significant uncertainty baked into these prices and a reticence about whether negotiations will lead to a lasting breakthrough. The weekend attacks by Houthi rebels continued at the Red Sea ports of Yanbu and Jizan, a reminder of how many more factions have been pulled into the war. Oil prices are still around a third higher over the month as tensions ratcheted up again. Nevertheless, with fresh negotiations looking increasingly likely, it appears to be a sign of progress, and there is an expectation that President Trump will want some kind of resolution given that the mid-term elections are looming and this war remains unpopular among voters.</p>

<p>With fears of a chronic energy crunch easing a little, it has helped take the pedal off borrowing costs, which accelerated higher last week. UK gilt yields have dipped back, easing the pressure slightly on the Burnham administration. This will be welcome given focus has switched firmly to the spending challenges facing the new government, with warnings from the Prime Minister that social care needs desperate reform to help save the NHS while also accepting that the benefits bill needs to be brought down. There is still a distinct lack of detail on how he and his ministers will go about tackling the huge costs of welfare, and so investors in government debt look set to stay wary while there&rsquo;s so much talk but so little action on lowering government spending costs.</p>

<p>While some heat is being taken out of energy prices, there&rsquo;s no change in temperature for emergency services fighting the ferocious fires raging, particularly in France and Spain. The devastating wildfires are set to leave a deep economic as well as environmental scar. As firefighters battle to contain the blazes, businesses are also counting the cost, as immediate harm is being felt across tourism, agriculture and local economies. But the financial toll is set to mount rapidly through soaring insurance claims, disrupted transport links and supply chains, and a hit to consumer spending in some of Europe&rsquo;s most popular holiday destinations.</p>

<p>The timing couldn&rsquo;t be much worse given it&rsquo;s at the height of the summer getaway season, and prolonged disruption and poor air quality threaten to take a big bite out of tourism, a cornerstone of both the French and Spanish economies. Hotels, restaurants and attractions in affected regions face cancellations and lost trade during what would normally be their busiest weeks of the year. Tourists are being urged to stay away from the Gironde in particular right now, as key routes to the beaches remain closed while the fight to contain the dramatic blazes continues. </p>

<p>The flames are also threatening some of Europe&rsquo;s most productive agricultural land. Vineyards in particular are at risk in Gironde, home to the famous M&eacute;doc wine route. While for now the flames are concentrated to the western side of the peninsula, even if vineyards escape the flames, they can still suffer from smoke taint, which can affect the quality and value of grapes. France&rsquo;s public finances will also come under fresh strain, given the government faces the prospect of another hefty bill for emergency services, rebuilding infrastructure and supporting devastated communities at a time when it is already under pressure to rein in its budget deficit. Spain faces a similar challenge, with the major fires around Madrid adding another unexpected burden to public finances, forcing more spending on emergency response, reconstruction and longer-term climate resilience.</p>

<p>As extreme weather events become more frequent and more destructive, governments and businesses will have to dig deep, diverting money from investment and growth towards recovery and rebuilding. However, for infrastructure companies and renewable energy developers, the intensifying focus on climate risks could create a powerful tailwind. It&rsquo;s forcing governments to rethink how resilient their economies are, accelerating spending on everything from fire and flood defences and upgraded power networks to more efficient water systems and climate-proof infrastructure.</p>

<p>The powerful fast-fashion giant Shein has stumbled, facing a big hurdle from the removal of US import duty exemptions amid the wider tariff war. Shein, which was founded in China, lost $99m in the first three months of the year, compared with net income of $395m a year earlier. It&rsquo;s another sign that the huge wave of ultra-cheap fashion flooding Western markets may start to lose power. The removal of the US de minimis exemption has taken away a huge competitive advantage, forcing the retailer to put up prices and absorb higher costs at the same time. That&rsquo;s a difficult combination for a business built on razor-thin margins and impulse purchases.</p>

<p>However, although the US and the EU have already acted to clamp down on low-value imports from fast-fashion giants, the UK is still playing catch-up. The government has brought forward plans to scrap customs duty relief on parcels worth less than &pound;135, but the changes won&rsquo;t come into force until October 2028. That&rsquo;s left many major high street retailers frustrated that Britain continues to lag behind its biggest trading partners, allowing Shein and Temu to benefit from an advantage that has already been stripped away elsewhere.</p>

<p>For years, high street chains have complained they are fighting with one hand tied behind their back, competing against overseas rivals able to ship low-value parcels into major markets without facing the same import costs. As governments chip away at those tax advantages, the playing field is beginning to look a little more level, even if the UK is in the slow lane in this journey.&rdquo;</p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/oil-prices-drop-as-france-and-spain-count-cost-of-wildfires-26969.htm</link>
<pubDate>Mon, 27 Jul 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Buyin Completion Marks New Phase For Trustees</title>
		<description><![CDATA[<p>The UK pension risk transfer market continues to grow, with increasing numbers of defined benefit schemes securing buy-in transactions following years of funding improvements, careful planning and strategic decision-making.</p>

<p>However, as more schemes move beyond transaction day, attention is increasingly turning to the practical steps required after a transaction. These can include resolving historic data issues, addressing benefit complexities and coordinating the wider activities needed to support a scheme&rsquo;s chosen end-game strategy.</p>

<p><strong>Rob Chandler, Consultant at Cartwright Pension Trusts, said:</strong> &ldquo;Completing a buy-in is a major achievement and one that trustees and sponsors should rightly recognise. However, transaction day should be viewed as a milestone rather than a finish line. The work required afterwards is critical to delivering the scheme&rsquo;s long-term objective.</p>

<p>&ldquo;As the market continues to mature, the focus needs to move beyond securing transactions and towards ensuring schemes are well positioned for the next phase of their journey. Trustees, insurers, administrators and advisers are all managing significant volumes of activity, making early planning, clear ownership and strong oversight increasingly important.</p>

<p>&ldquo;Data is one of the key factors that can influence progress after a transaction. Insurer reviews can uncover historic inconsistencies, missing information or benefit complexities that require careful investigation. The important question for trustees is not whether issues will emerge, but whether they have the right processes and expertise in place to address them effectively.&rdquo;</p>

<p><strong>Chandler continued:</strong> &ldquo;Trustees can help maintain momentum by reviewing their post-transaction plans early, ensuring outstanding actions have clear ownership, maintaining regular communication with advisers and service providers, and addressing data or benefit issues as soon as they are identified.</p>

<p>&ldquo;Ultimately, completing a transaction is only one part of the end-game process. Whether a scheme is moving towards buyout or pursuing another long-term strategy, success depends on the preparation, governance and collaboration that follows.&rdquo;</p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/buyin-completion-marks-new-phase-for-trustees-26970.htm</link>
<pubDate>Mon, 27 Jul 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Savers Turn To Gifting As An Iht Fix As Pension Changes Loom</title>
		<description><![CDATA[<p><strong>Helen Morrissey, head of retirement analysis, Hargreaves Lansdown: </strong>&ldquo;The inclusion of unused defined contribution pensions in estates for inheritance tax purposes from next April is having a major impact on retirement planning, the latest research from Hargreaves Lansdown shows.</p>

<p>Before the change was announced, many people planned to spend down their other assets first and leave their pension for as long as they could, so it could be passed on to loved ones, free of inheritance tax. The change in the rules has since prompted people to think again and assess what can be done to reduce the value of the estate to save their family a tax bill.</p>

<p>The research shows that gifting is viewed as a key option. Around one in four people said they would access their tax-free cash and make use of their allowances to gift to loved ones while they are still alive, rather than leaving it in a will. One in four (22%) said they would draw an income from their pension and make gifts alongside that. The same proportion of people said they would still gift but would use assets outside of their pension to do it.</p>

<p>It&rsquo;s understandable why people would consider gifting to loved ones as a means of reducing the value of their estate. Gifting to loved ones while you are still alive not only potentially saves them a tax bill but can also help them to meet their financial goals that bit earlier. It could be a one-off amount towards a house deposit or wedding, for instance, or regular contributions into a Junior ISA to help someone afford university later down the line. Contributing to a Junior SIPP can give a young loved one a real leg up the retirement planning ladder, that puts them well ahead of their peers. It can also act as an early lesson on the power of investing, which can go on to form a lifelong habit.</p>

<p>However, it&rsquo;s important not to give away too much, too quickly. This risks potentially running short of money further down the line, which can cause serious challenges. Take a longer-term approach and assess the affordability of these gifts as you go. One in five (21%) said they would spend their assets to reduce the value of their estate. This may point to someone prioritising taking their income rather than gifting - again it&rsquo;s crucial not to spend your assets down too quickly as you don&rsquo;t know how long you are going to live.</p>

<p>The upcoming changes are going to have an enormous impact on retirement planning, and it&rsquo;s important to understand the ramifications before acting. For instance, there are several different gifting allowances that can be used to reduce a potential inheritance tax bill, but they can be complex. You will also need to make detailed notes as to who you have given money to and when, so your family can evidence your gift giving if needed.</p>

<p>These are major decisions and it is a good idea to take financial advice. The data show that 27% said they would access financial advice before deciding, and this may grow over time. Advisers can play a vital role in making sure that you not only gift sustainably but also that your gifting does not fall foul of any rules that could leave your family with a large bill.&rdquo;</p>

<p> </p>

<p> </p>

<p> </p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/savers-turn-to-gifting-as-an-iht-fix-as-pension-changes-loom-26971.htm</link>
<pubDate>Mon, 27 Jul 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Hmrc Collects  1 36bn From Iht Probes In Last Five Years</title>
		<description><![CDATA[<p>HMRC recovered more than &pound;1.36bn in unpaid inheritance tax during the past five years, with collections in the last financial year down 13% on previous year, according to new figures obtained by financial advice firm NFU Mutual.</p>

<p>HMRC launches investigations into the estates of deceased individuals where underpayment of inheritance tax is suspected.</p>

<p>The amount of inheritance tax recovered following investigations was &pound;247m in 2024/25, down from &pound;285m in the previous year, and comes at a time when the total amount of IHT collected reached a new annual high of &pound;8.5bn in 2025/26.</p>

<p><img alt="" src="https://www.actuarialpost.co.uk/images/pic_NFUIHT2707261.jpg" style="height:380px; width:600px" /></p>

<p><strong>According to Sean McCann, Chartered Financial Planner at NFU Mutual: </strong>&lsquo;&rsquo; Where there is a suspicion that inheritance tax has been underpaid through error, omission or undervaluing assets, HMRC has substantial investigative powers and will check a range of sources to build a picture of the deceased individual&rsquo;s financial affairs.</p>

<p>&lsquo;&rsquo;Bank statements can be a rich vein for an HMRC investigator as they can reveal income from undisclosed assets such as overseas property or investments, as well as outgoings such as life insurance premiums, which if not written in trust will be included in the taxable estate&rsquo;&rsquo;.    </p>

<p>&rsquo;HMRC will often review the deceased&rsquo;s insurance records as part of their investigations, to ensure jewellery, wine collections and other high value items have been included in the IHT return&rsquo;&rsquo;</p>

<p>&lsquo;&rsquo;Insurance records can also highlight items that have been gifted more than seven years ago but the deceased continued to enjoy a benefit from, such as a valuable painting remaining in their home. This &lsquo;reservation of benefit&rsquo; can mean that the item is included in their Inheritance tax calculation.   </p>

<p><strong>He explains:</strong> &ldquo;In addition, the interest rate you pay on overdue inheritance tax stands at 7.75%, which can add a significant amount to the bill. This can compound what for many is already a challenging and distressing situation.</p>

<p>&ldquo;With the &pound;325,000 nil-rate band and the &pound;175,000 residence nil-rate band frozen until 2031, and pensions set to be included in the inheritance tax calculation from April next year, more families will be caught in the net with ever increasing bills for those affected.&rdquo;</p>

<p>Although the figures reveal that the sums collected from IHT investigations have fallen, according to Sean McCann, this doesn&rsquo;t mean a change in tack from the authorities:</p>

<p>&ldquo;Investigations can take months and occasionally years to complete, and therefore the &pound;247m recovered in 2024/25 may be from inquiries opened in earlier years.</p>

<p>&ldquo;The revenue recovered through these investigations is significant and the rising value of assets and the potential sums at stake would appear to justify HMRC spending more time looking at individual cases.</p>

<p>&ldquo;Inheritance tax remains one of the most feared and least understood taxes,&rdquo; he added.</p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/hmrc-collects--1-36bn-from-iht-probes-in-last-five-years-26972.htm</link>
<pubDate>Mon, 27 Jul 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Managing Conflicts Of Interest In Insurance</title>
		<description><![CDATA[<p><strong>By Chris Knight, Director of Insurance, FCA</strong></p>

<p>One item that has crossed my desk is vertically integrated business models, which we&rsquo;re publishing information for firms on today.</p>

<p>When a consumer buys insurance, they need to trust that the firm they're dealing with is genuinely working toward the best outcome for them &ndash; and that they&rsquo;re not losing out due to conflicts of interest.</p>

<p>This can happen when a single group of companies span multiple parts of the insurance chain: underwriting the policy, distributing it to customers, arranging premium finance, and providing other related services.</p>

<p>It can also happen when firms are connected through ownership or financing relationships that may be publicly disclosed or private in nature. These arrangements can make good and efficient business sense. But they can also create conflicts of interest &ndash; particularly if they influence consumer journeys or potentially alter commercial incentives. This has the potential to shape decisions in ways that don't serve the customer.</p>

<p>This isn't just a theoretical concern. We've taken enforcement action before against firms where conflicts of interest weren't properly managed, and where ownership or remuneration arrangements influenced customer outcomes.</p>

<div><strong>What firms should do</strong></div>

<div>Having a conflict of interest doesn't automatically make a business model unacceptable. But you need to take these risks seriously.</div>

<p>You must actively identify, manage and evidence those conflicts. That means effective governance, clear senior management accountability and controls that actually work in practice, not just on paper.</p>

<p>Crucially, disclosure alone is not enough. Simply telling customers about a conflict doesn't remove your obligation to manage it properly.</p>

<p>You should look at how you design products and panels, how you communicate with customers, how you structure remuneration, and whether your customer-facing information is genuinely transparent about commercial relationships that could affect a customer's decision.</p>

<p>Wherever a firm happens to be in the chain it needs to assess and be able to evidence the value added in each link.</p>

<p>If you're considering new ownership, investment or financing structures that could add complexity or create new conflicts, you should factor our expectations into that assessment from the start. </p>

<div><strong>What we&rsquo;re doing  </strong></div>

<div>We've written directly to some firms where we think their business models may be creating heightened risks of conflicts of interest.</div>

<p>But we're also making our expectations clear to the whole market &ndash; because this isn't an issue isolated to a handful of instances.</p>

<p>We are monitoring developments in this area, so you may receive ad hoc data requests. You should be able to show us how your arrangements deliver good outcomes for customers. Where business models are overly complex or difficult to supervise, we expect you to think seriously about simplifying them.</p>

<p>Any material changes to your business model that affect conflicts of interest should be notified to us promptly.</p>

<p>Our position is clear: Where we see firms acting in ways that could harm consumers, obscure accountability or undermine trust, we will act, starting with supervisory engagement, and with enforcement if needed.</p>

<p>Getting this right will help give customers that extra peace of mind that insurance products are working for them.</p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/managing-conflicts-of-interest-in-insurance-26967.htm</link>
<pubDate>Fri, 24 Jul 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Mapfre To Acquire The Safety Insurance Group For  1 54bn</title>
		<description><![CDATA[<p>This all-cash transaction, valued at $1.54 billion, represents a significant step in Mapfre&rsquo;s global growth strategy. The acquisition builds upon Mapfre USA&rsquo;s market-leading position in Massachusetts and underscores the company&rsquo;s commitment to strengthening its presence throughout the Northeast.</p>

<p>The acquisition, which has been unanimously approved by the boards of directors of both companies is expected to close in Q1 2027, and will create the second largest writer of Private Passenger Auto in New England as well as the largest Homeowners and Commercial auto insurer in the region, further enhancing service and offerings to clients and agents in the region</p>

<p><strong>Antonio Huertas, Group Executive Chairman of Mapfre, said: </strong>This acquisition is in line with Mapfre&rsquo;s strategic objectives to strengthen our position in the markets where we already operate&mdash;specifically, in this case, in Massachusetts and a number of states throughout the Northeast. I believe that the combination of our strengths will allow us to serve our clients in the U.S. even better. It will enable us to strengthen our franchise in both scale and profitability, creating strategic and financial value for our shareholders, while putting us on track for enhanced growth in the highly attractive and developed states of the Northeast.</p>

<p>Mapfre has temporarily entered into a bridge loan agreement with Citibank and Deutsche Bank, making the acquisition not subject to any financing condition. This bridge loan is intended to be replaced by a combination of ~&euro;700 million in Tier 2 capital instruments, &euro;500 million in senior debt, and the remainder via bank debt. The Solvency II impact is expected to be around 10 p.p. and pre-tax synergies have been estimated at more than $30 million p.a., with full run-rate benefits anticipated within three years. The acquisition is forecast to be accretive with an over 5% uplift to net income.</p>

<p>This transaction is designed to deliver meaningful, tangible value for Mapfre and its shareholders. The acquisition is consistent with Mapfre&rsquo;s focus on financial discipline and long-term value creation. It brings significant upside to profitability while maintaining Mapfre&rsquo;s Solvency II ratio comfortably within the company&rsquo;s target range. The funding structure is also consistent with Mapfre&rsquo;s prudent financial framework.</p>

<p>The combination of Mapfre USA and Safety is expected to strengthen Mapfre&rsquo;s overall profitability, stability, and growth in the US It will reinforce its ability to attract and retain top talent, foster deeper connections with agents and clients, and enhance product innovation and service quality. Safety will operate within Mapfre and maintain the unique strengths of both organizations.</p>

<p><strong>Jaime Tamayo, CEO of Mapfre North America, stated: </strong>This is an exciting milestone that brings together two leaders in Massachusetts with a shared commitment to excellence. Safety has an exceptional team, a strong brand, and a deep understanding of the local market, making it an ideal partner. As a larger organization, we have the ability to unlock greater value, broader capabilities, and new opportunities for growth&mdash;while remaining deeply focused on the people who define our success. I look forward to incorporating Safety&rsquo;s high-quality franchise into Mapfre USA&rsquo;s operations. Safety&rsquo;s solid underwriting track record, servicing capabilities and agent network will enhance our product offerings and improve the customer experience of our clients and agents throughout the Northeast. This combination will definitely reinforce our commitment to agents and clients throughout the Northeast while providing enhanced opportunities for our employees.</p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/mapfre-to-acquire-the-safety-insurance-group-for--1-54bn-26968.htm</link>
<pubDate>Fri, 24 Jul 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Dwp Roadmap Highlights Pace And Scale Of Reform</title>
		<description><![CDATA[<div>According to Lumerathe roadmap highlights both the speed and scale of change required across the pensions industry, giving providers and trustees a clear view of when they need to be ready for reforms that will fundamentally change how disengaged members are supported.</div>

<div> </div>

<div><strong>The data has consistently shown that consumer engagement with pensions remains low.</strong></div>

<div>DWP research on DC pension decumulation released ahead of the roadmap, found that most of the respondents - aged 53-67 - understood that DC pots were invested but only a few actively engaged with investment decisions. Knowledge of products, fees and investment risk was generally low, with many struggling to differentiate between access routes or assess long-term implications.</div>

<div> </div>

<div>Separate DWP analysis found that three quarters (77%) of DC pension holders aged 40-75, yet to access their pension, did not have a clear plan on how to do this, and a fifth (21%) were not even aware they had to make a choice.</div>

<div> </div>

<div>This has driven a significant change in policy direction, with reforms increasingly focused on ensuring better outcomes for members who are unlikely to make active decisions about their retirement.</div>

<div> </div>

<div>While it represents a new and overdue focus for pensions policy, it also creates entirely new challenges for delivery. A key example of this is Guided Retirement, which will see disengaged members assigned to default retirement options that are assessed to be the most suitable for them.</div>

<div> </div>

<div>It means decision makers, such as trustees, will need to use the data they hold on their members, which is usually quite limited, to justify why a member is placed on a specific pathway. This means the industry will need to develop new approaches to governance, data management and technology-enabled decision making to ensure decisions are robust, transparent and made in members&rsquo; best interests.</div>

<div> </div>

<div>This is one of the areas where the use of AI may come to be seen as a necessity to evidence that the best approaches available are being used to translate this limited member data into justifiable assignments to default pathways, and to update the approaches based on future data on how these members actually behave as they transition into retirement.</div>

<div> </div>

<div>The new timeframe for Guided Retirement to be introduced in 2029 not only allows for the development of a robust regulatory framework for this reform, but also enables time for the establishment of regulatory guidance around the use of AI to support it.</div>

<div> </div>

<div>While the Pensions Act 2026 introduced Guided Retirement in the trust-based market, the updated roadmap confirms that the FCA will also produce a discussion paper on implementing an equivalent approach for contract-based pensions, potentially further expanding its scope across the sector.</div>

<div> </div>

<div><strong>Maurice Titley, Commercial Director, Data & Dashboards at Lumera, commented:</strong> &quot;The DWP&rsquo;s updated roadmap provides a clearer path for DC pension reform, giving providers and trustees greater visibility on when they need to be ready for some of the biggest changes the industry has seen in recent times.</div>

<div> </div>

<div>&ldquo;This next phase of reform will require providers and trustees to make increasingly complex decisions on behalf of members at scale. New initiatives like Guided Retirement will therefore be a tough test of the industry&rsquo;s ability to manage data and implement strong governance frameworks that can deliver for their members.</div>

<div> </div>

<div>&ldquo;Providers will need to demonstrate that default pathways are being designed and allocated using the best available information to maintain trust, with AI set to play an important role in helping schemes make more informed decisions on behalf of their members.</div>

<div> </div>

<div>&ldquo;This updated roadmap starts the clock for providers and trustees. The priority now is to build the data capabilities, technology infrastructure and system processes that are required to deliver these reforms effectively.&rdquo;</div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/dwp-roadmap-highlights-pace-and-scale-of-reform-26965.htm</link>
<pubDate>Fri, 24 Jul 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>State Pension Alone Will Not Bring A Comfortable Retirement</title>
		<description><![CDATA[<div>The Office for Budget Responsibility (OBR)&rsquo;s latest &lsquo;Fiscal risks and sustainability&rsquo; report estimates that state pension spending will rise from its current rate of 5% of GDP to around 9% by 2075/76.</div>

<div> </div>

<div>The projected increase is driven by the cost of triple lock uprating and an ageing population which will become older over the long term, with the median age expected to rise from 40 to 49 in the next 50 years.</div>

<div> </div>

<div>Long-term spending policy assumptions in the report reflect future planned increases to the state pension age.</div>

<div> </div>

<div>Earlier this year the state pension age increased to 67, impacting anyone born on or after 6 April 1960. While the next legislated rise to 68 was set for 2044 to 2046, the report states that the current policy position is to bring this forward to 2037 to 2039.</div>

<div> </div>

<div><strong>Stuart Price, Partner and Actuary at Quantum Advisory, said:</strong> &ldquo;The OBR&rsquo;s latest report brings into question the sustainability of the state pension in its current form. Workers&rsquo; national insurance contributions pay the state pension for current pensioners but as people live longer and spend more time in retirement, the ratio of workers to pensioners is diminishing. Since 2000, the number of people receiving the state pension has increased by 40% and will increase by a further 40% by 2050.</div>

<div> </div>

<div>&ldquo;Either the state pension age will need to continue to increase, taxes will need to increase, or the amount of state pension will need to reduce &ndash; or a combination of these measures would have to be undertaken &ndash; for the state pension to remain sustainable. We are already seeing the government use the lever of raising the state pension age, with the timing of future rises potentially being accelerated.</div>

<div> </div>

<div>&ldquo;The triple lock will be retained for now, with the new Prime Minister Andy Burnham reaffirming Labour&rsquo;s manifesto commitment. Although the policy has played an important role in supporting pensioner incomes and getting many out of poverty, it is also a major driver behind the projected increase in state pension spending.</div>

<div> </div>

<div>&ldquo;Instead, the government has focused on reforms to workplace pensions in the Pension Schemes Act in a bid to deliver better outcomes for savers and pensioners. The impact of these reforms will be important as the state pension only provides around 20% of average earnings. This means private pension saving remains crucial for individuals to retire at a reasonable age with a decent level of income.&rdquo;</div>

<div> </div>

<div>In addition to the measures set out in the Pension Schemes Act, pensions professionals are calling for the expansion of the auto-enrolment system.</div>

<div> </div>

<div>The Society of Pension Professionals (SPP) is urging the second Pensions Commission, which aims to review adequacy in retirement outcomes and the barriers affecting people from saving enough for retirement, to introduce an equivalent system to auto-enrolment for the self-employed in particular.</div>

<div> </div>

<div><strong>Price said: </strong>&ldquo;One of the ways we can increase the amount we retire with is through increasing auto-enrolment contribution rates and introducing the format, or equivalent systems, for those who currently do not fall into the scope for auto-enrolment like the self-employed or younger employees.</div>

<div> </div>

<div>&ldquo;The Pensions (Extension of Automatic Enrolment) Act 2023 has granted the government the powers to reduce the minimum age to 18 and remove lower earning limits which is step in the right direction, but is yet to be implemented.</div>

<div> </div>

<div>&ldquo;Even for those savers already benefitting from auto-enrolment, the current minimum total contribution of 8% of a salary is not enough to provide savers with a comfortable retirement. Increasing the total contribution rates to at least 12% could make a significant difference in driving up pension savings.&rdquo;</div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/state-pension-alone-will-not-bring-a-comfortable-retirement-26966.htm</link>
<pubDate>Fri, 24 Jul 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Collective Defined Contribution  Learning From The Dutch</title>
		<description><![CDATA[<p><strong>By Dr. Roel MehlkopfSenior Client Adviser, Cardano</strong></p>

<div><strong>The essence of Dutch pensions</strong></div>

<div>In common with the UK, Dutch occupational pensions are complex and a challenge for participants and experts to understand. In essence, the Dutch system reflects an attempt to maintain some protections for members when making the switch away from DB to DC. Those familiar with the UK government&rsquo;s CDC plans will recognise features of the Dutch system in the Government&rsquo;s plans, in particular the plan to introduce Retirement-only CDC schemes from 2028.</div>

<p>Looking at two key features that distinguish Dutch &lsquo;solidarity&rsquo; DC schemes from traditional UK occupational DC schemes:</p>

<div><strong>Contributions at DB-like levels</strong></div>

<div>In &lsquo;solidarity&rsquo; DC schemes the contribution rates are set at a similar level to DB, so whilst the Netherlands has moved away from sponsor guarantees it has done so without the sharp decline in contribution levels typically seen in the UK. Dutch unions have strongly prioritised adequate contribution levels in the negotiations with employers, who in turn were happy to be fully relieved of pension risk. Moreover, Dutch pensions are paternalistic: there is typically no individual choice for employees about the contribution level, nor is there an opt-out.</div>

<div> </div>

<div><strong>The payout phase is a &lsquo;collective variable annuity&rsquo;</strong></div>

<div>Dutch DC pensions are lifelong, in striking contrast with many other countries, where the switch from DB to DC has been accompanied by a shift towards drawdowns and lump sums. The Dutch, however, have kept the DB tradition of lifelong pensions, which avoids the key risk of members running out of money if they live longer than expected.</div>

<p>In Dutch schemes, DC pots are automatically converted at retirement into a &lsquo;collective variable annuity&rsquo;. This is a collective pool of all retirees, where all risks are shared, including longevity risks and financial risks, which allows for post-retirement investment in return-seeking assets. </p>

<p>The collective variable annuity is offered within the same fund as the accumulation phase. Hence no assets must be liquidated at the conversion date, which facilitates the use of private and illiquid assets. </p>

<p>The risk exposure of the collective variable annuities is typically an allocation of 30% to 55% towards a diversified return portfolio. The risk level is determined at cohort-level by participants, via a &lsquo;risk preference survey&rsquo;.</p>

<div><strong>Lessons learned</strong></div>

<div> </div>

<div>1. The Netherlands has moved away from using the DB building blocks. Initial proposals for &lsquo;defined ambition&rsquo; schemes were based on giving workers a pension entitlement in the form of a &lsquo;deferred variable annuity&rsquo; and calculating the value of these liabilities with the use of a long-term discount rate. However, this triggered a fierce intergenerational debate between the elderly (who pleaded for a high discount rate to boost current benefit levels) and the young (who feared pension assets would be depleted in the long term with the use of a high discount rate). The intergenerational debate was intense and was not resolved. Eventually, the Netherlands switched to individual pension pots in the accumulation phase.</div>

<div> </div>

<div>2. The Netherlands has devised various &lsquo;safeguards&rsquo; (or &lsquo;buffers&rsquo;). In particular, Dutch pensions feature a &lsquo;solidarity reserve&rsquo; which covers first losses if the investment returns in the collective variable annuity are below expectations. This solidarity reserve is a relatively small percentage (typically 3-5%) of the total assets of a pension fund. The use of the solidarity reserve smooths experience and drastically reduces the annual probability of pensions in payment being reduced. This has helped the Dutch government to defend accusations from the opposition that the new Dutch system is a lottery. However, the new system is still not very popular: it receives a score of 6 (on a scale from 1 to 10) in Dutch public opinion polls. </div>

<div> </div>

<div><strong>Reflecting on the changes</strong></div>

<div>Ironically, Dutch pensions are domestically unpopular whilst being internationally ranked &lsquo;best&rsquo; in the world. The Dutch have not forgotten their gold-plated DB system, but long-term demographic trends made the switch from DB to DC inevitable. The government and pension professionals are generally of the opinion that Dutch pensions have transitioned to DC in an intelligent way, by maintaining some of the strengths of DB. The general public, however, is not yet convinced and will likely draw conclusions from how the system copes with changing and potentially turbulent economic conditions in the coming years. Contact a consultant to discuss CDC from a UK perspective</div>

<p> </p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/collective-defined-contribution--learning-from-the-dutch-26964.htm</link>
<pubDate>Thu, 23 Jul 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Torsten Bell Stays On As Pensions Minister </title>
		<description><![CDATA[<div><strong>David Brooks, Head of Policy at Broadstone, commented:</strong>&ldquo;Given the significant pensions policy agenda currently flowing through the Pension Schemes Act alongside other reforms, it is pleasing to have continuity for the sector.</div>

<div> </div>

<div>&ldquo;There is a big opportunity &ndash; through the expansion of CDC, unlocking surplus capital and delivering pensions dashboards to name just a few &ndash; to make a tangible difference to workers, savers, providers and UK plc.</div>

<div> </div>

<div>&ldquo;Pension policy is a long-term game which needs focus and consistency to ensure the current reforms are implemented in a way that will deliver a sustainable, trusted retirement savings framework for the millions who depend on it in later life.&rdquo;</div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/torsten-bell-stays-on-as-pensions-minister--26958.htm</link>
<pubDate>Thu, 23 Jul 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Standard Life Completes  260m Buy in With Reassure</title>
		<description><![CDATA[<div>The transaction, which completed in June 2026, covers approximately 1,500 deferred members and around 1,250 pensioners and dependants.</div>

<div> </div>

<div>ReAssure, a life and pensions consolidator, was acquired by Standard Life (formerly Phoenix Group) in 2020. Standard Life has worked closely with the Trustee and its advisers in the period leading up to the transaction to support a well-aligned outcome for the Scheme and its members.</div>

<div> </div>

<div>Mercer acted as risk transfer adviser to the Trustee, with legal advice provided by Gowling WLG.</div>

<div>This buy-in represents an important step in the Scheme&rsquo;s journey to secure members&rsquo; benefits over the long term.</div>

<div> </div>

<div><strong>Emma Haylock, PRT Transaction Manager at Standard Life, said: </strong>&ldquo;Reaching this stage reflects the close collaboration between the Trustee, sponsor and advisers over several months. By working together with a shared focus on achieving the right outcome, we&rsquo;ve been able to support a transaction that strengthens long-term security for all members. This is a positive step forward for the Scheme and its future.&rdquo;</div>

<div> </div>

<div><strong>Chris Martin, IGG, Chair of Trustee said:</strong> &ldquo;I&rsquo;m delighted that we have successfully completed this buy-in, which insures the benefits of all our members. This was a complex project and I am grateful for Standard Life&rsquo;s support in achieving this outcome. I also want to thank the whole trustee board and our excellent advisers, Mercer, Gowling WLG, WTW and Gallagher for their role throughout the process in scoping and executing the transaction. Member experience has been at the forefront of our mind throughout this process and Standard Life have demonstrated their alignment and commitment in this respect&rdquo;.</div>

<div> </div>

<div><strong>Andrew Ward, Partner and Head of Risk Transfer at Mercer, said:</strong> &ldquo;We worked closely with the Trustee and Standard Life on this transaction. The Scheme&rsquo;s relationship with Standard Life made for a particularly interesting process. This required due diligence and strong governance from the Trustee, resulting in an excellent outcome for members and helping to secure their benefits for the long term. The strength of the collaboration between the Trustee and Standard Life was central to achieving a strong package with residual risk cover.  This acknowledged the individual Scheme&rsquo;s circumstances giving the Trustee confidence in the outcome achieved.&rdquo;</div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/standard-life-completes--260m-buy-in-with-reassure-26960.htm</link>
<pubDate>Thu, 23 Jul 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Db Pension Schemes Maintain Strong Surplus Positions</title>
		<description><![CDATA[<p>As of 30 June 2026, PwC estimates that UK DB schemes held assets totalling &pound;1,110 billion against liabilities of &pound;900 billion on a low dependency measure. This represents a surplus of &pound;210 billion and a funding ratio of 123%, maintaining the robust funding position seen over recent months despite continued economic uncertainty and market volatility.</p>

<p>Meanwhile, PwC's Buyout Index, which tracks the estimated cost for UK defined benefit pension schemes to fully insure their liabilities through an insurance buyout, showed an estimated surplus of &pound;155 billion, with schemes totalling an aggregate position of 116% funded.</p>

<p>PwC's Superfund Index also remained robust, with an estimated surplus of &pound;220 billion and a funding level of 125%, highlighting the continued strength of alternative endgame solutions.</p>

<p>This strength has been consistent throughout 2026, with low dependency and buyout measure consistently exceeding 120% and 110% respectively, alongside a general upwards trend.</p>

<p><strong>Saye Mkangama, Pensions Partner at PwC UK, said: </strong>&quot;With funding levels remaining strong, the government's surplus release consultation marks an important step towards making surplus release a practical option for well-funded schemes. That greater clarity is already influencing market sentiment, with around two-thirds of trustees, sponsors and industry professionals responding to PwC polling saying the consultation and The Pensions Regulator's (TPR) statement have increased their confidence in running on schemes and releasing surplus.</p>

<p>&quot;The focus now turns to translating that confidence into action. Government and TPR have an opportunity to create a practical framework that gives trustees and sponsors the certainty to make informed decisions while maintaining appropriate member protections. If achieved, the new flexibilities could allow well-funded schemes to put surplus capital to more productive use without compromising members' security.&quot;</p>

<p><strong>The PwC Low Dependency Index, Buyout Index and Superfund Index figures are as follows: </strong></p>

<p><img alt="" src="https://www.actuarialpost.co.uk/images/pic_PWCIndex2307261.jpg" style="height:685px; width:495px" /></p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/db-pension-schemes-maintain-strong-surplus-positions-26959.htm</link>
<pubDate>Thu, 23 Jul 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Ftse100 Slips  Energy Fears And Ai Spending Sparks Caution</title>
		<description><![CDATA[<p><strong>Susannah Streeter, Chief Investment Strategist, Wealth Club: </strong>&ldquo;Investors are in a wary mood, with London's FTSE slipping into the red in early trade, as fresh jitters of worry about the ongoing energy crunch hit sentiment. Brent crude has barrelled above $97, heading towards the $100 mark, as escalating Middle East tensions raise the risk of deeper supply disruptions and threats to vital energy arteries including the Strait of Hormuz.</p>

<p>Iran appears to have pulled the Houthis back into the toxic geopolitical mix, with the Iran-backed group claiming it attacked two Saudi oil tankers in the Red Sea with drones and missiles. The strikes, if confirmed, would mark the first since the Houthis announced a maritime embargo against Saudi Arabia, opening another potential front in the conflict. It comes as the US carried out its 12th consecutive night of strikes on Iranian targets, while President Trump warned Washington would target Iranian infrastructure if ships were attacked in the Strait of Hormuz.</p>

<p>With both the Strait of Hormuz and the Red Sea now under increasing pressure, markets are bracing for the possibility that the conflict could disrupt key energy routes, keep oil prices elevated, and the prospect of interest rate hikes in focus.</p>

<p>easyJet has flown through some fierce turbulence with profits taking a nosedive, but shares are cruising higher today as investors spy resilience, amid the ongoing takeover story. Third-quarter profits plunged 70% to &pound;85 million as the Middle East conflict sent fuel costs soaring and knocked travellers' confidence, but demand didn't disappear, it simply arrived later, with holidaymakers waiting until closer to departure to book, lured by attractive fares.</p>

<p>Investors also seem to be encouraged by the continued momentum in easyJet Holidays, which is proving to be much more than a useful sidekick to the airline. Customer numbers grew 8%, and profits rose 7% on a constant currency basis. It's increasingly becoming the group's profit engine, delivering higher-margin revenues at a time when the core flying business is battling volatile fuel costs and geopolitical disruption. As more travellers opt for package holidays, easyJet is earning a bigger slice of customers' travel budgets, helping smooth some of the bumps that have traditionally made airline earnings so unpredictable. And the company has big ambitions for this part of the business, targeting &pound;590 million in pre-tax profit by 2030.</p>

<p>Above all of this looms the bid for the airline by private equity giant Apollo, and investors may be buying into the possibility that there could be another chapter to the takeover story. Apollo's interest has highlighted the airline's strategic value, and although tougher EU scrutiny over foreign ownership clouds the path to a deal, investors don't appear to be ruling out another twist, and potentially another approach from rival bidder Castlelake. Until there's greater clarity on whether Apollo can navigate the regulatory turbulence, or whether another bidder could emerge, takeover speculation and the prospect of further corporate interest still appear to be providing investors with a fresh tailwind.</p>

<p>Shares in pub operators haven't benefited from a Burnham bounce, despite the Prime Minister's announcement of a 20% cut to business rates for night-time hospitality businesses.  Wetherspoon's shares continued their descent, with investors still reeling from yesterday's downbeat update. Fresh clouds have also scuttled over the sector after Mitchells & Butlers, the owner of brands including Harvester, Toby Carvery, All Bar One and Miller & Carter, warned that the recent heatwave dented food sales. The hot weather has been a bittersweet brew, filling beer gardens but emptying dining tables, with customers choosing another round rather than another course. While that kept drinks sales flowing, it was a less profitable sales mix as food serves up the fatter margins.</p>

<p>Given operators had been calling for much steeper relief, such as a cut in VAT from 20% to 9%, bringing the UK more into line with European peers, today's measures look more like a small top-up than a game-changing pint of support. Investors are also mindful that hospitality businesses continue to grapple with higher wage bills, elevated National Insurance contributions and stubborn input costs, all of which continue to squeeze margins. Another headache is brewing with crude oil prices climbing again, raising the prospect of higher transport, logistics and energy costs filtering through supply chains in the months ahead. That threatens to pile further pressure on margins at a time when operators are already finding it difficult to pass higher costs on to increasingly value-conscious consumers. So, while the business rates cut is a welcome gesture, it's not enough to dispel concerns about the sector's longer-term profitability. Far from providing bubbles of cheer, today's announcement has had a flat response.</p>

<p>Wall Street is set to open lower, as tense geopolitics and inflation worries collide with concerns that the AI spending boom could be running way ahead of returns. Alphabet&rsquo;s results highlighted the vast infrastructure race under way, with the Google owner lifting its 2026 capital expenditure plans to as much as $205bn as it pours money into data centres and AI capacity.</p>

<p>The company&rsquo;s results highlighted that AI remains a huge growth opportunity but also increasingly a source of investor anxiety. Google Cloud revenue surged 82% year-on-year, but investors baulked at the sheer scale of the spending required to stay ahead in the AI arms race, with shares slipping in after-hours trading. There are growing concerns that the returns from these vast investments won&rsquo;t arrive quickly enough, or be large enough, to justify the eye-watering costs.&rdquo;</p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/ftse100-slips--energy-fears-and-ai-spending-sparks-caution-26961.htm</link>
<pubDate>Thu, 23 Jul 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Retirement On Hold</title>
		<description><![CDATA[<p>Over a third (36%) of people in their 60s who have not yet retired say they will need to work longer as a direct result of the State Pension age rise, according to new research from the Standard Life Centre for the Future of Retirement. </p>

<p>The research also finds that nearly two in five (38%) of 60-65-year-olds are working for longer to cover day-to-day expenses, showing that financial pressures are a major factor behind the increase in later-life working, alongside those who continue working by choice.</p>

<p>And these figures may increase if reported plans to raise the State Pension Age to 68 more quickly are implemented. Currently it is due to gradually rise to 68 between April 2044 and April 2046, affecting those born between April 1977 and April 1978.</p>

<p>However, the possibility of an acceleration of in SPA rises was highlighted after reports that Treasury officials have told the Office for Budget Responsibility (OBR), the government&rsquo;s fiscal forecaster, that the &ldquo;current policy&rdquo; is to bring the increase in the retirement age forward by at least seven years, to 2037.</p>

<p>This comes against a backdrop of widespread under-saving in the UK, with over 15 million people not saving enough for retirement.</p>

<p><strong>Catherine Foot, Director of the Standard Life Centre for the Future of Retirement, comments:</strong> &ldquo;Working later in life can offer real financial and social benefits, particularly when it reflects personal choice. Yet for many people, this isn&rsquo;t a lifestyle decision but a financial necessity. Millions across the UK are unable to retire when they want, underlining the challenge of retirement adequacy and the need for longer working lives just to bridge the gap.&rdquo;</p>

<p>Following the State Pension age starting to rise to 67 in April, over a third (37%) of 60-65-year-olds who are still working say they are delaying retirement until they can receive the State Pension, with the State Pension comprising a significant proportion of most people&rsquo;s retirement incomes. Previous Standard Life research also found that one in six (16%) retirees have either gone back to work (8%) or are thinking of doing so (8%)3, as the inadequacy of their retirement finances becomes clear.</p>

<p>These findings underline the growing pressure on retirement plans. While the Pensions Commission&rsquo;s interim report highlights the need for longer working lives, it also makes it clear that the system must adapt to modern, more flexible ways of working if this is to be fair and achievable.</p>

<p><strong>Catherine Foot continues:</strong> &ldquo;To make working in later life as accessible as possible, we need expanded, age-tailored careers support, alongside better flexible work arrangements and improved access to in-work health support. However, many will not be able to continue working, even with better support. This is particularly true for those with long-term health conditions and unpaid carers, who are financially disproportionately affected by the rise in State Pension age. Alongside improving wider pensions adequacy, the government must set out a clear plan to ensure the most vulnerable are supported before and during retirement, mitigating the negative impact of further changes to the State Pension age on their financial security.&rdquo;</p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/retirement-on-hold-26962.htm</link>
<pubDate>Thu, 23 Jul 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Five Pension Questions The New Prime Minister Must Answer</title>
		<description><![CDATA[<div><strong>1. Will the triple lock survive until the end of Parliament?</strong></div>

<div>Andy Burnham has repeatedly recommitted to the State Pension triple lock, but reports suggest his own economic advisers view scrapping it as a straightforward way to repair the public finances. With the State Pension already costing around 5% of GDP (&pound;138bn, second only to spending on the NHS), the Office for Budget Responsibility is projecting the policy itself will cost &pound;15.5bn a year by 2029-30. The question is not whether reform is on the table, but whether the government reaches for one of the &quot;middle way&quot; options already proposed by industry figures rather than an outright manifesto U-turn. Changes here have consequences that echo across the generations and with the current economic difficulties faced by younger workers and those seeking work, the intergenerational impact arguments surrounding both keeping and dispensing with the triple lock will keep this issue at the forefront of policy debate.<br />
<em>Political risk factor: high </em></div>

<div><em>Financial implications: high </em></div>

<div> </div>

<div><strong>2. What will the government do with the Second Pensions Commission's findings?</strong></div>

<div>The Commission's interim report warned that 15 million working-age people are not saving enough for retirement, with millions saving nothing at all. Its final report isn't due until early 2027, but with the industry pressing for a path to see Auto-Enrolment minimum contributions to rise from 8% to 12%, the new Prime Minister will face early pressure to signal his intentions on adequacy reform. Reforms to bring self-employed people and other &lsquo;invisible workers&rsquo; into automatic pension saving and to address the structural barriers to pension adequacy faced by low earners, disabled people and those young people who are &lsquo;NEET&rsquo; would send a strong signal that the new government is prepared to solve these difficult and so far unaddressed imbalances that only look set to grow. These could include removing the &pound;10,000 Auto-Enrolment trigger and lowering the minimum age from 22 to 18.<br />
<em>Political risk factor: low</em></div>

<div><em>Financial implications: high </em></div>

<div> </div>

<div><strong>3. Will the Mansion House Accord turn from a promise into a reality?</strong></div>

<div>The commitment for signatory DC funds to allocate at least 10% of main default funds to private markets by 2030 remains, with half of this to be directed towards UK private markets, is for now a voluntary industry commitment rather than a legal requirement. The Pension Schemes Act includes a reserve power allowing government to mandate this allocation across master trusts and Group Personal Pensions, but it was heavily constrained during its passage through Parliament: it can only be used once and not before 2028, falls away entirely by the end of 2035, is capped to the targets set out in the Accord, and includes a carve-out allowing trustees to seek exemption where they conclude the mandated investment isn't in members' best interests. Whether this government treats that power as a genuine backstop of last resort, or comes under pressure to use it as leverage if voluntary progress on the Accord stalls, will be an early test of how it weighs pension savers' protection against its wider growth agenda. </div>

<div><em>Political risk factor: medium</em></div>

<div><em>Financial implications: high </em></div>

<div> </div>

<div><strong>4. Will pension tax relief reform be back on the table?</strong></div>

<div>Flat-rate pension tax relief has resurfaced at almost every fiscal event of the last decade. With limited room to raise income tax, NI or VAT and pressure mounting on the public finances, reform of higher rate relief remains one of the few significant revenue levers available to new Chancellor John Healey and is arguably one that risks less backlash when compared with other pension tax regime alterations. However, such a change would likely receive significant pushback given further disruption to long-term saving habits set against a backdrop of a nation of millions who already aren&rsquo;t saving enough. A transition from the current system to a flat rate would also be administratively highly complex, at a time where the pensions industry is already grappling with looming changes to Inheritance Tax (bringing unused pension pots into IHT calculations from April 2027).<br />
<em>Political risk factor: medium</em></div>

<div><em>Financial implications: medium</em></div>

<div> </div>

<div><strong>5. Will Pensions Dashboards actually reach savers on schedule?</strong></div>

<div>Scheme connection to the dashboards ecosystem remains legally required by 31 October 2026, with coverage now over 85%. But the public launch date has already slipped repeatedly, and the Money and Pensions Service has indicated the MoneyHelper dashboard is unlikely to be available to consumers before the 2027/28 financial year. After a decade of delay, the new government will need to commit to a firm public launch date, or risk the timetable drifting again.<br />
<em>Political risk factor: low</em></div>

<div><em>Financial implications: low</em></div>

<div> </div>

<div><strong>Becky O'Connor, Head of Pensions at PensionBee, said:</strong> &ldquo;Andy Burnham has come in with a stated aim of a 10-year plan, signalling a willingness to think long term. Pension policy may therefore present a natural focus. Pensions are a highly politically sensitive topic - with policy decisions having a significant impact for the Treasury and for the nation both now and for generations to come. </div>

<div> </div>

<div>&ldquo;Balancing considerations of fairness, sustainability and the central goal of better long term financial security for all requires an effort to resolve existing tensions with honesty and creativity. Where there&rsquo;s a will, there&rsquo;s a way and there may be more tools in the new leader&rsquo;s box that have not been sufficiently explored by his predecessors. Making pensions more equitable for those who are structurally disadvantaged by the current system, such as self-employed and disabled people, feels like a natural priority fit for the new Prime Minister.</div>

<div> </div>

<div>&ldquo;The Pension Schemes Act is the UK's most significant pensions shake-up in decades, and there are a plethora of key reforms and consultations already in motion as set out in the new &lsquo;Roadmap&rsquo;, so the continuity of leadership within the DWP is welcome. Given the extreme amount of changes to the pensions tax regime over recent years, taking a cautious approach and resisting the temptation to make further drastic alterations to the way pensions are taxed, without careful consideration of the impact for savers now and in the future, may be a wise approach.&rdquo;</div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/five-pension-questions-the-new-prime-minister-must-answer-26963.htm</link>
<pubDate>Thu, 23 Jul 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Retail  Leisure And Hospitality  Cutting Out Ai Fraud Claims</title>
		<description><![CDATA[<p><strong>By Teresa Long, Industry Leader &ndash; Retail, Leisure and Hospitality for GB Risk and Broking, WTW</strong></p>

<div><strong>How is AI driving heightened fraud risk for retail, leisure and hospitality businesses?</strong></div>

<div>AI is helping fraudulent claimants transform what would have been a short or patchy complaint into a detailed claim, with a chronology, confident wording and realistic images that support their account. Fraudsters can produce this content in seconds, enabling high volumes of claims without substance with little demand on their time or other resources.</div>

<p>The volume and sophistication of fraudulent claims is making it harder for teams to distinguish them from genuine customer issues, particularly where retail, leisure and hospitality organisations feature busy sites, lean customer service or claims teams or high staff turnover.</p>

<div><strong>What practical steps reduce retail, leisure and hospitality organisations&rsquo; exposure to AI-enabled claims?</strong></div>

<div>Reducing your exposure to AI-enabled claims demands the &lsquo;back to basics&rsquo; discipline similar to that you might apply to traditional claims: strong reporting disciplines, training your people to identify warning signs and creating clear audit trails.</div>

<p>Your people need to know that polished wording and professional-looking images don&rsquo;t prove the facts. Frontline staff are your first line of your claims defensibility. They need clear prompts they can be ready to deploy during busy shifts or backed-up complaints queues: what happened, who saw it, what records are there?</p>

<p>Junior or transient staff may not see how a missed photo or incomplete log or can drive investigation costs, your business&rsquo; reputation and your ability to defend a claim. They may also need explicit permission to pause, check the incident log, ask for missing information or escalate to someone with claims experience.</p>

<p>Processes that are hard to access or take too long to carry out are likely to fail on a busy shop floor or hotel reception, during restaurant service or if you operate a call centre where your people are handling high volumes of complaints. Think about easy-to-use processes, clear ownership of roles and responsibilities when someone makes a claim &mdash; both on-site and online &ndash; and a route to preserving evidence and escalating cases.</p>

<div><strong>How can you review claims data to identify AI-related issues early?</strong></div>

<div>Monitor and analyse claims activity, making sure you have a process that flags warning signs, such as repeated wording or image types, unusual timings or concentrations in particular locations. You need to be able to capture unusual activity and have a process for triggering a closer review.</div>

<p>If your claims teams have a way of comparing the trends it&rsquo;s seeing with wider market experience, they&rsquo;ll be in a better position to separate isolated service issues from AI-supported.</p>

<p>Can you trace a claim from first contact to settlement, challenge or escalation. Where did it start? Who handled it first? What evidence did they capture?</p>

<p>If a location, product line or channel shows higher volumes, you may want to investigate whether poor recording, weak escalation, an operational issue or AI-supported claims activity caused the increase.</p>

<p>If you&rsquo;re facing high volumes of claims, your teams may benefit from a clear framework for triaging cases that look doubtful but lack enough evidence to justify a harder stance. This framework should help teams weigh cost, available evidence, customer experience and reputational risk consistently, ultimately saving time and resources.</p>

<div><strong>How can your organisation strengthen claims defensibility against AI-enabled fraud?</strong></div>

<div>Check smaller sites can capture the same core information as your flagship locations: date, time, place, people involved, condition of the area or product, action taken and evidence preserved.</div>

<p>Test your written procedures against recently closed incident records and claims files. Review the records, speak to the teams who created them and check whether your escalation routes are clear to the people using them. The findings from these exercises can identify practical improvements in training, forms and reporting, or give you assurance you&rsquo;re getting the basics right.</p>

<p>Get the industry specialist support you need to protect your business against AI-enabled claims. Get in touch with our retail, leisure and hospitality specialists.</p>

<p> </p>

<p> </p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/retail--leisure-and-hospitality--cutting-out-ai-fraud-claims-26956.htm</link>
<pubDate>Wed, 22 Jul 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Db Scheme Trustees Face Agenda Overload</title>
		<description><![CDATA[<p>Pensions dashboard readiness and endgame planning are the leading challenges facing defined benefit (DB) pension scheme trustees over the next 12 months, according to new research from TPT Retirement Solutions (&ldquo;TPT&rdquo;), as trustees contend with a growing set of operational, governance, investment and strategic priorities.</p>

<p>The findings have been published in the first <a href="https://www.tpt.co.uk/news-insights/db-trustee-pulse-2026/">Insight Report from the TPT Retirement Solutions: DB Trustee Pulse 2026</a>, a new series based on an independent survey of 100 UK DB pension trustees representing schemes with assets ranging in size from &pound;100m to over &pound;10bn+.</p>

<p>Pensions dashboard readiness topped the trustee agenda, cited by 38% of respondents. Evaluating endgame options ranked second and was the fast-rising priority, with 31% of trustees citing it as a major challenge, compared with 16% in 2024. Other priorities followed closely including liquidity, collateral and cashflow management (30%), staying on top of member communications and expectations (28%), and navigating market volatility / investment performance (26%), all of which ranked similarly high (see Figure One).</p>

<p>Taken together, the findings point to a broader capacity issue. Trustees are no longer contending with a single overriding challenge. Rather, they are having to deal with an increasingly crowded agenda that requires them to progress long-term strategic decisions while simultaneously meeting an ever-expanding range of operational and governance demands.</p>

<p><img alt="" src="https://www.actuarialpost.co.uk/images/pic_TPTDB2207261.jpg" style="height:314px; width:600px" /></p>

<p>Compared with TPT&rsquo;s 2024 DB Trustee Pulse Survey, some previously prominent challenges have eased. Notably, concerns around accessing different asset classes fell from 29% to 24%, while concerns over data quality declined from 21% to 16%, suggesting progress has been made in areas that previously required greater trustee attention.</p>

<div><strong>Differently sized schemes experiencing different pressures</strong></div>

<div>The research also reveals that the types of challenges faced by trustees differ by scheme size. Analysis shows that schemes with less than &pound;1bn in assets under management are more likely to flag endgame options as a challenge, cited by 42% of trustees in this category. Smaller-scheme trustees also show a greater concern around running costs, cited by 30%, and staffing capacity, cited by 26%.</div>

<p>However, for medium-to-large sized schemes with &pound;1bn or more in assets under management, pensions dashboard readiness is the most prominent challenge, selected by 39% of trustees in this category, followed by liquidity, collateral or cashflow management needs at 33%. Scheme administration, keeping pace with regulation and asset allocation all rank close behind, each cited by 26% of trustees in this group.</p>

<p><strong>Nicholas Clapp, Commercial Director, TPT Retirement Solutions, said: </strong>&ldquo;For a number of years, the industry conversation was dominated by funding, de-risking and endgame planning. Those priorities have not gone away, but there is now greater recognition of the growing practical realities trustees face in overseeing a pension scheme. Dashboards, governance, data, administration and implementation projects all compete for the same time and resource.&rdquo;</p>

<p>Katherine Lynas, Head of Consultant Relations, TPT Retirement Solutions, said: &ldquo;What we are seeing is that operational complexity is becoming a strategic issue. Trustees are evaluating endgame options while also thinking about how much governance, resource and ongoing management each route requires. That's why consolidation options that provide scale and simplicity are becoming increasingly important considerations.&rdquo;</p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/db-scheme-trustees-face-agenda-overload-26951.htm</link>
<pubDate>Wed, 22 Jul 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Inflation Cools But Escalation In Middle East And Black Sea</title>
		<description><![CDATA[<p><strong>Susannah Streeter, Chief Investment Strategist, Wealth Club: </strong>&ldquo;UK inflation has eased to 2.6% in June, with some of the heat coming out of rapidly rising prices, offering some short respite for households and pushing the threat of interest rate hikes a little further into the distance. The fall was steeper than some forecasts, but it's still above the bank's 2% target. Also, it's not likely to be long before the temperature rises again, with fresh attacks in the Middle East and the Black Sea threatening to keep prices on the boil. Brent crude has raced upwards again, to trade around $93 a barrel, the highest level in six weeks, and this snapshot of prices won&rsquo;t capture this unwelcome development. Transport costs were the biggest downward driver of the headline rate of inflation, with prices of motor fuel coming down markedly, but with oil prices becoming painfully hot again, it'll soon show up at the pumps and filter through to other consumer prices via higher freight and energy costs.</p>

<p>Core CPI, which strips out volatile food and fuel prices and is monitored closely by the Bank of England, also came in at 2.6%. Price rises for goods have slowed quite markedly, but services inflation is proving stickier, falling only a little to 2.6%, above expectations. The pound initially rose before losing ground as investors assessed the conflicting signals for interest rate policy. While the fall in the headline rate is welcome news, stubbornly high core inflation, a sluggish economy and the Middle East crisis are set to keep Bank of England policymakers on alert. However, it still looks likely they'll adopt another wait-and-see stance at the meeting later this month, with an interest rate hike not fully priced in until close to the end of the year.</p>

<p>Policymakers will be monitoring closely how the war with Iran filters through to everyday prices. Risks to supplies are mounting again, with the effective blockage of the Strait of Hormuz remaining a chokehold as tankers are stranded in and around the waterway, while risks to other crude routes are also intensifying. Both the Red and Black Seas are fast becoming the latest flashpoints. President Trump has dashed hopes for imminent talks, threatening to ramp up attacks on Iran if Houthi rebels are drawn into the conflict and begin disrupting the Red Sea route for oil shipments. As the conflict in Ukraine rages, with drone attacks on tankers serving Russia's Caspian Pipeline Consortium on the Black Sea coast, Kazakhstan has been forced to halt crude exports through the port. Both conflicts, which look increasingly intractable given the lack of momentum behind diplomatic solutions, are threatening to choke vital energy supply routes and keep a firm floor under oil prices, raising the risk that inflationary pressures flare up once again. If they drag on, this could prove to be the low point for inflation before price pressures start building again through the second half of the year.</p>

<p>The new Burnham administration is trying to build a buffer against a fresh cost-of-living squeeze amid the threat of higher prices. Following yesterday's VAT cut on household electricity bills, today's &pound;2 bus fare cap is another attempt to put money back into consumers' pockets before higher energy costs start filtering through the economy. For many households, particularly those reliant on buses to get to work, the savings will offer an immediate salve to what have become painful everyday costs. But in many ways policymakers are in a race against forces beyond their control. If conflict in the Middle East keeps oil prices simmering near recent highs, the relief offered by cheaper electricity and transport could quickly be eroded by rising fuel, freight and wider consumer costs. The cost-of-living battle may be getting a helping hand from government, but it is still likely to be fought on the global stage.''</p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/inflation-cools-but-escalation-in-middle-east-and-black-sea-26949.htm</link>
<pubDate>Wed, 22 Jul 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Dc Pension Tracker For Q2 2026</title>
		<description><![CDATA[<div>Over the quarter (January to March 2026), the Aon UK DC Pension Tracker rose, which suggests the expected future living standard in retirement provided by defined contribution (DC) savings was higher than at the end of the previous quarter.</div>

<div> </div>

<div><strong>Aon DC Tracker</strong></div>

<div><img alt="" src="https://www.actuarialpost.co.uk/images/pic_AonDCTracker12207261.jpg" style="height:356px; width:600px" /></div>

<div><span style="font-size:11px"><em>Source: Aon UK DC Pension Tracker (1 January to 31 March 2026) </em></span>                   </div>

<div> </div>

<div>Note, the sample savers used in the Aon DC Tracker were &rsquo;re-set&rsquo; to their original age and fund values at the year-end which results in the discontinuity (shown in grey in the chart above) as at 31 December 2025.</div>

<div> </div>

<div>The Tracker rose from 67.5 to 70.5 over the first quarter of 2026, driven predominantly by an increase in expected return assumptions pre-retirement and despite negative benchmark investment returns across major asset classes over the quarter.</div>

<div> </div>

<div>This has resulted in an increase in expected retirement income for all savers, though younger savers have benefited the most (in percentage terms) from the higher future return assumptions pre-retirement, unlike older members who are closer to retirement.</div>

<div> </div>

<div><strong>Savers' Positions (measured compared to the &lsquo;moderate' living standard)</strong></div>

<div><img alt="" src="https://www.actuarialpost.co.uk/images/pic_AonDCTracker22207261.jpg" style="height:440px; width:600px" /></div>

<div><em style="font-size:11px">Source: Aon UK DC Pension Tracker (1 January 2026 to 31 March 2026).</em></div>

<div>                 </div>

<div><strong>Second Pension Commission interim report highlights the scale of the adequacy challenge</strong></div>

<div>The publication of the Second Pensions Commission's interim report highlighted the scale of the UK&rsquo;s adequacy challenge, noting that around 4 in 10 of working age people are currently under-saving for retirement. While the report recognises the success of reforms introduced following the original Pensions Commission, including auto-enrolment and a strengthened State Pension, it makes it clear that significant challenges remain.</div>

<div> </div>

<div>Automatic enrolment has been one of the most successful pensions policy reforms of recent decades, transforming workplace pension participation and bringing millions more people into long-term saving. However, for many employees, the statutory minimum contribution level has become the default savings target rather than a starting point, even though evidence shows that current contribution rates are often insufficient to deliver an adequate retirement income.</div>

<div> </div>

<div>The Commission also notes that approximately 45 percent of working-age adults &ndash; around 18 million people &ndash; are not contributing to a pension at all - despite many being in employment.  It also expects that 13 percent of the working age population will not meet the Minimum Retirement Living Standard. The report also highlights persistent inequalities in retirement outcomes, with women, carers, the self-employed and some ethnic minority groups facing particular barriers to building adequate retirement savings.</div>

<div> </div>

<div><strong>Matthew Arends, partner and head of UK Retirement Policy at Aon, said: </strong>&quot;The Second Pensions Commission delivered a clear message. Getting more people saving through auto-enrolment was a major achievement, but participation alone is no longer enough. With millions of people projected to fall short of an adequate retirement income, the focus must now shift towards ensuring people save enough, for long enough, and that they can turn those savings into sustainable retirement incomes. I would hope that the Commission's findings act as a catalyst for employers, pension schemes and policymakers and that they start to address these challenges now, rather than waiting for the final recommendations.&rdquo;</div>

<div> </div>

<div><strong>Latest update to the Pensions UIK Retirement Living Standards released</strong></div>

<div>June saw the latest update to Pensions UK&rsquo;s Retirement Living Standards - this will be reflected in next quarter&rsquo;s DC Tracker. The new figures reflect an increase in everyday costs - including food, essential household bills and social activities, which have pushed up the income required across all lifestyles at retirement.</div>

<div><br />
A minimum retirement lifestyle is now up 3.7 percent to &pound;13,900 a year for a one-person household, while a moderate lifestyle costs &pound;32,700 for one person (up 3.2 percent), and a comfortable lifestyle costs &pound;45,400 for one person (up 3.4 percent).</div>

<div> </div>

<div><strong>Matthew Arends said: </strong>&ldquo;The latest Retirement Living Standards remind us that the &lsquo;finish line&rsquo; for an adequate retirement continues to move as living costs change and expectations evolve. Savers have an important - and difficult - task in understanding their own target and whether their current level of savings can get them there.&rdquo;</div>

<div><br />
<strong>Movement over the first quarter of the year</strong></div>

<div>The increase in the Aon UK DC Pension Tracker over the first quarter of 2026 was primarily driven by an increase in future expected returns pre-retirement over the period. On an individual saver basis, movements over the quarter were positive at all ages.</div>

<div><em>The youngest saver saw an increase of around &pound;1,500 p.a. (4.3 percent) driven by an increase in expected future investment return assumptions pre-retirement, offset to a degree by negative investment performance over the quarter.</em></div>

<div><em>The 40-year-old saver saw the largest increase of around &pound;1,250 p.a. (or 3.1 percent) in their expected retirement income.  Again, this was driven by a rise in post-retirement expected future returns.  These were also marginally offset to a degree by a reduction in the expected future return post-retirement and by actual investment returns over the period.</em></div>

<div><em>Our 50-year-old saver saw an increase of around &pound;650 p.a. (or 1.8 percent) in their expected retirement income. Due to this saver&rsquo;s larger existing funds, negative performance over the quarter had a larger impact. However, this was offset by increases in expected future return assumptions pre- and post-retirement.</em></div>

<div><em>The oldest saver&rsquo;s income was broadly flat (an increase of around &pound;75 p.a. or 0.3 percent). This was as a result of an increase in expected future returns pre- and post-retirement being almost entirely offset by negative investment return over the quarter.  </em></div>

<div><em>Overall, the oldest saver is expected to be the worst off in retirement, albeit with a retirement income of around 150 percent of the &lsquo;minimum&rsquo; Retirement Living Standard. This excludes any defined benefit pension benefits they may have but which are not included in this projection. </em></div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/dc-pension-tracker-for-q2-2026-26953.htm</link>
<pubDate>Wed, 22 Jul 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Mercer Investment Insights Q3 2026</title>
		<description><![CDATA[<div><iframe allow="accelerometer; autoplay; clipboard-write; encrypted-media; gyroscope; picture-in-picture; web-share" allowfullscreen="" frameborder="0" height="315" referrerpolicy="strict-origin-when-cross-origin" src="https://www.youtube.com/embed/-CCSeJkyTOU?si=Cv-gAx9dvRm19-1B" title="YouTube video player" width="340"></iframe></div>

<p> </p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/mercer-investment-insights-q3-2026-26957.htm</link>
<pubDate>Wed, 22 Jul 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>No Single Automatic Enrolment Reform Protects Low Earners</title>
		<description><![CDATA[<p>The final report in the research series, &lsquo;From Payslip to Pension: Life Course Impacts on Retirement Saving Among Low Earners&rsquo;, funded by a grant from the Nuffield Foundation, identifies that, due to the diversity of financial security and pensions adequacy risks different low earners face in working life and retirement, no single AE policy can account for all scenarios.(1)(2)</p>

<p>For low earners who spend a particularly large portion of their working life as low earners, the study states the Lower Earnings Limit (LEL) reduces their contributions to such a degree that increased minimum contribution rates are unlikely to compensate for it. For example, at age 22, low earners are projected to have a further 16 years of low earning across their working life if they are a woman, or 8 if they are a man. Other risk factors, such as low educational qualification levels or motherhood, may increase these figures further, increasing the impact of any change to the LEL. However, for other low earners who may be at risk of poverty, any contribution may be too much, and the removal of the LEL could increase their contribution significantly.</p>

<p>The research also shows how the impact of fiscal drag on AE thresholds has made its current aims unclear. Eroded by inflation since the last uprating in 2014, PPI analysis shows the Earnings Trigger is now &pound;4,300 (43%) lower in real terms, pushing employees and employers to make a greater contribution to a workplace pension. As low earners and employers face a range of cost of living and global economic pressures, the LEL is also 28% lower in real-terms, meaning a further &pound;1,750 of employees&rsquo; earnings are now subject to a workplace pension contribution since the last 2020 uprating.(3)(4)</p>

<p> The analysis notes that the real-terms decrease of AE thresholds reflects an implicit assumption that low earners will opt out if it is in their best interests to do so, in order to address immediate cost of living pressures, or other factors. This is despite the AE policy mechanisms of the Earnings Trigger and the LEL being originally designed to protect against low earners failing to opt-out of saving when potentially needed, the report states. Future AE reforms that explicitly outline assumptions about the capacity of low earners to opt-out when necessary, the assessment elaborates, would help clarify the wider policy direction.</p>

<p>The report comes as the Second Pensions Commission considers how AE might be reformed to increase pensions adequacy, with low earners highlighted as facing particularly high adequacy risks.</p>

<p><strong>Further key findings of the research series summarised in the report include:</strong></p>

<p>Saving may present immediate risks to low earners who are at risk of poverty, in debt, or in precarious or unstable employment. Even relatively small contributions under current AE policy may exacerbate hardships, and some AE reforms may increase these contributions.</p>

<p>Many individuals will spend a significant portion of their career as low earners, so any periods of higher earnings are unlikely to provide sufficient savings for their retirement. For example, in the case of an 18 year old low earning woman who does not achieve qualifications higher than a GCSE, she is projected to spend 22 years as a low earner across her working life.(5)(6)</p>

<p>Some potential new policies may benefit persistent low earners, such as non-contingent employer contributions, or sidecar savings. Non-contingent employer contributions would see an employee enrolled in a pension scheme, receiving employer contributions, without having to reduce their own take home pay. Sidecar savings create a mechanism by which pension contributions would be paid in to a separate, accessible savings account first, and only when this account reached a certain size, would they be paid into a conventional, harder-to-access pension pot.</p>

<p><strong>John Upton, PPI Policy Analyst and lead author of the research series, commented:</strong> &ldquo;Automatic enrolment started with the assumption that low earners may not opt out by themselves and needed a degree of protection, but this assumption appears to be shifting: they are excluded from Automatic Enrolment to a degree, but as thresholds reduce with inflation, more people are gradually brought into scope. As the Second Pensions Commission seeks to improve pensions adequacy, highlighting low earners as a high risk group, it will need to find the delicate balance between working life living standards and retirement living standards for low earners. As no single policy reform may fully counter all risks, it may be necessary to make the assumptions around the capacity for saving and opting out more explicit, so that extra protections for at-risk groups may follow.&rdquo;</p>

<p> </p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/no-single-automatic-enrolment-reform-protects-low-earners-26954.htm</link>
<pubDate>Wed, 22 Jul 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Comments On Inflation Boost For The New Pm</title>
		<description><![CDATA[<div>Mike Ambery, Retirement Savings Director at Standard Life plc said: &ldquo;Today&rsquo;s fall in inflation to 2.6% is no doubt a welcome boost to Andy Burnham and his new chancellor John Healey, particularly after concerns that price pressures could remain stubbornly high. However, it's too early to assume inflation is now on a steady downward path. July's energy price cap increase has yet to feed through into the data, while ongoing global uncertainty and the new government's spending decisions could still influence the outlook over the coming months. With this in mind, today's figures are unlikely to be enough on their own to trigger a Bank of England rate cut. Policymakers are expected to keep rates on hold next week and will want greater confidence that inflation is moving sustainably back towards the 2% target before changing course. This uncertainty is already feeding through to borrowers, with mortgage rates rising in recent weeks as lenders reassess the outlook for inflation and interest rates. For households and those planning for retirement, it&rsquo;s important to remember that lower inflation does not mean prices are falling, they are simply rising more slowly. The joint impact of higher food, energy and everyday costs can still make long-term saving feel difficult. Pension contributions may seem like an obvious place to cut back, but pausing can mean missing out on employer contributions, tax relief and potential investment growth. Therefore, where affordable, it&rsquo;s important to stay engaged with your pension, review what you are paying in and maintain or even increase contributions when circumstances allow, all of which can help people build greater financial security over time.&rdquo;</div>

<div> </div>

<div><strong>George Brown, Senior Economist at Schroders, said: </strong>&quot;Lower fuel prices applied the brakes to inflation in June, but this rear-view mirror picture doesn't tell us much. With oil prices rising again amid renewed tensions in the Middle East, there could be inflation issues further down the road. For the Bank of England, the crucial question is whether this remains an energy shock or becomes a domestic inflation problem. So far, a cooling labour market suggests there is little risk of the sort of second-round effects that would warrant tighter monetary policy. That should allow policymakers to keep a steady hand on the wheel. While markets are pricing more than two rate hikes over the next year, we think the Bank can stay on hold as it gauges whether the latest energy shock is just a temporary bump in the road or something more persistent.&quot;</div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/comments-on-inflation-boost-for-the-new-pm-26950.htm</link>
<pubDate>Wed, 22 Jul 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Future Beneficiaries Banking On  essential  Inheritance</title>
		<description><![CDATA[<div>Aviva&rsquo;s new report, <a href="https://www.actuarialpost.co.uk/downloads/cat_1/Aviva-The-intergenerational-wealth-shift-2026.pdf"><strong>The Intergenerational Wealth Shift Report</strong>,</a> reveals a widespread reliance on inheritance among younger generations, but a lack of communication between families about expectations and plans and little understanding of the amount of money they may receive.</div>

<div> </div>

<div>The study has found 37% of people who expect to inherit saying they are financially dependent on it, and 43% saying it is essential to their financial security. However, more than half of these people (60%) say they don&rsquo;t know how much they will receive.</div>

<div> </div>

<div>This raises concerns that many households could be making important financial decisions based on assumptions, particularly where inheritance is expected to help pay for everyday living costs, clear debts and fund their own retirement.</div>

<div> </div>

<div>Demographic and societal changes mean that younger generations face rising housing costs, higher savings challenges and increasing pressure on household finances. As wealth passes between generations, inheritance is becoming a more important part of many peoples&rsquo; financial plans.</div>

<div> </div>

<div>More than half (54%) of the people in the survey are comfortable discussing their plans for inheritance with their families, However, almost the same number (53%) said their family did not need to know how much they would receive - suggesting they might not appreciate the reliance being placed on inherited wealth.  Despite saying they are comfortable with discussing plans, more than half of people with children (51%) have not had discussions on this subject with their beneficiaries, but 31% do say they plan to.</div>

<div> </div>

<div>Demographic changes, such as blended families, are driving the importance of clarity of communication. Younger people are more likely to say they are reliant on receiving an inheritance than older people: 41% of under-45s compared to 32% of over-45s. They are also more likely to challenge a will if they felt it was unfair: 16% of under-45s compared to 9% of over-45s. It could be they feel there is more at stake since many younger people might not have built up their own wealth. With greater propensity to challenge a will, it is important that inheritance plans are clear and expectations well-managed.</div>

<div> </div>

<div>The lack of communication could be driven by uncertainty about future financial needs and how much money people might need to support themselves in their retirement. More than three in five (61%) don&rsquo;t know how much money they might have left and more than half (53%) don&rsquo;t know how much they might need to support themselves. Typically, money goes across generations before it goes down. Over half (59%) plan to leave all their estate to their partner and a further 19% will leave it to a combination of partner and children. Additionally, where people have already received an inheritance from their spouse or partner, almost two-thirds (63%) inherited the entire estate.</div>

<div> </div>

<div><strong>Lorna Whalley, Director of Aviva&rsquo;s Adviser Platform, believes these findings demonstrate the importance of getting later life planning in order, saying: </strong>&ldquo;There&rsquo;s a crucial role for financial advisers within inheritance and estate planning discussions, which goes beyond simply putting the mechanics in place. While recognising that situations can change, financial advisers can encourage clients to consider the levels of income they will need in retirement and what contingencies need to be in place.  More than half of people say they don&rsquo;t know how much money they will need to support themselves through retirement. This is an important step in helping people to avoid either helping family out to the detriment of their own financial security or thinking they might need more money than they actually do. A clear understanding of your financial situation and future needs is the building block for open conversations about inheritance and expectations.&rdquo; </div>

<div> </div>

<div>Those who say an inheritance is essential to their financial security are planning to use the money for ordinary expenditure, rather than big-ticket or luxury items. The most common essential use of the inheritance money is for funding day-to-day expenses (35%). Almost a third (32%) of people say inheritance money is essential for funding their own retirements, while 29% intend to pay off debt, and 27% will pay off their own mortgages. </div>

<div> </div>

<div><strong>What will your inheritance be essential for?</strong></div>

<div>Day-to-day expenses &ndash; 35%</div>

<div>Fund own retirement &ndash; 32%</div>

<div>Pay off debt &ndash; 29%</div>

<div>Pay off mortgage &ndash; 27%</div>

<div>Fund a house move &ndash; 24%</div>

<div>For own or children&rsquo;s education &ndash; 20%</div>

<div> </div>

<div><strong>Lorna Whalley continued: </strong>&ldquo;People are relying on inherited wealth to fund essential parts of their lives, but many have no idea how much they are likely to receive. This uncertainty could prove disastrous for future financial plans and makes it much harder to take steps now to meet future requirements. Advisers have an important role in facilitating conversations between clients and their families to help ensure expectations are better understood.&rdquo;</div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/future-beneficiaries-banking-on--essential--inheritance-26952.htm</link>
<pubDate>Wed, 22 Jul 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Global Mutual Insurance Hits Record  1 61tn In Premiums</title>
		<description><![CDATA[<p>The report provides the most comprehensive assessment of the global mutual and cooperative insurance sector, drawing on data from more than 4,700 mutual insurers across 80 countries and territories.</p>

<p>The findings show that mutual and cooperative insurers continue to strengthen their position within the global insurance industry, achieving the highest premium volume ever recorded while maintaining more than one-quarter of the worldwide insurance market.</p>

<p><strong>Key findings from the <a href="https://www.actuarialpost.co.uk/downloads/cat_1/ICMIF-Global-Mutual-Market-Share-2026.pdf">Global Mutual Market Share 2026 report</a> include:</strong></p>

<div><em>Record premium income of USD 1.61 trillion in 2024, up from USD 1.50 trillion in 2023.</em></div>

<div><em>A 26.1% share of the global insurance market, broadly unchanged from 26.0% in 2023, demonstrating the continued resilience of the mutual insurance model.</em></div>

<div><em>Total assets of USD 10.8 trillion, with investments reaching USD 9.0 trillion.</em></div>

<div><em>Approximately 856 million members and policyholders served worldwide.</em></div>

<div><em>Around 1.2 million people employed across the global mutual insurance sector.</em></div>

<p>The report highlights the continued strength of mutual insurers in many of the world's largest insurance markets. Mutual insurers hold market shares of 40% or more in countries including the United States, France and Germany, while accounting for more than one-quarter of the insurance market in 19 countries globally.</p>

<p><strong>Commenting on the findings, Liz Green, CEO of ICMIF, said: </strong>&quot;At a time when trust is increasingly hard won, these findings demonstrate why mutual and cooperative insurers continue to be trusted to deliver for their members, customers and communities.</p>

<p>&ldquo;The record premium income achieved in 2024 is not simply a measure of financial performance. It reflects the enduring strength of a business model built on member ownership, long-term stewardship and service rather than short-term shareholder returns. Mutual insurers continue to demonstrate that commercial success and social purpose go hand in hand.</p>

<p>&ldquo;In an environment shaped by economic uncertainty, technological disruption and changing customer expectations, the mutual sector continues to adapt, innovate and grow while remaining focused on creating long-term value for the people and communities it serves.&quot;</p>

<p>While the report highlights the sector's continued strength in established insurance markets, it also points to significant opportunities for mutual and cooperative insurers to expand their presence in emerging markets, where mutual insurance currently represents just 3.0% of total insurance premiums.</p>

<p><a href="https://www.actuarialpost.co.uk/downloads/cat_1/ICMIF-Global-Mutual-Market-Share-2026.pdf">The Global Mutual Market Share report</a> is published annually by ICMIF and is recognised as the leading source of comparative data on the size, performance and contribution of the global mutual and cooperative insurance sector. Alongside market share analysis, the report examines premium income, assets, employment, membership and policyholder data across life and non-life insurance markets worldwide.</p>

<p> </p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/global-mutual-insurance-hits-record--1-61tn-in-premiums-26955.htm</link>
<pubDate>Wed, 22 Jul 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Aon Appoint Brian Fomby As North America Md Of Pathwise</title>
		<description><![CDATA[<div>Reporting to <strong>Van Beach, global head of life solutions in the Strategy and Technology Group</strong>, Fomby will lead the firm&rsquo;s PathWise strategy in North America, overseeing implementation programs, expanding client solutions and advancing strategic relationships. Collaborating closely with colleagues across the global life solutions team, he will oversee the design and delivery of PathWise solutions that help life and annuity insurers address complex business priorities build resilience and pursue profitable growth with greater clarity and confidence.</div>

<div> </div>

<div><strong>Beach said:</strong> &ldquo;Brian brings a strong track record of helping clients apply technology to make better business decisions. His experience will help us continue delivering value for clients and expand our offerings in this area.&rdquo;</div>

<div> </div>

<div>Aon&rsquo;s life solutions team provides actuarial advisory services that complement PathWise &ndash; the firm&rsquo;s life actuarial modelling technology &ndash; and its life reinsurance broking capabilities, delivering an integrated offering for life and annuity (re)insurers, asset managers, private equity firms and other stakeholders across the life sector.</div>

<div> </div>

<div><strong>Fomby said: </strong>&ldquo;Advances in actuarial technology are creating new opportunities for insurers to strengthen decision-making and unlock value. Clients are looking for trusted providers that translate innovation into business outcomes. I&rsquo;m excited to join the PathWise team and contribute to Aon&rsquo;s broader life capabilities.&rdquo;</div>

<div> </div>

<div>Fomby joins Aon from Milliman, where he served as a principal in its life technology solutions practice. He brings extensive experience advising clients across North America and the United Kingdom.</div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/aon-appoint-brian-fomby-as-north-america-md-of-pathwise-26947.htm</link>
<pubDate>Tue, 21 Jul 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Gender Pensions Gap In The Lgps Start Earlier  Engage Better</title>
		<description><![CDATA[<div><strong>By Julie Hammerton, Head of Hymans Robertson Personal Wealth</strong></div>

<div> </div>

<div>This matters particularly in the LGPS. The scheme has around 6.7 million members, the majority of whom are women. Based on the GPG statistics quoted in the March 2025 English and Welsh valuation reports, combined with separate analysis we have carried out for a number of Scottish funds, a gap of 47% exists across the LGPS for pensioner members (that is, for every &pound;1 paid to men, women receive 53p), and a gap of 34% for actives (for every &pound;1 paid to men, women receive 66p). </div>

<div> </div>

<div><strong>The drivers are structural and behavioural </strong></div>

<div>The causes of the gender pensions gap are well established. At a national level, the gap is driven by a combination of the gender pay gap and differences in working patterns. Women are more likely to work part-time, take time out of the workforce for caring and may experience slower career progression following these breaks.  </div>

<div> </div>

<div>Within the LGPS, part-time working is a particularly important factor. The Scheme Advisory Board (SAB) found that differences in both current and historic part-time work explain a large part of the gap, although they do not fully account for it. </div>

<div> </div>

<div>Policy changes are helping. The move to a career average revalued earnings (CARE) structure and recent reforms to make periods such as unpaid maternity leave pensionable are positive steps.  But change will be gradual. Structural reform on its own will not close the gap quickly.  </div>

<div> </div>

<div><strong>Engagement is the missing piece </strong></div>

<div>One clear lesson from the private sector is that talking about pensions alone does not engage people. Most individuals focus on immediate concerns such as cost of living, housing or childcare. Pensions feel distant and abstract. If we start with pensions, many people disengage. If we start with real-life financial priorities, engagement improves. </div>

<div> </div>

<div>This is why awareness is essential but not sufficient. People need to understand the scale of the gap and how it applies to them personally. When the issue becomes tangible, behaviour starts to change. For LGPS funds, this means reframing the conversation. Pensions should be part of a wider financial wellbeing discussion, not the sole focus. </div>

<div> </div>

<div><strong>Confidence and behaviour matter </strong></div>

<div>Another important factor is financial confidence. There is consistent evidence that women are less likely to feel confident making financial decisions, even where capability is similar. The Money and Pensions Service reports that women are less likely to understand pensions well enough to make decisions and more likely to lack a financial plan for retirement.  </div>

<div> </div>

<div>The Financial Conduct Authority&rsquo;s Financial Lives 2024 survey also shows that millions of people have low financial capability, which affects their ability to engage with financial decisions and services. These differences are shaped by experience, messaging and habit. Over time, they can lead to lower engagement, fewer proactive decisions and poorer long-term outcomes. </div>

<div> </div>

<div>This matters because many women will ultimately need to manage finances independently. By the time a woman is 60, she has a 3 in 5 chance of being single, divorced or widowed. Building confidence earlier in life is therefore a critical part of closing the pensions gap. </div>

<div> </div>

<div><strong>A life-stage approach works </strong></div>

<div>In practice, engagement is often more effective when it reflects where people are in their lives: </div>

<div><strong>Early career </strong></div>

<div>Focus on immediate concerns such as debt, rent and affordability. These can act as entry points into longer-term planning, including early awareness of pensions. </div>

<div><strong>Starting a family </strong></div>

<div>Explain the potential impact of career breaks, reduced hours and contribution gaps, including how these may affect pension savings. Keep the implications clear and practical. </div>

<div><strong>Mid-career </strong></div>

<div>Introduce structured interventions such as Midlife MOTs, where appropriate. This gives people space to review their overall financial position, including pensions, and consider their future plans. </div>

<div><strong>Approaching retirement </strong></div>

<div>Shift the focus towards retirement timing, income and available options, helping people understand how their pension savings may support different outcomes. The key principle remains - people are more likely to engage when the message reflects their current priorities. Pensions remain an important part of the conversation but are often better understood when linked to what matters most to individuals at each stage of life. </div>

<div> </div>

<div><strong>The LGPS starts from strength </strong></div>

<div>The LGPS has a strong foundation to build on. It is a defined benefit scheme, providing certainty and security that many private sector workers do not have. It also benefits from automatic enrolment and established employer structures.  </div>

<div>This means the challenge is not about fixing a weak system. It is about ensuring that all members can benefit equally from a strong one. </div>

<div> </div>

<div>For LGPS funds and employers, five practical actions stand out: </div>

<div><em>Go beyond pensions and focus on financial wellbeing. </em></div>

<div><em>Make better use of data to identify at-risk groups such as part-time workers and those with career breaks. </em></div>

<div><em>Target key life events including maternity leave and return to work. </em></div>

<div><em>Tailor communications to different life stages rather than using a single approach. </em></div>

<div><em>Use employers as a key channel, embedding messages into existing communication points. </em></div>

<div> </div>

<div><strong>Closing thoughts </strong></div>

<div>Closing the gender pensions gap in the LGPS is not about talking more about pensions. It is about understanding what drives the gap and responding in a way that feels relevant to people&rsquo;s lives. </div>

<div> </div>

<div>That means focusing on behaviour, engagement and confidence, not just scheme design. The LGPS has a strong base. The opportunity now is to build on it with more targeted, more personalised and more practical support. </div>

<div>If we do that well, we will not just reduce a gap. We will help more members make better financial decisions throughout their lives. </div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/gender-pensions-gap-in-the-lgps-start-earlier--engage-better-26946.htm</link>
<pubDate>Tue, 21 Jul 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Fca General Insurance Value Measures Data 2025</title>
		<description><![CDATA[<div>This publication is a factual summary only. We explain any data challenges and limitations, and our approach to data quality below. Please note that our post-implementation review of the value measures rules is ongoing - we plan to publish our findings later this year, which will enable us to draw attention to the known data issues we are tackling (for example, the inconsistencies in how firms report claims acceptance data for home insurance).</div>

<div> </div>

<div><strong>This data supports our wider work, including:</strong></div>

<div><em>Our ongoing commitment to the recommendations in our July 2025 retail insurance publication. In that work, we examined the reasons for increases in motor insurance premiums, with a focus on claims costs, and looked at claims handling in home and travel insurance.<br />
 Our expanded work to improve standards in the home and travel insurance markets following Which?&rsquo;s super complaint.</em></div>

<div> </div>

<div>These issues remain priorities for us and feature in our <strong><a href="https://www.actuarialpost.co.uk/downloads/cat_1/FCA insurance-report-2026.pdf">Regulatory Priorities: Insurance report</a>,</strong> published earlier this year.</div>

<div> </div>

<div><strong>How data informs our prioritisation and supervisory approach</strong></div>

<div>We use the value measures data to identify areas where consumers may not be receiving fair value or good outcomes. This informs our assessment and prioritisation of market-wide issues or individual firms that need further investigation.</div>

<div> </div>

<div>Our strategy makes clear that firms demonstrating that they are trying to do the right thing should expect lower-intensity supervision. On the other hand, firms with significant, multiple or recurring outlier indicators in the value measures data (as well as from other sources) should expect greater supervisory focus and action, especially where concerns persist or improvements are not being made.</div>

<div> </div>

<div>As an example, the value measures data informed our previous action on GAP insurance from which firms agreed to pause selling until they could show that their products provide fair value to customers. The data was also used to form part of our response to the Which? super complaint. In our 2023 value measures publication, we set out actions for firms and our expectations under PROD4 and the Consumer Duty, which remain unchanged.</div>

<div> </div>

<div><strong>What the 2025 data showsHome and travel insurance</strong></div>

<div>The data for home and travel insurance continues to reflect the trends we focused on in our response to the Which? super complaint and our Regulatory Priorities: Insurance report. We expect to see these measures improve through firms&rsquo; actions in response to our ongoing work. In particular:</div>

<div> </div>

<div><strong>Across both home and travel insurance, claims complaints as a percentage of claims registered are high</strong> compared with other retail insurance products - home insurance (7-13%) and travel insurance (5-6%), whereas most other products fall between (0-6%). </div>

<div> </div>

<div><strong>In home insurance:</strong></div>

<div><strong>Claims acceptance rates are relatively low</strong> - 62-71% for home compared with 83-86% for travel and 99% for motor. However, as noted in previous publications, we believe there are inconsistencies in how firms report claims acceptance data for home insurance and this means the rates should be used with caution. We have set up an industry working group to further consider value measures issues, including reporting inconsistency. <br />
<strong>Average claims payout increased across home insurance products,</strong> especially buildings and contents, where it rose by 17%. <br />
<strong>Claims costs as a proportion of premiums remained stable</strong> at 48% for home insurance, combining buildings and contents (46% in 2024).</div>

<div> </div>

<div><strong>In travel insurance:</strong></div>

<div><strong>Claims costs as a proportion of premium increased</strong> across all 3 travel products (annual European, annual Worldwide and single-trip stand-alone) from 2024 to 2025 (44-48% in 2025 vs 31-37% in 2024). Premiums increased by 12% for these products but the amount paid out in claims increased by 47%.</div>

<div> </div>

<div><strong>Claims costs across all products</strong></div>

<div>At aggregate product level, where at least 5 firms reported data and the data met our publication standards, we continue to see <strong>significant variation in claims costs as a proportion of premium</strong>, ranging from 17% for wedding and party insurance to 68% for healthcare cash plan (All). This is similar to the range in 2024, when the lowest was 20% for tyre cover (Add-on) insurance and the highest 69% for healthcare cash plan (All).*</div>

<div> </div>

<div><em>* Range excludes data for GAP insurance.</em></div>

<div><img alt="" src="https://www.actuarialpost.co.uk/images/pic_FCAInsuranceData2026.jpg" style="height:189px; width:600px" /></div>

<div> </div>

<div><strong>Other metrics of note</strong></div>

<div><strong>For Motor insurance, the largest retail general insurance product, premiums fell in 2025 by 7%</strong> while the average number of policies in force rose by 4%. A small increase in claims costs pushed claims costs as a proportion of premium from 54% in 2024 to 59% in 2025. For motor insurance (although it is also true of other products), there may be a time lag between the new business price captured in our data and the point when the claims payout is recorded. Where prices or claims costs are moving rapidly this can influence our data &ndash; particularly our figures on claims costs as a proportion of premium.<br />
<strong>Data for GAP insurance continues to reflect the impact of our interventions in late 2023 and early 2024</strong> with GAP insurance firms. In 2024, written premiums fell significantly and, while claims were still being paid, the claims costs as a proportion of premium rose above 100%. In 2025, claims costs as a proportion of premium for GAP (Stand-alone) insurance fell from 104% to 53%. Prior to our interventions, the proportion of premium paid out in claims for 2022 was 7% and for 2023 was 22%. We expected these figures to change dramatically between 2024 and 2025 as a result of our interventions. These figures should still be used with caution and may not yet be representative of product value or performance.<br />
<strong>Gadget insurance saw a fall in the percentage of premiums paid in claims,</strong> from 42% to 36% - one of the largest drops across all products. This was mainly driven by higher premium rates. Policies in force fell by 5% to 7.5 million, the number of claims registered fell by 8%, and claims costs fell by 12%, while premiums rose by 3%.<br />
<strong>Travel insurance policies in force for single-trip travel insurance,</strong> stand-alone single-trip policies rose by 15% to 3.1 million in 2025 &ndash; however, these figures should be used with caution. This figure is more volatile than for many other products given the short duration of these policies and the way that firms account for these policies in their data. Travel policies provided under packaged bank accounts are not included in our value measures data.</div>

<div> </div>

<div><strong>Factors to consider when analysing the data</strong></div>

<div>A wide range of factors can affect the value of a general insurance product. These factors should be considered together, rather than looking at individual measures in isolation. Some factors that are not visible in the value measures data may also affect the results for a given period. These include business mix, product age, policy duration, target market and business volumes. External factors such as climate, inflation and wider societal issues may also have an impact.</div>

<div> </div>

<div>The proportion of premiums paid out in claims is one possible indicator of the relationship between the price of risk and the total price. It may vary over time or between firms, for example because of a new product launch, a fall or pause in sales, or significant pricing changes. We publish this metric at aggregate product level because it allows some comparison across products, where other measures may be more affected by product-specific features.</div>

<div> </div>

<div>The data is not intended to help consumers choose insurance products directly. It is historical and may not reflect products and prices available today. Consumers with questions about the value of their insurance products should speak to their insurer or broker. It is important that consumers understand the cover they are buying, have confidence that it offers fair value, and are treated fairly when making a claim.</div>

<div> </div>

<div><strong>Data quality</strong></div>

<div>Firms are responsible for submitting complete and accurate Value Measures data by 28 February each year. Before publication, we validate the data to identify and clarify anomalies that may materially affect aggregate product data, and to ensure firms correct and resubmit returns where errors are confirmed. This year, we contacted 35 firms as part of this process, around half of which resubmitted data. Reporting inaccuracies or inconsistencies may still remain between firms, but we seek to resolve the most material issues through this process.</div>

<div> </div>

<div>Our reporting system is live and can accept resubmissions at any time. Once validation is complete, we therefore take a fixed snapshot of the data to preserve the version validated with firms and enable publication. This also prevents later submissions from introducing new anomalies or errors. The data published today reflects the data held in FCA systems on 5 May 2026.</div>

<div> </div>

<div>This year, three firms updated their data after the fixed snapshot was taken. In most cases, these updates had minimal impact on aggregate product data. However, following late clarification from one firm that it had made a material reporting error, as an exception we decided to manually update two datapoints in the product aggregate data:</div>

<div> </div>

<div>2024 claims acceptance rate for Before the event legal expenses &ndash; home (All)</div>

<div>2024 average claims payout for Home (buildings and contents combined) (All)</div>

<div> </div>

<div>We judged that the firm&rsquo;s error had a sufficiently material impact on the market-wide data for those datapoints to justify manual correction. We are not aware of any further material issues with the data and have retained the fixed snapshot elsewhere in the data. We are following up with firms where reporting needs to improve and considering broader options to strengthen data quality.</div>

<div> </div>

<div>Data may also change between publication cycles if firms identify and correct errors outside the normal reporting period, for example through routine audit activity. Comparisons with previous publications should therefore be made with care.</div>

<div> </div>

<div><strong>What the data includes</strong></div>

<div>The data includes firm-specific information on claims frequency, claims acceptance rates, average claims payouts and claims complaints as a proportion of claims for a wide range of retail GI products.</div>

<div> </div>

<div>Firms must report on relevant products sold to consumers in the UK where total written retail premiums are above &pound;400,000 in the reporting period and there are more than 3,000 policies in force during that period. As before, we are publishing data about individual firms where the same reporting threshold is met at detailed product level.</div>

<div> </div>

<div>We have included additional context at aggregate product level to help readers interpret the data. For example, we have calculated the proportion of premiums paid out in claims. Our aggregate product data includes only products where 5 or more firms submitted data and where the data met our publication standards.</div>

<div>In Policy Statement PS20/9 we said that we would not require firms to report claims cost information for legal expenses insurance or vehicle breakdown insurance. The data does not include related metrics for these products.</div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/fca-general-insurance-value-measures-data-2025-26948.htm</link>
<pubDate>Tue, 21 Jul 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Sterling Up As Strong Job Market Meets Burnhams First Target</title>
		<description><![CDATA[<p>Speculation over increases to capital gains tax and the top rate of income tax is set to intensify, with investors expected to adjust portfolios.</p>

<p><strong>Susannah Streeter, Chief Investment Strategist, Wealth Club: </strong>&ldquo;The Footsie has been on the back foot in early trade as investors keep an eye on Middle East tensions, a stronger pound puts pressure on some listed multinationals, and investors assess the Burnham administration&rsquo;s policies.  A slightly more resilient snapshot of the UK labour market has lifted sterling, just as the Prime Minister unveiled the first significant cost-of-living intervention of his premiership. The abolition of VAT on household electricity bills from October should provide some welcome relief for households, although it will only make a modest dent in overall energy costs, amounting to around &pound;45 per year for a typical bill payer. Investors will now be looking beyond the immediate announcement to how further support measures can be funded while keeping the public finances on a sustainable footing.</p>

<p>The latest snapshot of the UK labour market highlights the difficult inheritance facing the new government. While unemployment has edged slightly lower compared with the previous quarter, suggesting employers are hanging on to staff, the rise in the claimant count underlines that many families continue to feel the squeeze. Employment has largely stalled and economic inactivity remains stubbornly elevated, pointing to an economy that's proving a little more resilient than expected but still sluggish. Sterling has nudged higher, an indication that investors are increasingly pricing in two further interest rate hikes from the Bank of England after figures showed the jobs market is holding up better than forecast.</p>

<p>That resilience, however, comes with a sting in the tail for the Burnham administration. If borrowing costs stay higher for longer, it will make the task of repairing the public finances while delivering further cost-of-living support even more difficult. Cutting VAT on electricity bills is a relatively inexpensive intervention compared with lifting the threshold for the first rate of income tax, but if the government wants to go further it will have to find room within already tight fiscal constraints and raise money elsewhere. Burnham's government will also need to find ways to lift productivity and coax more people back into the workforce if it wants to generate the stronger economic growth needed to relieve pressure on households and the Treasury alike.</p>

<p>A little more hope appears to be creeping in about the potential for negotiations to resume in the Middle East and act as a circuit breaker to escalating violence. Amid rumours that talks could restart this week, Brent crude has shifted a little lower to around $88 a barrel, and some optimism has returned to financial markets. Stocks in Asia largely lifted, with Japan's Nikkei clawing back some of its losses. But as investors assess the shifting expectations about where the conflict could go next, European indices look set for a flat start to trading.</p>

<p>Fractious trade policy is once again front and centre, with the US slapping 50% tariffs on some Canadian goods, underlining how brinkmanship remains a key feature of the presidency. The higher duties are set to be imposed within 30 days, in retaliation for what Trump claims is unequal treatment of US cars, dairy and alcohol. Futures markets indicate that Toronto's main exchange will open in the red, as investors react to this fresh deterioration in bilateral relations. But Prime Minister Mark Carney appears sanguine, deflecting the threats with a vow to intensify negotiations. There will be expectations that the US will roll back after some concessions are made, but it's a reminder of the Trump administration's bullish treatment of both former friends and long-time foes.</p>

<p>There's been a cautious welcome on markets to John Healey's appointment as Chancellor, taking control of the UK's fragile finances. Former Defence Secretary John Healey was a Treasury minister in Gordon Brown's government, and there's an expectation he'll very much be playing second fiddle to Andy Burnham when it comes to leading economic policy, singing from the same song sheet on decentralisation and backing regional industrial bases. But the immediate focus will be on the military implications of his appointment. Having resigned from government over the lack of a roadmap to meet NATO commitments of defence spending reaching 3% of GDP by 2030, attention will now turn to how quickly he might be able to find more funding to bolster the defence investment plan. Shares in military contractors BAE Systems, Rolls Royce, QinetiQ and Melrose were all higher in early trade, indicating investors expect the chancellor will be a bigger backer of defence than his predecessor. There will be cautious optimism to his appointment across the armed services. Having spent months making the case for higher military spending, Healey has a detailed understanding of the capability gaps facing the armed forces and the demands of a far more dangerous geopolitical environment. It comes at a highly timely moment, given reports of live-firing weapons exercises by a Russian warship off the Plymouth coast. The service chiefs are likely to believe they now have a Chancellor who understands their concerns more fully and may be more willing than his predecessor to set out a credible pathway towards spending 3% of GDP on defence.</p>

<p>However, he's also inherited responsibility for balancing the nation's books, and the question will be whether he can reconcile his long-standing support for higher military spending with the government's fiscal rules, which require debt to be falling as a share of the economy by the end of the Parliament. Finding room for defence while also funding infrastructure, social care, employment programmes and measures to boost growth could prove one of the defining challenges of his time at the Treasury.</p>

<p>It also puts the question of tax rises back front and centre to fund these demanding requirements, especially with the VAT cut to energy bills, with speculation about increases in capital gains tax and further changes to the top rate of income tax likely to intensify. However, investors should resist the urge to drastically alter portfolios in an attempt to get ahead of potential tax changes. History shows us that rashly switching and ditching assets based on speculation can lead to unnecessary transaction costs, trigger premature tax liabilities and, crucially, miss out on the power of long-term compounding. Timing the market is hugely difficult, and time in the market is what counts most. Nevertheless, it may be worth trimming positions which have performed spectacularly well to lock in gains. For those looking to shelter their portfolios, it is well worth exploring government-backed, tax-efficient life rafts like Venture Capital Trusts (VCTs), the Enterprise Investment Scheme (EIS), and the Seed Enterprise Investment Scheme (SEIS).&rdquo;</p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/sterling-up-as-strong-job-market-meets-burnhams-first-target-26938.htm</link>
<pubDate>Tue, 21 Jul 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Faster Pension Transfers Backed But Scam Protection Crucial</title>
		<description><![CDATA[<p>The consultation forms part of the Government&rsquo;s wider work to tackle pension scams and improve the pension transfer process. It includes a targeted measure to address the risks of fraud within Small Self-Administered Schemes (SSASs), and represents the first stage of a broader programme of work relating to pension scams and pension transfers.</p>

<p>PSIG supports the aim of reducing unnecessary delays and friction where transfers are low risk. However, the group has identified several areas where further clarity and refinement are needed, including the proposed employment link warning sign, the approach to identifying lower-risk receiving schemes, oversight of SSAS arrangements, and ensuring the regulations remain effective as scam methods continue to evolve.</p>

<p><strong>PSIG Chair Margaret Snowdon OBE said:</strong> &ldquo;The key challenge will be getting the balance right - removing unnecessary delays for legitimate transfers while maintaining the protections needed to prevent fraud and protect savers. Members should not face unnecessary delays when making genuine transfers, but trustees and administrators must retain the ability to identify risks and act when something does not look right.</p>

<p>&ldquo;The proposed employment link warning sign is an important area where we believe changes are needed. As currently drafted, it may not always work as intended. A genuine employee could trigger a warning sign because they do not meet certain salary or contribution thresholds, while someone without a genuine employment link may avoid the same scrutiny by providing only partial evidence. We recommend that a red flag should apply wherever the employment link remains unproven, whether all, some or none of the required evidence has been provided.</p>

<p>&ldquo;We also support giving trustees greater discretion where they believe a transfer is low risk, but there needs to be greater clarity around the proposed concept of a &lsquo;reputable scheme&rsquo;. Trustees should be able to carry out further due diligence where they consider it necessary, without first having to make a potentially subjective judgement about a scheme&rsquo;s reputation.&rdquo;</p>

<p><strong>Snowdon continued: </strong>&ldquo;The risks facing pension savers continue to evolve. We are seeing increasing use of impersonation fraud, clone firms, artificial intelligence-generated evidence, social media investment scams, crypto-linked pension liberation and newly established occupational schemes with little or no genuine employment activity. The regulatory framework needs to keep pace with these developments. The employment link alone will not address the wider vulnerabilities in the SSAS market. We support proportionate additional oversight of these arrangements, including consideration of a requirement for professional trustee involvement.</p>

<p>&ldquo;We also need to ensure that any approach to lower-risk scheme lists is properly governed, regularly reviewed and supported by clear accountability, while recognising the practical challenges and responsibilities involved in maintaining them. The proposed exemption from repeat MoneyHelper guidance also needs careful consideration. While it may be appropriate where a member&rsquo;s circumstances have not changed and the guidance remains relevant, a subsequent transfer could involve a different receiving scheme, different warning signs or a materially different level of risk. The regulations should ensure that members receive appropriate guidance and safeguards where the circumstances and risks warrant it.&rdquo;</p>

<p><strong>Snowdon concluded:</strong> &ldquo;Ultimately, these reforms could help deliver a faster and more effective transfer process. But the test of success is not simply whether transfers happen more quickly, it is whether they can happen safely. Legitimate members should not face unnecessary barriers, but fraudsters should not be given new opportunities to exploit the system -make it easier for good transfers to proceed and harder for bad actors to succeed.&rdquo;</p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/faster-pension-transfers-backed-but-scam-protection-crucial-26940.htm</link>
<pubDate>Tue, 21 Jul 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Ipt Receipts Hit  2 172 Bn In First Three Months Of The Year</title>
		<description><![CDATA[<div>At a monthly level, June 2026 receipts stood at &pound;52 million - &pound;11 million higher than the previous year where receipts stood at &pound;41 million.</div>

<div> </div>

<div>The latest figures follow a record annual total of &pound;9.04 billion for the 2025/26 financial year, which exceeded the previous year&rsquo;s full-year total of &pound;8.88 billion by &pound;157 million.</div>

<div> </div>

<div>The Office for Budget Responsibility&rsquo;s Spring Statement forecasts indicate that IPT is now expected to raise &pound;57.8 billion between 2025/26 and 2030/31, a &pound;500 million upgrade on estimates made following the Autumn Budget in November (&pound;57.3 billion). Continued demand for health-related insurance products is expected to remain a key driver of growth.</div>

<div> </div>

<div><strong>Cara Spinks, Head of Life & Health at Broadstone, commented:</strong> &ldquo;IPT receipts have continued to grow in the early part of the new financial year, building on the record levels seen in 2025/26.</div>

<div> </div>

<div>&ldquo;Demand for health insurance remains strong as employers and individuals continue to look for ways to access healthcare more quickly, particularly while pressure on NHS services persists. At the same time, rising healthcare costs are feeding through into higher premiums, which is also contributing to increased IPT receipts.</div>

<div> </div>

<div>&ldquo;As the new cabinet under Andy Burnham looks to tackle economic inactivity, improve prevention and support a healthier workforce, there is a strong case for reviewing the tax treatment of health insurance. Health insurance including health cash plans increasingly provide access to early intervention, mental health support and rehabilitation services that help people remain in work or return to work more quickly. A targeted reduction in IPT for these products could improve access to preventative healthcare, support workforce participation and reduce pressure on NHS services at the same time.&rdquo;</div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/ipt-receipts-hit--2-172-bn-in-first-three-months-of-the-year-26941.htm</link>
<pubDate>Tue, 21 Jul 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>76  Of Pensions Policy Makers To Explore Cdc In Next 3 Years</title>
		<description><![CDATA[<p>Interest in Collective Defined Contribution (CDC) pensions is reaching a tipping point, with more than three quarters (76%) of UK pensions influencers and decision-makers set to consider a CDC option within the next three years.</p>

<p>That&rsquo;s according to Gallagher&rsquo;s CDC Report, which examines industry confidence levels, the barriers to implementation and the path to scale for CDC pension schemes in the UK.</p>

<p>The research, which surveyed 250 employers, trustees and pensions professionals, arrives at a time when multi-employer CDC schemes are nearing regulatory approval in the UK.</p>

<p>Interest in the CDC model is growing, with around half of respondents (52%) saying they would be comfortable being an early adopter. </p>

<div><strong>Interest in CDC is growing but confidence is a barrier</strong></div>

<div>Larger employers are leading the way. Among respondents working with companies of fewer than 250 members, 51% expect to explore CDC within the next three years. This rises to more than 80% among respondents from companies.</div>

<p>The findings indicate that larger employers may be better placed to assess CDC at this stage. Beyond the natural barrier of cost, they are more likely to have specialist pensions support and strong internal governance structures. Smaller companies may face greater barriers around governance capacity and internal resource.</p>

<p>Notably, many organisations are hesitant to move first when it comes to adopting CDC. When asked what would increase their confidence, respondents cited clearer regulatory guidance (39%), proven results from early adopters (38%) and positive feedback from unions or employee representatives (37%).</p>

<p><strong>Andre Clarke, Senior Vice President, Investment Consulting at Gallagher, said: </strong>&ldquo;In a very short period, the conversation around CDC has moved forward at blinding speed. The Royal Mail scheme gave the UK market its first live example. It is no longer possible to think of CDC as a niche actuarial idea; it is stepping into the spotlight, demanding close attention.&rdquo;</p>

<p>&ldquo;However, our research paints a more nuanced picture. There&rsquo;s a clear difference between exploring CDC as an option and taking the steps to introduce it into an existing benefits package. Employers and trustees want to see more test cases, and they want greater clarity on regulation and delivery. Then they want to understand what it really means for their specific workforce. It is here where an experienced consultant can help firms assess their options in the CDC market and decide which arrangements could suit their workforce best.&rdquo;</p>

<div><strong>Multi-employer models lead the way</strong></div>

<div>The availability of practical access routes will determine the rate of CDC adoption. More than half (53%) of respondents say they would be most likely to consider a multi-employer or master trust CDC arrangement, compared with 34% who would favour a single-employer model.</div>

<p>Sector-wide arrangements also saw significant interest, with 86% saying they would find a sector-wide CDC scheme appealing. The findings point to a preference for scalable CDC models that can be put into action across a broader range of organisations.</p>

<div><strong>A role for both whole-life and retirement CDC</strong></div>

<div>The research also challenges assumptions about how the CDC market may evolve. While retirement-only CDC arrangements have received a high amount of attention, the majority of the respondents preferred whole-life CDC. Nearly one third (32%) favour whole-life CDC, compared with 22% who favour retirement-only arrangements.</div>

<p>The largest group (36%) see both models as equally appealing, suggesting many organisations are open-minded about how CDC could be delivered in practice and recognise that their roles are not mutually exclusive.</p>

<p><strong>David Piltz, CEO of Gallagher's Benefits & HR Consulting Division, says: </strong>&ldquo;For decades, employers and pension professionals have struggled with one question: how can we offer good retirement outcomes for employees without putting too much risk on the balance sheet? A Collective Defined Contribution scheme offers a potential alternative. It is an aspirational model, and one that could offer more predictable outcomes than a traditional Defined Contribution scheme and without the high-risk guarantees of a Defined Benefit plan.</p>

<p>&ldquo;The challenge is converting that interest into adoption. If a firm is unsure about CDC, it&rsquo;s likely due to a mix of factors: a low number of test cases, competing business priorities, and a hesitance to step out first. The science, regulations, and guidance are in place, but the industry needs to communicate CDC in a way that everyone can understand. That is the only way that the sector will translate the growing interest into this emerging area into real and tangible action.&rdquo;</p>

<p><br />
 </p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/76--of-pensions-policy-makers-to-explore-cdc-in-next-3-years-26945.htm</link>
<pubDate>Tue, 21 Jul 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>M g Completes  760m Bpa Transaction For Smiths Group</title>
		<description><![CDATA[<div>The Trustee prioritised strong administration and member experience as the scheme has multiple sections following years of acquisitions. As part of its selection process, the Trustee recognised M&G&rsquo;s ability to manage this complexity and deliver a smooth transition.</div>

<div> </div>

<div>M&G is a founding member of the BPA market with over 25 years of experience implementing and administering bulk annuity transactions, backed by a robust balance sheet and a firm commitment to meeting customers&rsquo; needs. Building on the launch of BPA Plus1, a key differentiator for M&G in the market, the business expects to achieve &pound;3&ndash;&pound;4 billion of annual BPA sales by 2027.</div>

<div> </div>

<div>Hymans Robertson acted as risk transfer adviser, Aptia as Scheme administrator, Aon as Scheme actuary, Gallagher as investment adviser and Sackers as the Scheme&rsquo;s legal adviser. </div>

<div> </div>

<div><strong>Rosie Fantom, Head of Bulk Annuity Origination & Execution at M&G, said:</strong> &ldquo;We are delighted to have been selected by the Trustee as their trusted partner for their fifth and final buy-in. This is an important milestone for the Smiths Industries Pension Scheme, completing its move to fully secure members&rsquo; benefits. It also highlights the strength of our proposition and our ability to support schemes of varying size and complexity, with a focus on delivering tailored solutions, excellent administration and a positive member experience.&rdquo; </div>

<div> </div>

<div><strong>Nicholas Godden, Chair of the Trustee of Smiths Industries Pension Scheme, said: </strong>&ldquo;This buy-in with M&G reflects many years of careful planning and strong collaboration between the Trustee, Smiths Group and our advisers. On behalf of my fellow Directors, I would like to thank everyone involved in making the transaction possible, including all of our advisers and the Smiths Group in-house pensions team. Their collective expertise, commitment and support have been central to achieving this significant step in the Scheme&rsquo;s journey.&rdquo;</div>

<div> </div>

<div><strong>Michael Abramson, Partner at Hymans Robertson, said:</strong> &ldquo;We&rsquo;re delighted to have supported the Trustee in completing this final buy-in, securing the benefits of more than 10,000 members and their dependants. The insurance selection process placed significant emphasis on member experience, administration and implementation capability alongside pricing, ensuring an excellent outcome for the Scheme.&rdquo;</div>

<div> </div>

<div>This transaction was executed by the Prudential Assurance Company Limited (&ldquo;Prudential&rdquo;), M&G&rsquo;s wholly owned subsidiary providing life and pensions solutions.</div>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/m-g-completes--760m-bpa-transaction-for-smiths-group-26939.htm</link>
<pubDate>Tue, 21 Jul 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Burnhams Vat Carrot Begs A Bigger Question  Who Pays For It </title>
		<description><![CDATA[<p>&ldquo;The government estimates the measure will cost &pound;850 million this financial year, funded by savings from scrapping the digital ID programme. But the bigger question is what will ultimately fund the new government&rsquo;s &ldquo;new economic model&rdquo;.</p>

<p>&ldquo;Burnham has inherited a difficult economic backdrop: subdued growth, stubbornly high borrowing, a sizeable national debt and rising debt-servicing costs, alongside unresolved questions over how to fund higher defence spending. The arithmetic leaves limited room for manoeuvre. Higher taxes, spending cuts, more borrowing - or some combination of the three - could all be on the table.</p>

<p>&ldquo;That matters because the UK already has a highly progressive income tax system, with a relatively small group of higher earners shouldering a disproportionate share of the burden. Our analysis shows that someone earning &pound;150,000 earns 3.8 times the median full-time salary yet pays more than 10 times as much in income tax.&quot;</p>

<p>&ldquo;Frozen tax thresholds have also steadily pushed more people into higher tax bands without a corresponding improvement in their standard of living. This is particularly relevant for HENRYs - high earners, not rich yet - who may look affluent on paper but are often juggling hefty mortgages, childcare costs, pension contributions and other financial commitments.</p>

<p>&ldquo;So, while the government may want to pursue a different economic strategy, the question is how much more pressure can be placed on the same relatively narrow group of taxpayers. The key issue is not simply whether taxes will rise, but who will ultimately be expected to pay for Burnham&rsquo;s economic agenda - and whether those already carrying a disproportionate share of the burden have much more capacity left.&rdquo;</p>

<p> </p>

<p> </p>

<p> </p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/burnhams-vat-carrot-begs-a-bigger-question--who-pays-for-it--26942.htm</link>
<pubDate>Tue, 21 Jul 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Comments On Ifs Retirement Savings Consortium Report</title>
		<description><![CDATA[<p><strong>Calum Cooper, Head of Pension Policy Innovation, Hymans Robertson (member of the consortium), says: </strong>&ldquo;This is a timely and valuable report from the Institute for Fiscal Studies&rsquo; Retirement Savings Consortium. Automatic enrolment (AE) has been a huge success. It&rsquo;s brought millions more people into pension saving. However, that participation is not the same as adequacy and this report tackles that challenge head-on. The report also highlights an important employer reality. The impact of reform will not land evenly. Employers have just absorbed higher National Insurance costs and many are already planning for future salary sacrifice changes. At the same time, productivity growth remains weak and economic uncertainty is high. Against that backdrop, employers will want to understand how any increase in minimum contributions affects their workforce, pay profile and business model. For some sectors, especially those with large numbers of lower-paid or minimum wage workers, there are simply fewer levers to pull. The IFS scenarios provide a useful framework for that kind of planning.</p>

<p><strong>Hannah English, Head of DC Corporate, Hymans Robertson (member of the consortium), says:</strong>&ldquo;From an employer perspective, the how matters as much as the how much. A clear roadmap will be vital. Long lead times and gradual escalation will be essential. Reform must also be simple to operate as complexity creates cost, compliance risk and confusion. Employers are more likely to engage positively if the direction of travel is clear and the system is hard to get wrong. Most importantly, adequacy is not just a pensions issue. It is a workforce issue. Better pensions can support financial resilience, workforce planning and productivity. They help people make better decisions about when and how they retire. Higher contributions are likely to be part of the solution, but they are not the whole answer. Every pound saved needs to work harder through strong value for money, effective investment and better retirement support. There&rsquo;s no cost-free route to higher retirement incomes. This report from the IFS makes it clear that the question for the Second Pensions Commission is how to improve outcomes while balancing affordability for workers, employers and the Exchequer.  If pension reform gets those things right, it can become a success not just for savers, but for employers and the wider economy too.&rdquo;</p>

<p><strong>Catherine Foot, Director of the Standard Life Centre for the Future of Retirement said: </strong>&quot;The Pensions Commission's interim report rightly highlighted the scale of the retirement savings challenge facing millions of workers. Automatic enrolment has transformed pension participation, but current minimum contribution levels are unlikely to deliver adequate retirement incomes for many people, making further reform essential. Today's report reinforces the case for action. It shows that higher pension contributions and broader pension coverage could help significantly more people achieve adequate retirement incomes, particularly younger generations who have longer to benefit from reforms. In particular it correctly highlights the earnings thresholds limit the amount people save and potentially give them a false sense they are saving more than they are. We believe the long-term ambition should be to remove these limits and increase minimum contributions from 8% to 12%, delivered through a clear, phased and affordable roadmap. At the same time, reforms must recognise that people's financial circumstances change throughout their working lives. Any package should balance better retirement outcomes with the financial pressures households face today. Policymakers should therefore explore greater flexibility within the system, including temporary opt-down or pause mechanisms, allowing people facing short-term financial pressures to remain engaged with pension saving rather than opting out altogether. By combining higher contributions, broader coverage and greater flexibility, we can build on the success of automatic enrolment and create a system that improves retirement outcomes while remaining realistic about the challenges many households and employers face today.&quot;</p>

<p><a href="https://www.actuarialpost.co.uk/downloads/cat_1/IFS Retirement Savings Consortium Report 2026.pdf"><strong>IFS Retirement Savings Consortium Report</strong></a></p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/comments-on-ifs-retirement-savings-consortium-report-26943.htm</link>
<pubDate>Tue, 21 Jul 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Cgt And Iht Up Again As Both Hit Record Year</title>
		<description><![CDATA[<p><strong>Mark Jephcott, Senior Relationship Manager at Utmost commented: </strong>&ldquo;CGT receipts remain at historically elevated levels following a record year for Treasury receipts. The higher rates introduced at the Autumn Budget 2024, combined with fiscal drag, are drawing ever more individuals into the CGT net and are likely to drive a sustained increase in receipts over the coming years. While CGT generates significant revenues for the Treasury, it does little to enhance the UK's appeal to internationally mobile investors and entrepreneurs, with other jurisdictions offering more attractive tax regimes for wealth creators.&rdquo;</p>

<p>&ldquo;Inheritance Tax continues to generate historically high tax revenues for the Treasury as frozen thresholds and rising asset values bring more families within scope of the tax. The Autumn Budget 2025 extended the threshold freeze until 2031, while the scope of IHT continues to expand following reforms to Business Property Relief that came into effect on 6 April 2026 and with unused pension pots set to fall within the scope of Inheritance Tax from April 2027. While these measures are increasing tax receipts, it is making the UK a less competitive destination for entrepreneurs, investors and internationally mobile wealthy individuals, who make an outsized contribution to the tax take.&rdquo;</p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/cgt-and-iht-up-again-as-both-hit-record-year-26944.htm</link>
<pubDate>Tue, 21 Jul 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>Typical 55 year old May Need  74 month Extra If Spa Rises</title>
		<description><![CDATA[<p>Its modelling shows that a 55-year-old on median UK earnings (&pound;38,000) who wants to retire at 67 would need to save around an extra &pound;74 a month (2.3% of salary) until retirement to bridge the one-year gap before becoming eligible for the State Pension.</p>

<p>While higher earners would need to save broadly the same cash amount, the impact on affordability is very different. Someone earning &pound;80,000 would still need to save around &pound;74 a month, but because of their higher income and greater tax relief, this equates to around 1.1% of salary, compared with 2.3% for someone on median earnings.</p>

<p>Once pension tax relief is taken into account, the impact on take-home pay falls to around &pound;53 a month (1.7% of salary) for the median earner using salary sacrifice, compared with &pound;43 a month (0.6% of salary) for an &pound;80,000 earner.</p>

<p><strong>Martin Willis, Partner at Barnett Waddingham, part of Howden, said: </strong>&quot;People have understandably focused on the &pound;12,500 they'd need to replace if they still wanted to retire at 67. But for many households, the more immediate question is what it means for their monthly finances. Our modelling suggests a typical 55-year-old on average earnings would need to find around an extra &pound;74 every month - and if that's difficult for someone on average earnings, it'll be even harder for those on lower incomes.</p>

<p>&quot;Everyone loses broadly the same year's State Pension, but replacing it isn't equally affordable. The cash amount may be similar, but it takes a much bigger bite out of the budget for someone on average earnings than it does for a higher earner. That's why giving people plenty of notice of any changes is so important.&quot;</p>

<p>&quot;This also assumes people will continue working and contributing to their pension until they retire, although for some that might not be realistic. Whether because of ill health, caring responsibilities or physical demands of their job and anyone hoping to retire earlier or reduce their hours will have even less time to plug the gap. Even relatively small increases to pension contributions can make a meaningful difference if they're made early enough, whereas leaving it until the final years before retirement makes catching up far more difficult.&quot;</p>

<p> </p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/typical-55-year-old-may-need--74-month-extra-if-spa-rises-26934.htm</link>
<pubDate>Mon, 20 Jul 2026 10:05:00 GMT</pubDate>
	</item>
	<item>
		<title>What Should Be Top Of Pm Burnham s Pensions Agenda</title>
		<description><![CDATA[<p><strong>By Jonathan Griffith, Partner & Head of Endgame Innovation, Laura Amin, Partner, Head of Pensions, Charlie Finch, Partner, Jon Forsyth,Partner and Head of Pensions Developments</strong></p>

<div><strong>Pension scheme surplus</strong></div>

<div>A key priority is surplus use for pension schemes. The Department for Work and Pensions has now issued draft regulations on surplus use alongside a statement from The Pensions Regulator.</div>

<div> </div>

<div><strong>Jonathan Griffith, LCP Partner and Head of Endgame Innovation, said:</strong> &ldquo;The publication of draft regulations on surplus extraction is a major milestone in turning the government&rsquo;s ambitions into a practical reality, and the confirmation that the new regime is expected to be in force from April 2027 was very welcome. For the first time, schemes, sponsors and trustees have a much clearer picture of how surplus sharing could work, albeit we expect actual surplus sharing deals to be more varied beyond what is covered in TPR&rsquo;s statement. We are already seeing growing interest from schemes exploring these new flexibilities. In a recent LCP webinar poll, nine in ten respondents said they were planning to consider releasing surplus under the new regime.</div>

<p>&ldquo;The prize is significant. Based on LCP analysis, we estimate that FTSE 100 companies with UK DB schemes currently each have an average surplus of around &pound;500 million. That represents a substantial pool of capital that could be put to productive use while maintaining strong member security. The next step must be meaningful engagement with industry, so that reforms are workable in practice and deliver good overall outcomes. &rdquo;</p>

<div><strong>DB superfunds</strong></div>

<div>LCP says another major priority should be the development of the legal framework for DB superfunds, with a substantial part of the Pension Schemes Act dedicated to formalising this.</div>

<p><strong>Laura Amin, LCP Partner and Head of DB Consolidation, commented:</strong> &ldquo;Although it was disappointing to see earlier this week the delay in the timeframe for delivering draft superfund regulations to Q1 next year, we expect the government will want to drive forward delivering the new rules. Their focus should be on creating a viable superfund market which works effectively for providers, their investors, trustees and sponsors and which can deliver attractive solutions for members with suitable long-term protections in place.</p>

<p>&ldquo;With at least three new superfunds seeking assessment this year, we expect more superfunds to be operating from next year. This will mean greater competition with increased choice for trustees and sponsors as they consider the best long-term solution for their schemes.&rdquo;</p>

<div><strong>Endgame strategy</strong></div>

<div>LCP also says that policymakers should continue to support innovation and choice across the whole DB endgame market, rather than favouring any single solution. Alongside surplus-sharing and superfunds, the buy-in and buyout market remains a highly successful part of the UK pensions system and will continue to be the preferred destination for many schemes, with 2025 being a record-breaking year for deals.</div>

<p><strong>Charlie Finch, Partner in LCP&rsquo;s Pension Risk Transfer team, commented:</strong> &ldquo;The Pension Schemes Act has laid the foundations for greater innovation through surplus-sharing and a permanent superfund regime. The priority now must be implementing these reforms in a practical way to give trustees and sponsors a range of viable endgame options.</p>

<p>&ldquo;It&rsquo;s also pleasing to see wider industry innovation such as the &ldquo;sponsor swap&rdquo; solution where Stagecoach transferred their &pound;1.2bn scheme to Aberdeen &ndash; the recent Ministerial statement rightly supported such innovation and we would encourage any regulatory intervention to be considered carefully to ensure an appropriate balance between facilitating innovation and maintaining suitable guardrails to protect members.</p>

<p>&ldquo;At the same time, policymakers need to recognise the enormous success of the UK buy-in market, with the insurance regime providing robust long-term security at highly competitive pricing for schemes of all sizes. This will continue to be the endgame solution of choice for many schemes. The policy objective should not be to favour one approach over another, but to create a stable framework where insurance, superfunds, run-on and other innovative strategies can all flourish, giving trustees the confidence to choose the option that best meets their members' needs.</p>

<p>&ldquo;Getting that balance right will be critical if the UK is to unlock the full potential of the &pound;1 trillion plus of DB pension assets and create one of the world's most innovative and competitive pension endgame markets.&rdquo;</p>

<div><strong>Strategic decisions for schemes and sponsors</strong></div>

<div>Looking more broadly across the pensions landscape, LCP says ministers should now focus on certainty, sequencing and meaningful consultation, given the wide range of strategic decisions currently facing trustees and sponsors.</div>

<p><strong>Jon Forsyth, LCP Partner and Head of Pensions Developments commented:</strong> &ldquo;There is a huge amount on Trustees&rsquo; and sponsors&rsquo; agendas, and some very important strategic decisions for them to make and changes to implement. On the DB side alone, we have major developments on surplus and endgame, more to come from DWP and TPR on Trusteeship, a way forward on the Virgin Media issue, PPF regulations to come, and changes to inheritance tax with additional administrative requirements. And that&rsquo;s before we add the ongoing Pensions Commission and the big challenges with pensions adequacy, plus of course the myriad developments in DC and CDC.</p>

<p>&ldquo;There are great opportunities to improve things for schemes, members, and sponsors, and we very much support the government pushing ahead with the current reforms. But it is equally important to take a long-term view when it comes to pensions policy, and to consult meaningfully with industry on any future changes. Working towards a more stable, long-term policy framework for pensions should be the name of the game.&rdquo;</p>
]]></description>
		<link>https://www.actuarialpost.co.uk/article/what-should-be-top-of-pm-burnham-s-pensions-agenda-26937.htm</link>
<pubDate>Mon, 20 Jul 2026 10:05:00 GMT</pubDate>
	</item>
</items>