In the first six months of 2026, both insurance and reinsurance rates declined by 4% gross of trend and 6% net of trend. Insurance softened at approximately twice the pace in 2025, while reinsurance softened three to four times faster, marking a clear acceleration in weaker rating conditions.
Between 2017 and the market peak in 2023, rates net of claims and exposure trend increased by approximately 50% cumulatively. By July 2026, around 65% of these rate-strengthening gains had been eroded, according to the SIMS insurance rate index.
The survey draws on approximately $300 billion in gross written premium over a 10-year cycle, including $50 billion in 2025 and $29 billion in the first half of 2026. It covers specialty insurers operating in the London, Bermuda and U.S. excess and surplus (E&S) markets. Unlike surveys based on broker-derived data, SIMS relies exclusively on insurer-owned data provided by participating clients of WTW’s Insurance Consulting and Technology business.
Richard Clarkson, Global Market Leader, Global Specialty, WTW, said: “SIMS uniquely captures both 1 January and 1 July renewals, providing the market with granular insights. Insurance rate movements in the first half of 2026 were broadly consistent with the 1 January renewals, with a decline of 4% gross of trend compared with 5%. Against this backdrop, the 1 July results point to accelerating softening, with rates down 6% gross and 9% net. Rate movements across most individual classes also show no slowdown.”
Beneath the headline figures, individual markets follow different insurance cycles. Property showed the steepest declines, with rates down 17% net of trend at the 1 July renewals as softening accelerated from 2025. Energy and Financial and Professional Liability (FINEX) recorded high-single-digit reductions net of trend, although early signs of stabilisation emerged in U.S. FINEX. Marine declined by mid-single digits, while Aviation and Accident & Health posted low-single-digit reductions.
In Casualty, rate increases of 6% at the 1 July renewals are no longer sufficient to offset the estimated claims trend of 8% (in excess of exposure trend), resulting in an effective 2% rate reduction. This was not yet evident in the 1 January renewal data and is significant given continuing concerns about rate adequacy in the class.
In the first half of 2026, all 15 material insurance and reinsurance classes recorded net-of-claims-trend rate decreases.
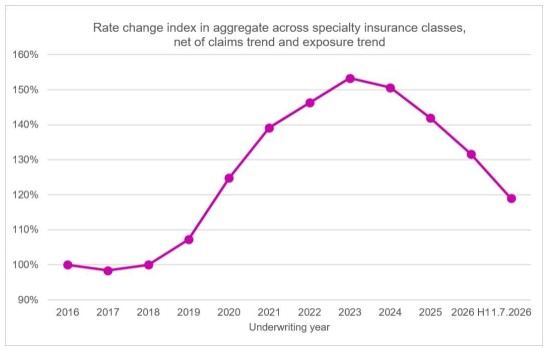
The reported figures represent the survey participants’ latest view of claims trend for all years, thus providing an up-to-date picture of the full cycle.
SIMS uses market-derived data to provide a consistent view of risk-adjusted rate changes across specialty classes and key geographies. WTW clients use these insights to validate business plans, compare pricing trends, assess rate adequacy for new and renewal business, support reserving, and strengthen benchmarking and performance management.
|


.jpg)




(2).jpg)