Significant new analysis from Standard Life highlights the opportunity for workplace pension contribution reform to substantially improve the retirement prospects of younger workers, while warning that changes to contribution rates alone will come too late for many of those approaching retirement.
The analysis shows that today's automatic enrolment system could leave those entering the workforce in their early twenties short of the income needed to achieve a Moderate standard of living in retirement. However, gradually increasing pension contributions from 8% to 12% could significantly strengthen their retirement outlook over the course of their working life.
The picture becomes progressively more challenging for older generations. Those in their fifties and sixties have less time to benefit from increased contributions and investment growth, meaning reforms that could transform outcomes for younger workers will have a much more limited impact for those already approaching retirement.
The analysis comes amid renewed focus on pensions adequacy following the revival of the Pensions Commission, whose interim report estimated around 15 million people are currently under-saving for retirement. Standard Life modelled what different groups of workplace pension savers are currently on track for and compared this against an Australian-style phased increase in contributions – a 0.5 percentage point annual increase from 8% until default contributions reach 12%.
£85,000 retirement boost for young workers
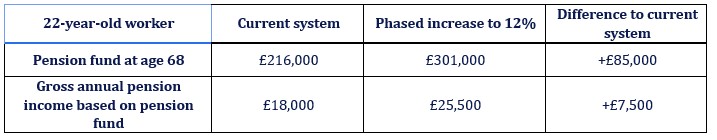
A 22-year-old entering the workforce on a salary of £25,000, around minimum wage, could build a pension pot of around £216,000 in today's money under the current system. Based on current annuity rates, this could generate around £18,000 in gross pension income a year. Combined with the full State Pension, this would leave them short of the income needed to achieve a Moderate Retirement Living Standard.
However, relatively small increases in pension contributions over the course of their working life could significantly strengthen their retirement prospects. If default contributions increased by 0.5 percentage points each year from 2030, rising from 8% to 12%, the same worker could instead build pension savings of around £301,000, £85,000 more at retirement.
This additional saving could generate around £7,500 more gross pension income a year, taking annual pension income to around £25,500. Combined with the full State Pension of £12,547.60 a year, this would provide total gross annual income of around £38,000, enough to meet the £37,732 pre-tax income needed for a Moderate Retirement Living Standard .
The Australian experience demonstrates how contributions can be increased gradually over time, giving employees and employers time to adapt while improving long-term retirement saving. Standard Life research shows there is appetite for a similar approach in the UK, with 69% of adults willing to pay slightly more into their pension alongside their employer if it meant a better retirement income.
Graph: Difference in pension fund value at age 68 from gradual increase to default auto-enrolment pension contributions from 8% to 12% (from 2030-2037)
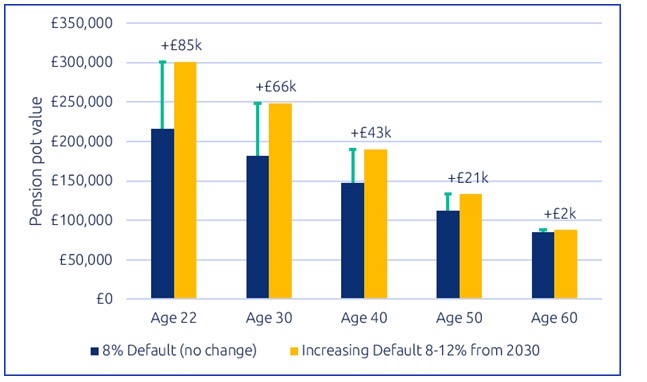
Standard Life analysis: values shown in today's money terms. Pensions projections assume retirement at age 68 and are based on average DC pension pot size by age. Contributions increase by 0.5 percentage points from 2030-2037. Figures are an illustration and are not guaranteed.
Emma Furlonger, Managing Director for Workplace and Retail Intermediary at Standard Life, comments: "The opportunity to make progress on pension adequacy is within our grasp, and our analysis shows that small, gradual increases in pension saving have the potential to significantly improve retirement outcomes for future generations. The experience of other countries demonstrates that phased contribution increases can work, balancing the benefits of higher long-term saving with the need to give employees and employers time to adapt.
"With the Pension Commission's recommendations expected next year, there is an opportunity to set out a comprehensive package of reforms to improve retirement adequacy, combining gradual increases in contributions with measures such as removing the lower earnings limit and bringing younger workers into pension saving earlier."
Clock is ticking for Gen X who shouldn’t wait for reform
Younger workers have decades over which a gradual increase in contributions can build their pension savings, but the picture is very different for those approaching retirement. Many workers in their fifties and sixties will need to act now to strengthen their financial resilience in later life or risk reaching retirement without the income they need. This generation is caught between those before them, who were more likely to benefit from defined benefit pensions, and younger generations whose working lives will be shaped largely by automatic enrolment.
Under a phased increase from 2030, someone aged 60 would see their pension pot increase by just £2,000, with contributions not even reaching 12% before they reach state pension age.
For those with limited time to build their retirement savings, higher default contributions therefore cannot provide the whole answer. Those who can afford to may need to consider voluntarily increasing their pension contributions, while wider support is needed to help people remain in the workforce, build skills and continue to earn and save where they are able to do so.
Catherine Foot, Director at The Standard Life Centre for the Future of Retirement, comments: “The saving challenge remains greatest for those closer to retirement, particularly people in their late fifties and early sixties. Many Gen X are approaching retirement having missed out on a full working lifetime of automatic enrolment, while also seeing the shift away from defined benefit pension schemes that previous generations were more likely to rely on. As a result, many are reaching later life with less pension wealth than they need and less time to close the gap.
“For this group, waiting for incremental increases in contribution rates will not be enough, meaning action is needed now. Those who can afford to increase pension contributions should consider doing so, but we also need targeted intervention to help more people remain in work and continue earning and saving for longer. This includes supporting people who are balancing caring responsibilities or living with ill health to access flexible employment opportunities, strengthening their retirement security and financial resilience.
“Improving retirement outcomes requires a long-term strategy for future generations, but there is an equally pressing need to address the challenges facing those approaching retirement today.”
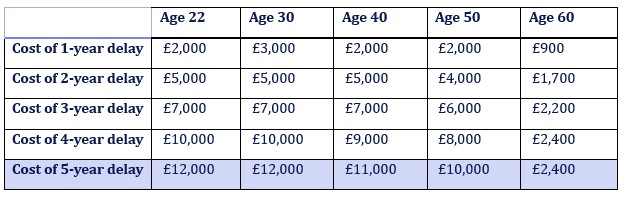
Cost of delay
Standard Life believes action to improve pension adequacy should begin as soon as possible, with 2030 likely to be the earliest realistic date for a phased increase in pension contributions to start. The modelling shows that delaying reform beyond then could have lasting consequences for future retirees.
For example, a five-year delay could reduce retirement savings by up to £12,000 for younger workers, leaving fewer people with the level of savings needed to achieve a Moderate standard of living in retirement.
|