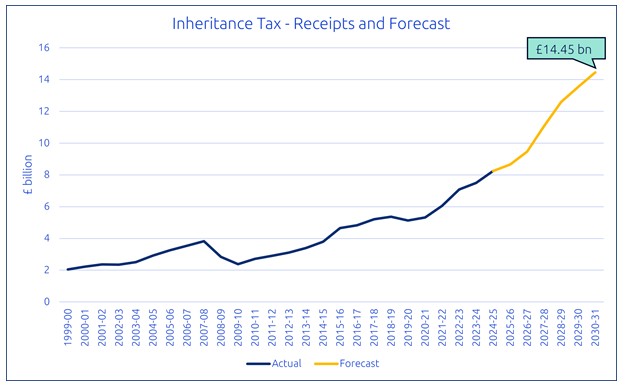
"The change comes against a backdrop of record monthly IHT receipts in June 2026, with the frozen nil-rate band and rising asset values bringing more estates into the scope of IHT. Including pensions will widen the potential IHT exposure further, creating the conditions for a ‘perfect storm’, with annual receipts projected to rise from £8.7bn in 2025/26 to £14.5bn by 2030/31.
"A significant amount of work has already taken place to prepare clients. Last year, advisers estimated that, on average, around 40% of their clients would require a review of their financial plans ahead of the change. Those reviews will have looked at areas such as how retirement income is taken, the role of alternative products such as bonds or trusts, and different approaches to passing on wealth, including gifting strategies.
"The next six months will be about refining plans rather than rushing into decisions that could have long-term consequences. Amid all the noise, it's important not to lose sight of the fact that pensions are designed to provide a sustainable income throughout retirement, and the majority of estates will remain unaffected by the change."
Six months to go checklist for advisers and clients
1. Look at potential IHT exposure
Estate values and circumstances change, so assess the value of pensions alongside the wider estate and available allowances.
2. Stress-test the retirement income plan
IHT is only one part of the picture. Check that the plan still provides the income and flexibility the client needs throughout retirement, including enough money for unexpected costs.
3. Which assets are used, and when
The IHT change could affect long-standing assumptions about the order in which pension and non-pension assets are accessed. Ensure the existing approach remains appropriate.
4. How will wealth be passed on
Talk through what clients want their money to achieve and whether existing arrangements still support those goals. Gifting, trusts and other estate-planning options may all form part of the conversation depending on individual circumstances.
5. Ensure pension admin is in good order
Make sure clients have a clear record of their pension arrangements and that their plans are easy for others to understand. Multiple pension pots can create additional work for personal representatives, although consolidation won't always be the right answer and could mean giving up valuable features or guarantees.
|