The quarterly Defined Benefit (DB) Redress Tracker from leading independent financial services consultancy Broadstone provides an indicator of the level of compensation due to those who were previously ill-advised to transfer out of their DB pension.
Broadstone’s DB Redress Tracker follows the example of an individual who left their scheme in 2018 aged 50, with a pension of £10,000 p.a. which would receive inflation-linked increases when in payment. The potential spread around the example case has been updated to reflect the largest loss and gain in a notional portfolio of cases (previously it showed a narrower spread based on varying the fund return for the single example case).
The Tracker is developed in line with Financial Conduct Authority (FCA) rules for calculating redress with the individual assumed to have invested their funds to earn returns in line with the FTSE UK Private Investor Income Total Return Index.
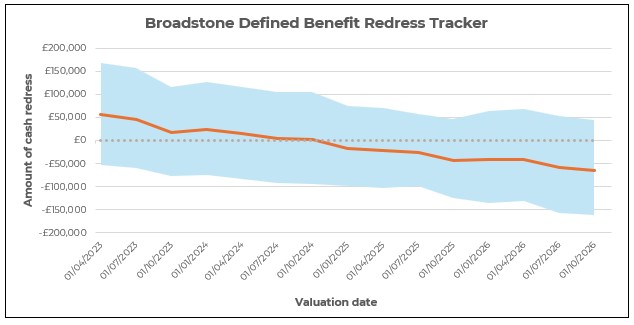
The update for Q4 2026 finds that a gain continues to be expected in most cases meaning that no redress is payable as the consumer is judged to be better off as a result of transferring with the central estimate for Q4 2026 being a gain of around £65,000 (Q3 2026: c£59,000).
The small increase in the gain has largely been caused by rising bond yields through the third quarter which has reduced the value of the defined benefit liabilities given up. Typical investment returns on the receiving personal pension plans were very small and so had a broadly neutral impact on the gain.
The last time that the Tracker found compensation would be payable was two years ago (Q4 2024: c.£2,000) with the central estimate showing a clear and sustained downward trend over recent times. Just over three years ago, when the current FCA rules were introduced, the central estimate found that c.£57,000 (Q2 2023) would be payable.
The central result hides the fact that there will be cases which do result in a loss which would mean that redress is payable. The reasons why a case might result in a loss are varied but typically arise from poor investment strategies post transfer or older transfers .
Simon Robinson, Senior Consultant & Actuary in Broadstone’s Insurance Advisory & Remediation division, commented: “Market changes through the quarter are estimated to have driven redress amounts even lower in Q4 2026 than they have been previously, following the sustained downward trend over the last couple of years. Increased bond yields have been the primary driver over the last three months.
It really is impossible to second guess how redress will look in future quarters. We can see short-term inflationary pressures, which would increase redress levels, but these could be accompanied by higher bond yields offsetting the impact. Future investment returns in equity markets are hugely uncertain and could well be quite volatile.
Where this could give rise to peculiar results is that redress calculated in any quarter is based on market conditions and asset values at the end of the previous quarter. This has the benefit of stability over a three-month period and reduces the ability for either party to cherry pick valuation dates but could mean redress offers made are quite out of date with reality at the point the offer is made.”
|